



$125B Regenerative Medicine Market: Why 22.5% CAGR and Oncology Demand Redefine Growth

Regenerative Medicine Market: Strategic Shifts and Commercial Opportunities in a High-Growth Sector
Market Landscape and Core Challenges
The regenerative medicine market has entered a phase of accelerated expansion defined by sustained capital deployment, expanding clinical applications, and maturing development pathways. Valued at $30.0 billion in 2025, the market has grown at a rapid pace over the past five years and is projected to reach $125.0 billion by 2032, reflecting a compound annual growth rate of 22.5 percent over the forecast period. This trajectory reflects more than incremental adoption; it signals a structural shift in how biopharma developers, medical device companies, and healthcare systems approach tissue repair, disease modification, and personalized intervention.
Behind the headline numbers, the competitive landscape remains moderately concentrated. The top three players command roughly 45 percent of market revenue, while the top five account for approximately 62 percent. This concentration points to a sector where scale, manufacturing capability, and regulatory experience still confer meaningful advantages. Yet the same dynamics leave substantial room for disciplined new entrants and specialized innovators, particularly in indications where clinical differentiation and manufacturing execution can outweigh raw market share.
Three challenges are shaping the sector’s near-term inflection points:
Stem Cells Market
- Manufacturing complexity and cost variability. Cell and gene therapies continue to rely on highly specialized, often labor-intensive production processes. Batch-level manufacturing economics vary widely depending on modality, starting material sourcing, and scale, making cost predictability a persistent operational hurdle.
- Reimbursement inconsistency and access barriers. High therapy prices, combined with uneven reimbursement frameworks across markets and indications, constrain commercial uptake. The challenge is especially pronounced for therapies requiring advanced manufacturing infrastructure, cold-chain logistics, and patient-specific workflows.
- Regulatory pathways in transition. Agencies are creating faster routes for serious conditions, but these pathways demand rigorous evidence packages, clear development strategies, and nimble responses to evolving expectations. Sponsors that can align clinical design, manufacturing strategy, and regulatory engagement early gain a distinct advantage.
For enterprise leaders, these challenges are not merely operational friction. They influence capital allocation, partnership structures, geographic rollout decisions, and the pace at which innovation can be converted into sustainable revenue.
Key Drivers Shaping the Market
The regenerative medicine market is being propelled by several interrelated forces that go beyond general industry momentum. Understanding how these drivers interact is essential for identifying where value is created and where execution risk concentrates.
Technological Innovation and Clinical Breakthroughs
Innovation is expanding both the therapeutic envelope and the operational playbook. Advances in cell engineering, gene delivery, scaffold design, and manufacturing science are enabling more targeted interventions across oncology, musculoskeletal repair, wound care, and rare disease. Importantly, the strongest commercial momentum often comes from therapies that combine a credible mechanism with a feasible manufacturing strategy and a clear patient-selection approach.
Recent developments illustrate this dynamic. In late 2025, the FDA issued draft guidance on expedited programs for regenerative medicine therapies for serious conditions, reinforcing the relevance of RMAT designations and accelerated approval pathways. That regulatory signal is not just procedural; it shapes how developers prioritize indications, design evidence packages, and sequence development steps. At the same time, high-profile approvals continue to validate the model. In early 2026, regulatory milestones included expanded-use decisions for gene therapy in spinal muscular atrophy and the first taxpayer-funded therapy developed through a state-backed research program, demonstrating how public funding, nonprofit leadership, and commercial manufacturing can intersect in modern development models.
Regulatory and Policy Environment
Policy is increasingly a competitive variable rather than a back-end compliance issue. Regulators are signaling greater flexibility in select areas while maintaining high expectations for safety and product characterization. In January 2026, for example, the FDA announced increased flexibility on CMC requirements for cell and gene therapies, including more permissive release criteria in investigational applications and reduced comparability data expectations in certain scenarios.
This evolution creates opportunity for sponsors that can build regulatory strategy into their development thesis from the outset. It also raises the stakes for organizations that treat CMC, release testing, and comparability as afterthoughts. Faster pathways can shorten time-to-market, but they still require disciplined evidence generation, robust manufacturing controls, and careful post-approval planning.
Demand-Side Shifts and Unmet Clinical Need
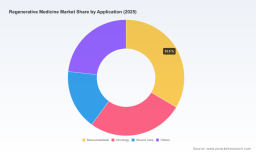
Demand is being reinforced by genuine clinical gaps across multiple indications. Musculoskeletal regeneration, oncology, and wound management continue to represent substantial areas of opportunity, each with distinct patient populations, treatment pathways, and reimbursement dynamics. Across these applications, the commercial pull is strongest where regenerative approaches can offer durable benefit, reduced downstream care burden, or alternatives where existing options are limited.
At the same time, adoption depends on more than clinical promise. Providers and payers weigh operational feasibility, treatment logistics, and total cost of care. Therapies that can demonstrate not only efficacy but also manageable delivery requirements and predictable patient access are more likely to scale in real-world settings.
Supply Chain Constraints and Cost Structure Pressures
The sector’s growth is also being shaped by supply-side realities. A significant share of manufacturers relies on imported key starting materials, and the patient-specific nature of many therapies compresses the window between collection, manufacturing, and delivery. These factors increase vulnerability to disruption and make resilience a strategic priority rather than a procurement afterthought.
Cost pressure is equally important. Manufacturing economics remain highly variable across modalities and batch sizes, with labor intensity, specialized expertise, and limited scalability for smaller patient populations all contributing to wide cost ranges. This does not mean the sector is inherently unprofitable, but it does mean that margins and long-term viability depend heavily on process design, standardization, and the ability to scale selectively without sacrificing quality or speed.
Competitive Landscape and Leading Strategies
The competitive field spans global biopharma, specialized cell and gene therapy developers, tissue-engineering companies, and innovators in advanced wound and musculoskeletal care. The result is a market that combines deep breadth with sharp differentiation. Not all participants are competing on the same axis, and the winners are increasingly defined by clear strategic positioning rather than broad presence alone.
Several patterns stand out among leading organizations:
- Scaling established modalities with strong clinical franchises. Large global players continue to build on platforms in cell therapy and gene therapy where they already have clinical data, commercial infrastructure, and regulatory familiarity. Their advantage often lies in combining product depth with the ability to support manufacturing, market access, and global rollout.
- Focusing on indication-specific differentiation. Some companies compete by narrowing their footprint to areas where they can build a strong technical and clinical narrative. Tissue-engineered products, scaffolds, and regenerative matrices are natural examples, where surgical workflow integration, product reliability, and clinical evidence can drive adoption in specific procedural settings.
- Pursuing platform and manufacturing leverage. Other organizations emphasize process capability, allogeneic approaches, or manufacturing efficiency as the basis for long-term competitiveness. In a sector where production constraints can limit reach, an organization’s ability to standardize, scale selectively, and reduce cost variability can become a durable moat.
- Expanding through partnership and targeted progression. High-impact submissions and prioritized regulatory reviews show that late-stage execution still matters enormously. A successful resubmission, prioritized review, or expansion into a broader patient population can reset a company’s commercial trajectory quickly, especially when paired with operational readiness.
The field is also changing shape. Consolidation pressures are building where scale, manufacturing sovereignty, and market access capabilities matter most. At the same time, fragmentation persists in niche modalities and specialized applications, allowing smaller innovators to compete through superior product design, focused clinical positioning, or differentiated manufacturing approaches. New entrants that can bring credible science alongside operational discipline remain viable, but the bar for execution is rising.
For decision-makers watching this landscape, the key question is not simply who is largest, but who is best positioned to capture value in a given segment. Competitive advantage is increasingly a function of three things: therapeutic differentiation that holds up in clinical and real-world use, manufacturing reliability that supports consistent supply and acceptable unit economics, and commercial infrastructure that can convert approval into durable adoption.
Future Outlook and Strategic Implications
Over the next three to five years, the regenerative medicine market is likely to be defined less by aggregate growth alone and more by the maturation of its internal structure. Three trends are especially relevant for strategic planning.
Trend 1: Scaling Will Depend on Manufacturing Discipline More Than Ever
As the market grows, the organizations that convert innovation into durable revenue will be those that can make sophisticated therapies reproducible, timely, and economically viable. That means tighter control over starting materials, improved process standardization, and more deliberate choices about allogeneic versus autologous approaches where appropriate. Companies that can reduce variability and improve throughput without compromising quality will be better positioned to expand indications, manage demand volatility, and support broader access.
Commercial opportunity: There is meaningful value in process innovation, supply resilience, and manufacturing partnerships. Enterprises that treat manufacturing as a strategic differentiator rather than an operational cost center are likely to gain optionality in both organic growth and external deal-making.
Trend 2: Regulatory Acceleration and Evidence Expectations Will Co-Evolve
Faster pathways for serious conditions will continue to attract development activity, but they will also intensify scrutiny around the quality of the evidence package and post-approval readiness. The expectation is not simply to reach approval faster, but to reach approval with a credible plan for characterization, manufacturing consistency, and real-world follow-through. Sponsors that align clinical design, regulatory strategy, and CMC early will have an advantage in both speed and durability.
Commercial opportunity: Regulatory strategy is becoming a gating factor for portfolio value. Early alignment with evolving agency expectations can reduce late-stage rework, improve the probability of successful progression, and strengthen positioning in negotiations with partners and access stakeholders.
Trend 3: Access, Reimbursement, and Health System Adoption Will Increasingly Shape Commercial Outcomes
Even compelling therapies face real-world friction if access is uncertain or delivery is operationally burdensome. As the field expands, health systems and payers will place greater weight on total cost implications, care pathways, and practical feasibility. That will reward therapies and commercialization models that account for patient selection, site readiness, logistics, and downstream care burden.
Commercial opportunity: Companies that design for access from the beginning, including site support, evidence generation for economic evaluation, and operational simplicity where possible, will have a better chance of translating clinical success into sustained adoption.
Stem Cell Therapy Market
These trends carry risk as well. Supply concentration, cost volatility, and uneven reimbursement can slow momentum even for clinically strong products. In addition, competitive intensity may rise in segments where early movers have already established familiarity and referral pathways. Organizations should therefore weigh not only therapeutic potential, but also the durability of their manufacturing, regulatory, and commercial positioning under stress.
Actionable Takeaways for Decision-Makers
The regenerative medicine market is expanding quickly, but the distribution of value will depend on execution quality across several fronts. Different stakeholders should emphasize different priorities.
For Manufacturers and Developers
- Build manufacturing resilience into your development thesis. Starting material sourcing, batch consistency, and release strategy should be treated as strategic variables, not just technical tasks.
- Choose indications and modalities with an eye toward feasible scale, patient selection, and evidence efficiency. A narrower, better-supported path can outperform an ambitious but fragile one.
- Align regulatory engagement with product strategy early, especially where flexibility is increasing but expectations remain high. Early clarity reduces costly rework later.
For Investors
- Evaluate not only the science, but also the path to reliable supply and acceptable unit economics. Manufacturing and CMC readiness can be decisive in late-stage value creation.
- Differentiate between therapies with strong clinical narratives and those with credible operational scalability. The two do not always overlap.
- Watch for regulatory momentum that affects development sequencing, but also monitor reimbursement and access dynamics that determine whether commercial potential becomes realized revenue.
For Procurement and Health System Leaders
- Assess regenerative therapies with a broader lens that includes site readiness, logistics, training, and downstream care implications, not just product efficacy.
- Prioritize suppliers and partners that demonstrate supply continuity, quality systems, and realistic delivery expectations, especially for patient-specific or temperature-sensitive products.
- Use evidence packages that account for total cost of care where possible, to support more informed adoption and contracting decisions.
The next phase of growth in regenerative medicine will reward organizations that can combine scientific ambition with operational discipline. Detailed segmentation data, company-level benchmarks, and indication-specific analysis can sharpen these decisions considerably, particularly for teams evaluating market entry, partnership strategy, or portfolio prioritization. For that level of granularity, the full PW Consulting research report provides expanded breakdowns and tailored recommendations designed for direct application in planning discussions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Regenerative Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


