



Cable Glands Market: Why 6.5% CAGR and $2.78B Scale Redefine 2032 Strategy

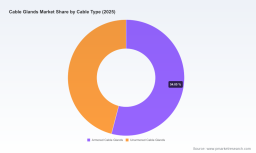
Cable Glands Market: Strategic Trends and Commercial Opportunities (2025–2032)
The cable glands market has entered a phase of structural expansion, driven by renewed investment in industrial infrastructure, energy transition projects, and stricter safety compliance requirements across hazardous and non-hazardous environments. With historical revenue progressing from approximately 1.5 billion in 2020 to 1.8 billion in 2025, the market is positioned to reach roughly 2.78 billion by 2032, reflecting a compound annual growth rate of 6.5 percent. This trajectory signals more than cyclical recovery; it indicates a broader realignment of how industrial, utility, and construction sectors approach cable entry protection, environmental sealing, and hazardous-area compliance. For executives and investors, the opportunity lies not in treating cable glands as commoditized accessories, but in recognizing them as critical components within larger system reliability, asset protection, and regulatory compliance strategies.
The growth pattern observed between 2020 and 2025 demonstrates steady momentum with a notable acceleration toward the end of the period. Revenue levels held firm through 2024 before expanding more sharply in 2025, suggesting that procurement cycles, project backlogs, and compliance-driven replacements began converging at scale. The forecast window through 2032 points to continued expansion, with mid-term projections crossing the 2 billion threshold around 2026 and maintaining upward momentum thereafter. This environment rewards firms that can align product portfolios with application-specific demands, certification pathways, and regional deployment patterns while managing input cost volatility and supply chain complexity.
Market Landscape and Core Challenges
Concentrated Competitive Field With Diverging Growth Vectors
The market operates within a moderately concentrated structure, where a small group of established manufacturers commands a substantial share of revenue and distribution. This concentration creates a dual dynamic: incumbents benefit from brand trust, certification portfolios, and long-standing channel relationships, while smaller and regionally focused players gain traction through specialized materials, price agility, and localized service models. For decision-makers, this landscape means sourcing strategies must balance reliability and compliance assurance against cost, lead-time flexibility, and application-specific performance. The presence of strong European, North American, Asian, and South African manufacturers also indicates that regional preferences, certification regimes, and project types continue to shape purchasing behavior, rather than a single global standard dominating every segment.
Key Challenges and Inflection Points
Several structural pressures are redefining how the market evolves. First, hazardous-area compliance is becoming more rigorous and fragmented across jurisdictions. Cable entry equipment used in explosive atmospheres must satisfy an expanding set of certification expectations, and projects increasingly require documentation that satisfies multiple approval bodies simultaneously. This raises the bar for product design, testing, and time-to-market, particularly for manufacturers serving cross-border industrial customers.
Second, raw material cost fluctuation remains a persistent operational challenge. Brass, stainless steel, aluminum, and engineered plastics form the backbone of cable gland production, and global pricing movements directly affect margin stability and pricing strategy. Suppliers that depend heavily on a narrow set of input materials can experience cost shocks that propagate quickly through contract renewals and tender pricing. This has pushed many manufacturers to revisit material mix decisions, supplier diversification, and product standardization.
Third, the market is facing a subtle but meaningful shift in buyer expectations around performance beyond basic sealing. Industrial customers now evaluate cable glands as part of broader cable management systems, considering strain relief, electromagnetic compatibility, environmental durability, and ease of installation. This expands the evaluation criteria and rewards suppliers that can deliver integrated solutions rather than isolated hardware. At the same time, it pressures manufacturers to avoid over-engineering products where simpler, cost-effective designs would satisfy the application.
Key Demand Drivers
Technical Innovation and Materials Advancement
Product development is increasingly oriented toward versatility, protection performance, and installation efficiency. Manufacturers are expanding families of cable glands that accommodate multiple cable diameters, reduce part complexity, and maintain protection ratings across varied environments. Lamellar and adaptive sealing approaches, for example, have gained attention because they allow a single gland design to serve a broader range of cable sizes while preserving sealing integrity. This kind of design flexibility matters in the field because it lowers inventory complexity for distributors and contractors while reducing the risk of mismatches during installation.
Material choices are also evolving in response to application demands. Brass continues to serve as a widely used baseline for durability and conductivity, but stainless steel and engineered plastics are gaining prominence where corrosion resistance, weight, or chemical exposure becomes decisive. The coexistence of these material pathways indicates that the market is not moving toward a single superior material; rather, it is becoming more application-sensitive. Winners in this environment are those that match material selection to operational conditions, provide clear guidance on suitability, and avoid one-size-fits-all positioning.
Worldwide Connector Backshells Market
Regulatory and Certification Pressure as a Deployment Catalyst
Regulatory requirements are a central force shaping demand, particularly in hazardous locations and utility environments. Cable glands intended for explosive atmospheres must meet recognized standards and obtain relevant certifications, while external connection solutions in defined hazardous zones increasingly require documented compliance. This regulatory backdrop does more than constrain product design; it actively stimulates replacement cycles, upgrade programs, and new project inclusions. When safety and compliance expectations rise, engineering teams specify cable entry hardware more deliberately, and operators often choose certified solutions to reduce liability, streamline audits, and maintain operational continuity.
PW Consulting
Certification complexity also affects commercial dynamics. Products that carry multiple recognized approvals can gain preference in multinational projects, especially where engineers must satisfy overlapping regional requirements. Conversely, manufacturers that can only meet a narrow set of approvals may find their addressable market limited to domestic or lower-risk applications. This dynamic reinforces the strategic importance of certification portfolios as a commercial asset, not merely a technical checkbox.
Demand-Side Shifts in Industrial and Infrastructure Spending
Demand is being supported by broad industrial activity across energy, utilities, manufacturing, and construction. Oil and gas operations continue to require reliable cable entry for instrumentation, control, and power applications, particularly where environmental and explosion-risk conditions are present. Power and utilities projects contribute steady demand as grid infrastructure, substation work, and industrial power distribution expand or modernize. Manufacturing and process industries add further volume through automation upgrades, equipment refreshes, and facility expansions that rely on durable cable connections.
A notable shift on the demand side is the growing emphasis on operational resilience. Procurement teams are increasingly willing to prioritize solutions that reduce maintenance exposure, improve sealing reliability, and support faster installation, even when this means moving beyond lowest-unit-price selection. This does not eliminate cost sensitivity, but it changes the decision calculus: total cost of ownership, downtime risk, and compliance confidence now weigh more heavily in many bids. As a result, suppliers that can articulate performance benefits in operational terms often gain an advantage over those competing solely on specification sheets.
Supply Chain and Cost Structure Evolution
Supply chain conditions continue to influence both pricing and availability. Global trade dynamics, import-export policies, and input material availability interact to shape manufacturing costs and delivery reliability. In this environment, regional production footprints and diversified supplier networks can become strategic advantages, especially for customers who require predictable lead times and stable pricing. Manufacturers that can localize certain production steps or maintain flexible sourcing arrangements are better positioned to absorb external shocks and maintain commercial credibility during procurement cycles.
Tubular Cable Lugs Market
Cost structure pressure is also encouraging product rationalization. Rather than maintaining excessive SKU proliferation, some suppliers are narrowing ranges to high-use configurations, improving production efficiency, and reducing overhead complexity. This approach can simultaneously support margin defense and improve customer experience by making specification and ordering more straightforward. At the same time, differentiation remains essential, because overly simplified portfolios may fail to meet the needs of specialized hazardous-area or high-corrosion applications.
Competitive Landscape and Leading Strategies
Incumbent Positioning and Differentiation
Leading manufacturers are competing on a combination of certification breadth, application coverage, material expertise, and brand trust. Some firms have built strong identities around hazardous-location solutions, where Ex-certified cable glands and explosion protection expertise form the core of their value proposition. Others differentiate through wide industrial portfolios, emphasizing durable seals, strain relief, and compatibility across multiple cable types. A further group focuses on material-grade specialization, offering brass, stainless steel, or plastic nylon options tailored to corrosion, weight, or cost priorities.
Geographic origin and distribution footprint also influence positioning. European manufacturers often lean on engineering heritage, broad certification portfolios, and established industrial relationships. North American and Asian players may gain ground through application breadth, production scale, or targeted product technologies such as multi-diameter sealing systems. South African and Indian manufacturers can compete effectively by combining regional presence, cost competitiveness, and experience in weatherproof, flameproof, and EMC-relevant applications. The result is a market where no single formula dominates; instead, advantage tends to come from aligning product strength with the customer's primary risk profile and purchasing environment.
Strategic Behavior Reflected in Recent Market Activity
Recent supplier activity highlights a shared emphasis on visibility, application demonstration, and relationship development. Multiple manufacturers have participated in major trade events to present cable gland portfolios, industrial wire protection solutions, and related product lines. This pattern suggests that face-to-face engagement remains important in a market where specification decisions often involve engineers, procurement teams, and project stakeholders who value direct product explanation and technical reassurance. Trade presence also serves as a channel for showcasing new designs, reinforcing certification claims, and positioning suppliers within broader industrial ecosystems.
At the same time, regulatory developments continue to reinforce the importance of compliant, well-documented products. Certifications and safety approvals for hazardous locations are increasingly treated as baseline expectations rather than differentiators alone, which pushes competitors to distinguish themselves through reliability, ease of specification, material suitability, and service support. Companies that can integrate compliance credibility with practical installation benefits are better placed to convert interest into long-term contracts.
Market Evolution: Consolidation, Specialization, and New Entrants
The competitive field appears likely to evolve along multiple paths. Consolidation may continue where larger players seek to broaden regional coverage, strengthen certification portfolios, or acquire specialized capabilities. At the same time, specialization will remain attractive for firms that can serve distinct niches, such as polyamide-based designs, high-temperature applications, railway and new-energy fittings, or locally customized hazardous-area solutions. New entrants can still gain relevance if they bring clear technical differentiation, competitive cost structures, or strong regional channel access.
For buyers and investors, this mixed evolution means the market is not simply becoming more concentrated or more fragmented; it is becoming more segmented by use case and compliance profile. That segmentation creates opportunities for targeted growth, but it also raises the importance of understanding which applications and regions offer the most reliable demand signals. Broad positioning without application clarity is increasingly risky, while focused strategies built around specific industries, materials, or certification regimes can generate more predictable returns.
Future Trends and Commercial Implications
Trend 1: Compliance-First Specification Will Become Standard Practice
Over the next several years, hazardous-area compliance and multi-certification readiness will likely become default considerations in more procurement processes. As safety scrutiny persists and project documentation requirements deepen, engineers will favor products that simplify approval verification and reduce the risk of non-conformance. The commercial implication is clear: manufacturers with strong certification coverage and transparent documentation will have an easier path to specification, while those with limited approval footprints may be restricted to lower-risk segments. For investors, compliance readiness should be viewed as a durability factor, because it affects both revenue stability and the ability to enter demanding project pipelines.
Trend 2: Material and Design Choices Will Become More Application-Specific
The market is moving toward more deliberate matching of materials and gland architectures to operating conditions. Stainless steel will continue to gain relevance where corrosion or chemical exposure is a concern; brass will remain important where durability and cost balance matter; engineered plastics will hold value in lighter-weight or cost-sensitive applications. Simultaneously, designs that reduce SKU complexity while retaining performance flexibility will be favored by distributors and installers. The opportunity here lies in helping customers specify correctly the first time. Suppliers that provide clear application guidance, compatible accessory ecosystems, and reliable protection ratings can reduce friction in the buying process and strengthen repeat business.
Trend 3: Industrial Modernization and Infrastructure Renewal Will Sustain Demand
Demand is expected to remain supported by ongoing modernization across power systems, process manufacturing, energy operations, and construction activity. Many of these projects require cable entry hardware that can withstand environmental stress, support safe electrical connections, and meet project-specific regulatory expectations. Because such work often unfolds over multi-year cycles, demand is likely to be less volatile than in discretionary consumer markets. The commercial opportunity is to align product availability, lead times, and technical support with the pacing of large industrial programs, rather than treating each order as an isolated transaction. Firms that can serve as dependable partners in long-duration projects may benefit from stronger retention and more predictable order flow.
Risks and Uncertainties
Despite the positive trajectory, several uncertainties deserve attention. Raw material price swings can compress margins if pricing mechanisms lag cost increases. Regulatory expectations may tighten further or diverge across regions, complicating product planning and certification maintenance. Project delays in energy, utilities, or construction can affect order timing even when underlying demand remains intact. In addition, competition from lower-cost suppliers may intensify in non-hazardous and standard industrial applications, pressuring incumbents to defend value through service, certification, and performance credibility rather than price alone. These risks do not negate the growth outlook, but they highlight the need for disciplined portfolio management and scenario-aware sourcing strategies.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Focus portfolio strategy on application clarity rather than broad volume claims. Identify the highest-value use cases where certification, material durability, and sealing reliability directly influence buying decisions, and align product development, documentation, and channel messaging accordingly. Evaluate SKU complexity with an eye toward both cost efficiency and field usability; reducing unnecessary variants can improve production stability while preserving the configurations that matter most to key segments. Strengthen certification and approval readiness as a commercial capability, not just a technical requirement, because it influences specification speed, project eligibility, and buyer confidence.
For Investors and Strategic planners
Assess companies through the lens of application exposure, compliance breadth, and supply chain resilience. Revenue tied to industries with sustained modernization cycles and hazardous-area requirements may offer more durable growth characteristics than exposure concentrated in highly price-sensitive segments. Pay attention to material mix, production flexibility, and regional distribution strength, since these factors shape margin stability and responsiveness to cost fluctuations. Where possible, prioritize businesses that can demonstrate a clear link between product differentiation and operational value for end users, because that link typically supports pricing discipline and customer retention.
For Procurement and Engineering Teams
Treat cable gland selection as a system-level decision with implications for safety, maintenance, and installation efficiency. Standardize where possible to reduce complexity, but preserve material and certification options for environments that demand them. Evaluate suppliers not only on unit price, but also on approval documentation, compatibility with cable types, protection ratings, and field service support. Where projects span multiple regions or regulatory regimes, prioritize products that simplify compliance verification and reduce the administrative burden of multi-approval procurement.
For organizations that need a deeper, segment-level view of revenue splits, regional dynamics, material trends, and competitive positioning, broader market research can provide the additional granularity required for detailed planning and custom go-to-market decisions. A structured research deep-dive can help translate these strategic themes into specific product priorities, sourcing strategies, and investment screens tailored to the relevant industry and geography.
For detailed analysis of this topic, please visit the official page: Cable Glands Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


