



Vitamin C Market: Why Asia Pacific's 76.88M Scale and 5.35% CAGR Redefine Growth

The Vitamin C (Ascorbic Acid) Market: Strategic Trends & Commercial Opportunities Through 2032
1. Market Overview & Core Challenges
The global ascorbic acid market has demonstrated resilient expansion over the past five years, with revenues rising from approximately USD 147.2 million in 2020 to an estimated USD 186.7 million in 2025. The trajectory points toward continued growth through the forecast window, with the market projected to exceed USD 267.2 million by 2032. This expansion reflects a compound annual growth rate of 5.35 percent, signaling steady but not explosive demand appreciation across downstream sectors. The pace of growth suggests a maturing commodity that is simultaneously undergoing structural repositioning rather than experiencing pure volume-driven expansion.
PW Consulting
A defining characteristic of the current market structure is its moderate concentration. The three largest firms account for roughly 54.7 percent of total revenue, while the top five players capture approximately 68.5 percent. This distribution indicates a landscape where dominant incumbents hold meaningful pricing and supply influence, yet substantial room remains for specialized producers, regional suppliers, and application-focused innovators to compete on differentiation rather than scale alone.
Key Challenges and Inflection Points
Several structural tensions are reshaping how value is created and captured in this market. Understanding these inflection points is essential for any executive evaluating capital allocation, sourcing strategy, or product development roadmaps.
First, the pricing environment has become more normalized but remains sensitive to regional trade dynamics. After a period of pronounced volatility across global supply chains, benchmark pricing settled into a more stable band through early 2026, with market indicators pointing to levels around USD 2.95 per kilogram compared to approximately USD 3.58 per kilogram in the prior year period. This decline reflects Chinese supply normalization and softer near-term demand pull, but it also introduces a strategic dilemma for producers who must balance margin defense with customer retention. Price stability should not be mistaken for pricing power; companies that rely purely on volume without application-specific value addition face renewed compression risk.
Second, trade policy uncertainty continues to create asymmetric opportunities across geographies. Import flows from China into the United States are subject to a 30 percent tariff rate following the expiration of a temporary truce in August 2024. This structural cost element reshapes competitive dynamics for formulators and distributors sourcing from East Asian production hubs, pushing some procurement strategies toward alternative sourcing corridors or prompting reformulation efforts that reduce exposure to tariff-sensitive supply lines. Executives who treat tariff exposure as a static risk rather than a dynamic sourcing variable may find their cost assumptions drifting as trade frameworks evolve.
Third, the raw material cost cycle is introducing both margin relief and planning complexity. In the first quarter of 2026, upstream glucose feedstock prices declined, reducing manufacturing input costs at major ascorbic acid production sites. While lower feedstock costs improve near-term operating economics, they also compress the cost advantage that some producers previously leveraged during periods of input inflation. Companies that use cost tailwinds to invest in capacity upgrades, application development, or sustainability programs will be better positioned than those that simply pass through temporary savings without strengthening structural competitiveness.
2. Key Drivers of Market Change
The market’s direction is being shaped by a combination of technological, regulatory, demand-side, and supply chain forces. These drivers interact in ways that reward firms capable of aligning production strategy with downstream application requirements.
Technological Innovation and Product Differentiation
Innovation in ascorbic acid is increasingly focused on stability, bioavailability, and formulation compatibility rather than pure commodity volume. The launch of premium stabilized forms, such as gold-stabilized ascorbic acid variants introduced for high-performance cosmetics, illustrates how technical differentiation can command higher value in application segments where shelf life, sensory performance, and active efficacy matter. Parallel developments in plant-derived and sustainably positioned ingredients reflect a broader industry push toward cleaner labels and traceable sourcing narratives. These innovations are not marginal; they are reshaping the value hierarchy within the market, separating commoditized bulk supply from specialty grades that justify tighter margins and longer customer relationships.
For producers, the strategic implication is clear: incremental R&D investment in stabilized forms, derivative variants, and application-tailored grades can unlock revenue pools that are less correlated with bulk commodity cycles. For buyers, the implication is equally important: specification decisions increasingly involve performance trade-offs, compatibility with formulation systems, and total cost of ownership rather than price-per-kilogram alone.
Policy and Regulatory Environment
Regulatory developments are acting as both a constraint and an enabler. Compliance requirements around purity, documentation, and application-grade certification continue to raise the bar for suppliers serving pharmaceutical and food sectors, reinforcing the advantage of producers with mature quality systems and audit-ready operations. At the same time, regulatory recognition of sustainability practices is beginning to influence procurement decisions. The awarding of high-quality development benchmark status to a producer’s pilot project on comprehensive waste utilization from vitamin C fermentation signals that environmental efficiency is moving from a supporting initiative to a qualification criterion in certain markets and customer conversations.
Policy-induced cost elements, including tariffs and trade-flow changes, also influence where value is created. Firms that can anticipate regulatory shifts and adjust supply routing, certification positioning, or regional manufacturing footprints gain a planning edge. Rather than reacting to compliance or trade changes after they affect quoting cycles, companies that build scenario planning into sourcing and capacity decisions can protect margin and customer confidence more effectively.
Demand-Side Shifts in Consumer and Corporate Behavior
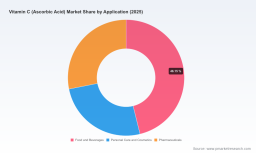
Demand patterns are being shaped by three overlapping currents. In personal care and cosmetics, there is sustained interest in vitamin C as an active ingredient associated with visible skin benefits, which supports demand for grades with enhanced stability and compatibility in complex formulations. In food and beverages, fortification and clean-label positioning continue to drive usage, though formulation constraints and label expectations requiregrades that integrate cleanly into varied processing conditions. In pharmaceuticals, demand remains tied to both established therapeutic applications and broader nutraceutical trends, with buyers placing a premium on consistency, documentation, and supply reliability.
Vitamin A Market
Across these segments, the common thread is a shift from transactional purchasing toward specification-driven partnerships. Customers are increasingly willing to pay for performance assurance, batch-to-batch consistency, and responsive technical support when those attributes reduce downstream risk. This behavior shift benefits suppliers who can demonstrate application competence, not merely capacity availability.
Supply Chain and Cost Structure Evolution
The supply side is undergoing a gradual rebalancing. Chinese producers, which represent a significant share of global output, are increasingly emphasizing value-over-volume approaches, with pricing stabilization and modest upward movement observed after an extended period of volatility. This recalibration suggests that the market is moving away from pure capacity-led competition toward a more nuanced environment where grade differentiation, sustainability performance, and supply reliability contribute to competitive positioning.
Cost structure dynamics also reflect feedstock movements, logistics considerations, and regional production economics. The decline in glucose feedstock costs provides temporary margin support, but the longer-term question is whether producers will convert that support into durable advantages through process improvements, byproduct utilization, and energy efficiency. Firms that treat input cost fluctuations as an opportunity to fund structural upgrades will build more resilient operating models than those that treat lower costs as a transient reprieve.
3. Competitive Landscape and Leading Strategies
The competitive field features a mix of globally positioned specialty players and large-scale producers with strong regional footprints. The strategic contrast among them highlights different pathways to value capture in a market where concentration is meaningful but not absolute.
Strategic Positioning Among Leading Companies
Dsms-firmenich has concentrated its ascorbic acid offering around a high-purity, pharmaceutical-grade positioning linked to a dedicated production site in Scotland, positioning itself as a Western-manufactured source for customers prioritizing traceability and grade consistency. This specialization reflects a deliberate choice to compete on quality assurance and application credibility rather than on sheer bulk volume.
BASF SE combines bio-based and standard ascorbic acid production through China-based facilities with collaborative development activity targeting nutraceutical and sustainable applications. Its approach blends scale with applied development, using partnerships and formulation-oriented innovation to expand relevance beyond conventional bulk supply.
Chinese producers such as CSPC Pharmaceutical Group, Northeast Pharmaceutical Group, Zhejiang NHU, Shandong Luwei Pharmaceutical, and North China Pharmaceutical Group illustrate a range of scale and application orientations. Several of these firms emphasize bulk and derivative production across pharmaceutical and food-grade standards, while others integrate ascorbic acid output with broader active pharmaceutical ingredient or peptide lines. One notable operational signal is the focus on waste recycling and comprehensive utilization in fermentation processes, a theme that aligns with both cost efficiency and sustainability positioning.
Evonik Operations GmbH has leaned into premium stabilized forms for cosmetics, targeting high-performance applications where enhanced stability and bioavailability justify a differentiated value proposition. This strategy demonstrates how a firm can compete in a mature market by building a specialty-grade identity rather than competing primarily on commodity pricing.
Differentiation Advantages and Competitive Evolution
The landscape is evolving along several axes. One is the divergence between bulk-oriented suppliers and specialty-grade innovators. Bulk producers compete on capacity, cost discipline, and reliability of large-volume supply, while specialty players differentiate through grade design, formulation support, and compliance narratives. Both models can be viable, but they require distinct operating postures, sales approaches, and capital priorities.
A second axis is regional repositioning. Trade policy and tariff exposure are encouraging some buyers to diversify sourcing and some producers to consider how manufacturing location affects customer affordability and supply continuity. This does not necessarily mean a wholesale exit from any one geography, but it does increase the value of flexible supply arrangements and transparent cost explanations.
A third axis is sustainability and process efficiency as competitive attributes. Waste utilization, energy efficiency, and feedstock optimization are moving from back-office improvements to elements of customer-facing storytelling and qualification. In a market where multiple suppliers can meet baseline purity requirements, process credibility and sustainability performance can become meaningful selection criteria.
New entrants and smaller specialists are unlikely to displace the largest incumbents through scale alone, but they can gain footholds by targeting underserved application niches, offering superior technical service, or introducing stabilized and derivative forms that address specific formulation pain points. The more probable trajectory is continued differentiation layered onto a concentrated base, with competitive advantage flowing to firms that match grade portfolio, supply reliability, and application expertise to the right customer segments.
3-O-Ethyl-L-Ascorbic Acid Market
4. Future Trends and Commercial Opportunities
Looking ahead across the next three to five years, several trends are likely to shape the market’s evolution and create actionable opportunities for firms that prepare early.
Trend 1: Continued Shift from Commodity Pricing to Application-Based Value
As stabilized forms, derivative variants, and grade-specific certifications become more established, a larger share of revenue is likely to migrate toward product categories where performance attributes matter more than bulk cost. This creates opportunities for producers to expand margins through specification-led offerings and for buyers to reduce downstream formulation risk by selecting grades that align with their processing and shelf-life requirements. Companies that invest early in application testing, technical documentation, and customer co-development will be better positioned to capture this shift than those that continue to compete mainly on tonnage and headline price.
Trend 2: Supply Chain Realignment Around Resilience and Sourcing Flexibility
Tariff exposure, regional cost differences, and customer sensitivity to supply continuity are likely to keep sourcing diversification on the agenda for formulators and distributors. Over the next few years, this should encourage more dual-sourcing architectures, greater attention to lead-time reliability, and more explicit conversations about total landed cost rather than ex-works price alone. For manufacturers, the opportunity lies in providing predictable supply, transparent cost logic, and the ability to serve multiple grade requirements from a coherent operational base. For procurement teams, the opportunity is to structure supplier relationships that balance cost efficiency with resilience, rather than optimizing narrowly for the lowest unit price.
Trend 3: Sustainability and Process Efficiency as Procurement Criteria
Waste utilization, feedstock efficiency, and energy-conscious manufacturing are expected to become more prominent in supplier evaluation, especially where customers face their own sustainability reporting obligations or where regulatory and consumer expectations reward cleaner production narratives. Producers that can demonstrate measurable efficiency gains and credible environmental practices may find these attributes translating into preferred-supplier status in certain segments. The risk for lagging firms is not immediate disqualification, but gradual erosion of relevance as sustainability becomes a tie-breaker in multi-supplier selection processes.
Risks and Uncertainties
Several factors could alter this trajectory. Continued trade-policy changes could reintroduce cost volatility in specific corridors, particularly where tariff exposure remains significant. Demand softness in one or more application segments could pressure utilization and reassert price competition, especially if feedstock cost relief encourages a return to volume-focused behavior. Regulatory tightening around documentation, purity, or environmental performance could raise compliance costs for less-prepared operators. Finally, innovation adoption may be uneven; if stabilized or specialty grades fail to achieve broad formulation acceptance, the anticipated value migration could stall, leaving bulk pricing dynamics more influential than expected.
5. Strategic Recommendations for Decision-Makers
Different roles face different priorities, but several strategic actions are broadly relevant across the industry.
For Manufacturers and Producers
- Align product portfolios with application value rather than aggregate tonnage. Invest in stabilized and derivative grades, technical documentation, and formulation support where customers are most likely to pay for performance assurance.
- Use feedstock cost relief and operational improvements to fund process efficiency, waste utilization, and energy optimization. These investments strengthen margin durability and build credible sustainability positioning that can support customer qualification.
- Build sourcing and supply flexibility into customer engagements. Transparent cost logic, reliable lead times, and the ability to serve multiple grade requirements can differentiate a supplier even in a concentrated market.
For Investors
- Evaluate exposure along the value gradient. Companies with specialty-grade portfolios, strong quality systems, and application-oriented customer relationships typically have more resilient margin profiles than pure bulk players in a normalizing price environment.
- Monitor regional risk factors, including tariff exposure and supply re-routing dynamics, as part of valuation assumptions. Cost structures that appear favorable in one trade scenario may shift materially if sourcing patterns change.
- Track sustainability and process-efficiency milestones as indicators of competitive positioning. In a market where baseline purity is increasingly table stakes, operational credibility can be a meaningful differentiator in customer retention and premium segment access.
For Procurement and Sourcing Leaders
- Shift evaluation frameworks toward total cost of ownership and supply reliability. Price-per-kilogram remains relevant, but grade compatibility, batch consistency, lead-time predictability, and documentation quality can have a larger impact on downstream outcomes.
- Consider diversified sourcing architectures that balance cost efficiency with resilience, especially where tariff exposure or single-region dependence creates hidden vulnerability.
- Engage suppliers early on specification needs and application constraints. Earlier collaboration can reduce reformulation risk and improve the fit between grade selection and end-product performance requirements.
The vitamin C market is not simply expanding; it is recalibrating around grade differentiation, supply resilience, and application-driven value. For executives navigating this environment, the most useful next step is a detailed look at segment-specific dynamics, regional cost and tariff exposure, and the competitive positioning of individual suppliers relative to end-use requirements. A comprehensive industry report can provide the deeper segmentation detail, competitive profiling, and scenario context needed to translate these strategic themes into concrete sourcing, investment, and product-development decisions.
The evolving balance between bulk supply and specialty-grade value, the impact of trade and feedstock dynamics, and the growing role of sustainability in supplier evaluation all point to the same conclusion: informed, segment-level intelligence will matter more over the coming years than broad market summaries. Decision-makers who secure access to detailed market data and tailored strategic guidance will be better equipped to act before structural changes become obvious to the entire industry.
For detailed analysis of this topic, please visit the official page: Vitamin C (Ascorbic Acid) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


