



Thionyl Chloride Market $935M by 2032: Why 4.8% CAGR Signals a Strategic Shift

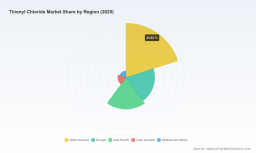
Thionyl Chloride Market Outlook 2026-2032: Strategic Shifts and Commercial Opportunities
Market Context and Core Challenges
The thionyl chloride market enters the 2026-2032 forecast period from a foundation of steady expansion. Recorded revenue progressed from USD 531.23 million in 2020 to USD 679.8 million in 2025, reflecting consistent demand accumulation across multiple end-use sectors. The forward trajectory points toward USD 695.83 million in 2026, climbing to USD 935.1 million by 2032, with a compound annual growth rate of 4.8 percent over the forecast horizon. This baseline growth establishes a recognizable macro pattern, but the market structure beneath these figures is undergoing meaningful recalibration that warrants closer attention.
One defining challenge is the uneven maturity of application segments. Industrial synthesis, pharmaceutical intermediates, and electrolyte-related uses do not expand at the same pace or respond to the same cost drivers. Buyers in mature segments increasingly demand consistency, purity, and supply reliability, while growth-oriented segments push for volume access and price stability. Suppliers must reconcile these divergent expectations within a single production and distribution framework, which places pressure on specification management, inventory planning, and customer segmentation.
PW Consulting
A second challenge arises from regulatory fluidity. Chemical handling, transport classification, and cross-border trade documentation remain subject to periodic adjustments that can alter lead times, compliance costs, and regional sourcing strategies overnight. The market has seen targeted updates that change the administrative burden around specific battery-related uses, and such changes can redirect procurement flows between jurisdictions without any underlying shift in chemical demand. Organizations that treat regulation as a static compliance checklist rather than an active market variable risk missing sourcing opportunities or overestimating friction in certain corridors.
A third challenge is feedstock linkage and cost predictability. Thionyl chloride production depends on the reaction of sulfur trioxide with sulfur dichloride, making the availability and price behavior of sulfur dichloride a central input risk. Because this feedstock is tied to refining and chlorination byproduct streams, supply can be influenced by upstream plant turnarounds, regional capacity dynamics, and energy cost movement. In a market expanding at a mid-single-digit rate, input volatility can compress margins more quickly than end-market demand can offset them, especially for producers with limited feedstock flexibility.
Strategic Implications of the Current Landscape
The combination of polarized application growth, regulatory variability, and feedstock sensitivity means that aggregate market size alone is an insufficient planning tool. Executives need to understand where growth is concentrating, which supply routes are becoming more or less friction-prone, and how specification requirements differ across customer types. The next phase of advantage will belong to firms that can align product grade, logistics, and compliance posture with the specific end-use profile they serve, rather than competing primarily on broad availability.
Key Drivers Shaping Market Direction
Technology and Application Innovation
Innovation in downstream applications is one of the most important demand-side forces in this market. In battery-related uses, thionyl chloride functions as a key electrolyte component in lithium thionyl chloride cells, where long service life and stable performance under demanding conditions support adoption in industrial, utility, and specialized remote deployments. Improvements in cell design, energy density, and operational reliability expand the addressable base for these batteries and, in turn, reinforce demand for high-purity electrolyte-grade material. For manufacturers, the strategic implication is clear: application-level performance gains can create durable demand pull, but they also raise expectations for consistency and traceability in the chemical input stream.
Beyond batteries, refinement in organic synthesis and specialty intermediate production continues to broaden the use of thionyl chloride as a chlorinating and synthesizing agent. Process optimization in pharmaceuticals and fine chemicals increasingly emphasizes yield, impurity control, and reproducibility, which favors suppliers able to support tighter specifications and dependable batch quality. Where customers integrate thionyl chloride into multi-step synthesis routes, delivery reliability and documentation quality can become as commercially significant as unit pricing.
Policy and Regulatory Environment
Policy developments are actively reshaping trade conditions in specific segments. Recent guidance from Chinese authorities optimized import and export measures for lithium thionyl chloride batteries containing no more than 1 kg of the chemical, removing licensing requirements from January 1, 2026. This adjustment reduces administrative friction for smaller-format cells and related components moving through China’s trade channels, and it can improve speed-to-market for products that rely on cross-border sourcing of battery-grade material. The broader lesson is that regulatory recalibration does not always function as a barrier; in some cases it realigns cost and timing dynamics in ways that benefit well-positioned supply chains.
At the same time, chemical regulation remains fragmented across regions. Handling standards, transport classification, workplace exposure oversight, and import documentation all vary, and the cumulative compliance burden can influence where production is sited, how inventory is buffered, and which customer segments are most attractive. Market participants that proactively monitor regulatory calendars and map them against their sourcing and distribution footprint can convert policy visibility into a planning advantage rather than reacting after changes take effect.
Demand-Side Shifts in End-Use Behavior
Demand patterns are being shaped by a combination of industrial electrification, specialty chemical expansion, and more selective procurement behavior. Battery-linked applications continue to benefit from the broader push toward long-duration and maintenance-light power solutions, particularly where stability and shelf life matter more than rechargeability. In parallel, pharmaceutical and agrochemical manufacturers are under pressure to improve process efficiency and reduce variability, which increases the value of predictable reagent supply and consistent grade quality.
Procurement teams are also behaving differently. Rather than treating thionyl chloride as a commodity bought primarily on spot price, many buyers now weigh total cost of ownership, including quality risk, lead-time variability, and compliance assurance. This shift favors suppliers that can demonstrate dependable specification control and transparent logistics, and it can create a divergence between customers who prioritize cost above all and those who prioritize supply integrity. Understanding which buyer archetype dominates a given region or application is essential for positioning product offerings and service levels appropriately.
Supply Chain and Cost Structure Dynamics
Cost structure remains tightly connected to feedstock behavior and production efficiency. With sulfur dichloride as the core feedstock for thionyl chloride synthesis, availability is supported by refining byproducts, but that linkage also means supply can be sensitive to changes in upstream operations and regional chlorination capacity. When feedstock conditions tighten, producers with integrated sourcing options or diversified input relationships can better protect margins and maintain delivery continuity.
Worldwide Lithium Thionyl Chloride Cell Market
Logistics and safety requirements add another layer to the cost structure. Because thionyl chloride must be handled and transported under appropriate controls, regional transport conditions, packaging standards, and intermodal coordination can materially affect landed cost and service reliability. In a market where multiple application segments depend on timely delivery, firms that optimize packaging, routing, and inventory positioning can differentiate on reliability even when base pricing remains competitive. The strategic opportunity lies in treating logistics and feedstock coordination as part of the core value proposition, not as a back-office function.
Competitive Landscape and Leading Strategies
The competitive field is moderately concentrated, with the top three players accounting for roughly 29.4 percent of market revenue and the top five combining for about 39.0 percent. This concentration indicates that leading firms hold meaningful share, but it also suggests substantial room for regional specialists, niche-grade suppliers, and application-focused entrants. The market is not dominated by a single universal model; instead, competitiveness depends heavily on grade focus, geography, and the ability to serve specific end-use requirements with reliable quality and documentation.
Large diversified chemical and specialty material firms are positioned around scale, brand trust, and broad application coverage. Companies such as LANXESS AG maintain a presence that spans high-purity chlorinating agent supply and electrolyte-related uses for long-life lithium thionyl chloride batteries, alongside pharmaceutical, agrochemical, and specialty synthesis demand. Merck KGaA, including its reagent-grade offerings through Sigma-Aldrich Co. LLC, serves laboratory and specialty synthesis customers with a focus on specification clarity and research-grade consistency. These positions are strongest where customers value recognized quality, technical support, and predictable supply over lowest-cost volume purchasing.
Worldwide Titanium Chloride Market
Regional and application-focused producers create value through proximity, responsiveness, and targeted product families. In China, Jiangxi Selon Industrial Co. Ltd. and Shandong Kaisheng New Materials Co. Ltd. participate in fine chemical and specialty materials supply for pharmaceutical, agrochemical, and organic synthesis uses, where local manufacturing and distribution can reduce lead times and improve service continuity. In India, Transpek Industries Ltd. and Bodal Chemicals Ltd. supply thionyl chloride for pesticides, pharmaceuticals, and fine chemical intermediates, aligning production with regional demand clusters in agrochemical and specialty intermediate markets. CABB Group adds another European-oriented presence with chlorinating agent supply for industrial and agrochemical applications.
Differentiation Paths in Practice
The market is shaping up around several identifiable differentiation strategies:
- Grade specialization, where suppliers build reputation and pricing power around technical-grade consistency or pharmaceutical/reagent-grade purity, depending on their target customer base.
- Application alignment, where firms tailor inventory, packaging, and technical support to battery electrolyte needs, organic synthesis workflows, or agrochemical and pharmaceutical intermediate production.
- Regional service depth, where local production, distribution, and compliance knowledge reduce lead-time risk and improve responsiveness for nearby customer clusters.
- Supply resilience, where feedstock coordination, multi-site capability, or inventory positioning is used to protect continuity during upstream disruption or demand surges.
These strategies are not mutually exclusive, but they tend to define distinct competitive identities. A supplier that attempts to compete on every axis at once may dilute focus; one that chooses a defensible specialty and executes it consistently can command stronger customer loyalty and more stable margins.
Market Evolution Trends
Several directional patterns are visible in the competitive landscape. First, the market is likely to see continued differentiation rather than full consolidation into a small number of universal suppliers. Application specificity and regional service needs favor a mixed structure in which global or multinational players coexist with regional specialists and grade-focused niche suppliers. Second, new entrants and expanding local producers are most likely to succeed where they can reduce lead-time risk, match specification expectations, or serve fast-growing application pockets that larger players serve less intensively. Third, customer purchasing behavior is increasingly segmented, which means competitive pressure is not uniform: some segments will remain price-sensitive, while others will reward reliability, documentation quality, and technical support. The firms that understand this segmentation and do not treat the market as a single battlefield will be better positioned to protect share and margin.
Future Trends for 2026-2032
Trend 1: Application-Linked Demand Becomes the Main Growth Engine
Over the next several years, aggregate growth is expected to remain positive, but the more important story is where that growth concentrates. Battery-related electrolyte demand, specialty synthesis, and pharmaceutical and agrochemical intermediates are likely to be among the more influential pockets, each with different specification and supply requirements. The commercial opportunity is to align product offerings, inventory depth, and service models with the application segments that offer the best combination of growth and margin resilience, rather than spreading resources evenly across all uses.
Trend 2: Regulatory Visibility Turns Into a Sourcing Advantage
As trade and handling rules continue to evolve in targeted ways, the ability to anticipate and adapt to regulatory changes will become a stronger differentiator. Adjustments that reduce licensing or administrative burden for specific battery formats can improve trade flow and open short-term pricing or sourcing windows. More broadly, suppliers and buyers that maintain forward visibility into regulatory calendars and regional compliance expectations will be better able to secure inventory, select routes, and negotiate terms from an informed position. The risk is complacency: organizations that wait for disruption to settle before adjusting their plans may leave value on the table or face avoidable friction.
Trend 3: Feedstock and Cost Discipline Shape Margin Outcomes
Because feedstock availability and input cost behavior remain central to production economics, firms that invest in feedstock coordination, procurement diversification, and process efficiency are likely to manage the middle of the market more effectively than those that rely on spot exposure alone. In a 4.8 percent CAGR environment, margin protection depends on more than selling into growth; it also depends on controlling input variability and avoiding reactive purchasing. The opportunity here is operational: companies that treat feedstock strategy and logistics design as strategic levers can improve resilience without needing to win on price alone.
Risks and Uncertainties
Several factors could alter this trajectory. Regulatory adjustments may move faster than anticipated in some regions or stall in others, changing the relative attractiveness of different sourcing corridors. Feedstock conditions could tighten if refining or chlorination byproduct streams are disrupted, pressuring margins for less flexible producers. Demand growth may also become uneven if downstream adoption in batteries or specialty synthesis slows in certain markets, leaving supply better balanced in some segments than others. Finally, competition from regional producers could intensify where local service advantages or cost positions improve, putting pressure on incumbents that depend primarily on scale and brand recognition.
Strategic Actions for Decision Makers
For Manufacturers and Suppliers
Position the portfolio around defensible grade and application profiles rather than treating all demand as interchangeable. Where high-purity or reagent-grade consistency is the main buyer concern, invest in specification control, documentation, and technical support. Where volume and reliability matter more, focus on feedstock coordination, production stability, and logistics design that protects delivery continuity. It is also worth examining whether regulatory changes affecting specific battery-related flows can be used to strengthen regional service advantages or streamline cross-border supply in selected segments.
For Investors and Strategic Buyers
Evaluate opportunities with an application-segment lens. The most compelling cases are likely to combine steady demand characteristics with manageable compliance and feedstock risk, rather than relying on scale alone. When assessing entrants or expansion projects, pay attention to regional service positioning, feedstock relationships, and the ability to serve a specific segment with consistent quality. In a moderately concentrated market with clear niche opportunities, value creation often comes from focusing on the right segment and executing supply reliability well, not from broad horizontal growth.
For Procurement and Supply Chain Leaders
Treat thionyl chloride sourcing as a total-cost and continuity decision, not solely a spot-price exercise. Map the trade and regulatory environment for each corridor you use, especially where battery-related or cross-border flows are involved, so that changes can be anticipated rather than absorbed. Diversify where possible across grade-qualified sources and regions to reduce exposure to localized feedstock or logistics disruption, and align supplier evaluation criteria with the quality and reliability expectations of your end-use application. Buying decisions that reflect specification needs, lead-time risk, and compliance visibility will usually outperform decisions based on headline price alone.
Where to Go Next
The thionyl chloride market is moving through a phase in which aggregate growth is important, but segmentation, regulatory dynamics, and feedstock discipline matter more for business outcomes. Leaders who understand which application pockets are expanding, how trade conditions are shifting, and where supply resilience will be tested are better placed to prioritize investment, sourcing, and competitive positioning. For organizations that need detailed segmentation data, regional breakdowns, grade-level demand patterns, and tailored strategic scenarios, the full PW Consulting research report provides the deeper structure required to move from market-level insight to company-specific action.
For detailed analysis of this topic, please visit the official page: Thionyl Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


