



The Real Drivers Behind Band Saw Blades Market's 5.5% CAGR Growth to 2032

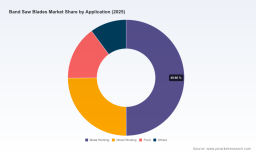
Band Saw Blades Market: Strategic Trends and Commercial Opportunities Through 2032
Market Context and Core Challenges
The global band saw blades market has demonstrated steady expansion over the past half-decade, with revenue valued at approximately USD 1.75 billion in 2025 and a projected trajectory toward the USD 2.5 billion range by 2032. This growth reflects a compound annual growth rate of roughly 5.5 percent, signaling a mature yet resilient sector that continues to attract capital and innovation. The market’s size is supported by broad industrial activity, yet its progression is not uniform across all applications or geographies. Instead, the sector is navigating a set of structural inflection points that will determine which participants capture disproportionate value in the coming years.
One of the most pressing challenges lies in raw material volatility. High-carbon strip steel remains the foundational input for the majority of band saw blades, and its pricing is deeply tied to global steel supply dynamics. When alloy availability tightens or energy costs shift, producers face margin compression that can quickly erode pricing power. This vulnerability is compounded by the fact that advanced blade formulations, particularly those incorporating carbide tips or specialized bi-metal constructions, rely on high-speed steel alloys whose supply chains have shown periodic disruption. Manufacturers that fail to secure forward contracting strategies or diversify alloy sourcing risk being forced into reactive pricing models that undermine long-term profitability.
A second challenge centers on regulatory and compliance complexity. Safety and quality standards in North America and Europe increasingly require periodic inspection, tension testing, and documented quality control protocols. ISO 9001 certification has become a baseline expectation for manufacturers operating in precision metal cutting, while European CE marking compliance ensures that blades meet industrial safety requirements for metal processing equipment. These mandates are not merely bureaucratic hurdles; they shape procurement decisions, increase the cost of market entry, and create a barrier that favors established players with robust documentation and testing infrastructure. At the same time, they open a subtle window for suppliers who can position compliance as a value-added service rather than a pure cost.
Circular Saw Blades Market
A third challenge is the tension between consolidation and niche specialization. The market exhibits notable concentration, with the top three participants accounting for a substantial share of revenue and the top five extending that dominance further. This structure suggests that scale, distribution networks, and brand trust remain powerful moats. Yet it also indicates that the competitive center of gravity is shifting toward differentiated product architectures, application-specific blade designs, and service-integrated offerings. Companies that compete solely on price in commoditized segments face margin erosion, while those that engineer blades for particular material hardness, cut speed, or vibration profiles are building defensible positions. The industry is thus at a crossroads where scale alone will not guarantee advantage, and specialization must be executed with operational discipline.
Key Drivers Shaping Market Dynamics
Technological Innovation and Material Breakthroughs
Innovation in blade geometry, tooth design, and material composition is reshaping performance expectations across metal fabrication, woodworking, and specialized industrial applications. Bi-metal constructions continue to anchor the largest share of product revenue, benefiting from their balance of toughness and edge retention. However, the most consequential advances are appearing in carbide-tipped formulations and optimized tooth profiles that extend blade life in high-production environments and reduce downtime in continuous cutting operations. Recent product launches and catalog updates from leading manufacturers underscore this trajectory. In early 2026, one of Europe’s largest blade producers presented new sawing solutions at a major industry fair in Hamburg, signaling continued investment in next-generation cutting performance. Shortly afterward, another European specialist released an updated product catalog featuring new carbide-tipped band saw blades, reinforcing the shift toward harder-wearing, application-tailored designs. Earlier in 2025, a notable milestone highlighted the upper limit of blade capability when a premium bi-metal blade was selected for use on the world’s largest band saw, with a workpiece capacity exceeding five meters. This deployment illustrates how blade engineering is extending into extreme-scale industrial settings where reliability and dimensional stability are paramount.
PW Consulting
The practical implication for buyers and manufacturers is that performance differentiation is increasingly measurable. Reduced changeover frequency, consistent cut quality across varying material hardness, and resistance to premature tooth wear translate directly into lower total cost of ownership. Suppliers that can validate these claims through documented field performance and application engineering support are gaining preference in procurement processes that once prioritized unit price alone.
Policy and Regulatory Environment
Regulatory frameworks are influencing both product design and market access. Mandatory periodic inspection and tension testing protocols, alongside ISO 9001 and CE compliance expectations, create a compliance layer that affects how blades are specified, sourced, and maintained. These requirements are not uniform across regions, which means multinational operators must navigate a patchwork of standards while maintaining consistent quality. At the same time, safety-driven procurement criteria are becoming more explicit. Plants that operate high-tension or high-capacity sawing equipment are increasingly tying blade purchases to documented conformity and traceability. This environment rewards manufacturers that have built quality management systems into their production workflows and can provide clear evidence of batch consistency, material traceability, and mechanical performance under standardized testing conditions.
For suppliers, the regulatory landscape is a double-edged sword. It raises the cost of participation but also creates a structural preference for proven providers. The companies that treat compliance as a core capability rather than a back-office function are better positioned to win contracts in regulated environments and to expand into markets where safety documentation is a prerequisite for vendor approval.
Demand-Side Shifts in Industrial and Commercial Applications
Demand is being reshaped by the way manufacturers and fabricators approach throughput, material efficiency, and equipment utilization. In metal working, the push for higher productivity in structural steel, super alloys, and heavy-section cutting continues to favor blades that maintain cutting accuracy over extended runs. In wood working and food-related applications, the emphasis leans toward clean cuts, reduced material waste, and blades that perform reliably under variable conditions. Across these segments, procurement teams are increasingly evaluating blades through the lens of total operating cost rather than sticker price. This shift is reinforced by the reality that blade changes, re-tensioning, and unplanned downtime carry significant indirect costs in high-volume production settings.
Worldwide Welded Band Saw Blades Market
A further demand-side dynamic is the growing preference for suppliers that can offer application-specific guidance. Fabricators handling high-strength steels or composite-heavy workpieces often require blades with tailored tooth geometry and hardness profiles. When manufacturers provide technical support, selection assistance, and documented cut recommendations, they reduce the risk of suboptimal blade choice and create a relationship anchor that extends beyond transactional purchasing. This trend is especially relevant for mid-sized fabricators that lack in-house metallurgy expertise but still need consistent performance from their cutting equipment.
Supply Chain and Cost Structure Pressures
Cost structures in the band saw blades market are being redefined by raw material volatility and the economics of advanced alloy usage. High-carbon strip steel pricing remains sensitive to global supply conditions, and fluctuations in high-speed steel alloys continue to affect production costs for advanced blades. These pressures are prompting producers to revisit procurement timing, inventory buffering, and manufacturing yield. The companies that are managing cost effectively are not simply passing price changes through to customers; they are investing in process optimization, reducing scrap rates, and aligning blade design with material availability in ways that preserve margin without sacrificing performance.
Supply chain resilience is also becoming a competitive consideration. Procurement departments in metal fabrication and industrial machining are increasingly aware that blade availability, consistent batch quality, and predictable delivery schedules matter as much as the blade itself. Suppliers that can demonstrate stable lead times and transparent sourcing for critical inputs are gaining trust in environments where production continuity is a top priority. This dynamic is gradually shifting the basis of competition from purely technical specifications to a broader reliability equation that includes material security and service responsiveness.
Competitive Landscape and Leading Strategies
Differentiating Through Product Architecture and Application Focus
The competitive field is populated by a mix of established European and North American manufacturers, with a growing presence from specialized producers in Central and Eastern Europe and Asia. Several leading companies have built their positioning around distinct product architectures and application expertise. One European leader stands out for its scale, global sales network, and focus on precision metal-cutting blades, consistently showcasing solutions at major industry events and securing high-profile deployments in extreme-capacity sawing environments. Another prominent North American manufacturer emphasizes premium bi-metal construction and optimized tooth geometry across metal, wood, plastics, and composites, appealing to users who value versatility and documented performance. A third U.S.-based producer concentrates on heavy structural steel, super alloys, and high-production applications, pairing American-made manufacturing with carbide-tipped tools designed for demanding metallurgical conditions.
German and Swedish specialists further enrich the landscape by emphasizing carbide-tipped and bi-metal designs for industrial metal and construction materials, as well as trimetal and bi-metal blades for heavy-duty cutting with specialized series engineered for difficult materials. Czech and U.S. manufacturers round out the field with bimetallic and wood-cutting options, plus full-line industrial blades that cover both bi-metal and carbide-tipped variants. Chinese producers focusing on bi-metal blades for high-strength steel are also part of the equation, offering capacity and cost-oriented alternatives for specific industrial applications. Together, these participants illustrate a market where differentiation is achieved not through a single formula but through a combination of material strategy, tooth design, production location, and application storytelling.
Strategic Positioning and Evolving Market Structure
The strategic positioning of leading players reflects a clear split between scale-driven distribution and performance-driven specialization. Larger, globally networked manufacturers leverage broad catalogs, established service channels, and event-based visibility to maintain brand prominence and capture share across multiple industrial segments. Their advantage lies in reach, consistency, and the ability to serve multinational procurement requirements. Smaller or regionally anchored specialists, by contrast, often compete by deepening expertise in particular material classes, cutting conditions, or end-use scenarios. This can include precision-focused metal cutting, heavy structural steel, or niche wood and composite applications where tailored geometry and hardness profiles deliver measurable gains.
The market structure appears to be evolving along two parallel paths. Consolidation pressure remains real, given the concentration of revenue among the top participants and the compliance and scale advantages that favor established players. At the same time, there is room for differentiation and selective fragmentation when suppliers can prove that application-specific engineering reduces total cost of ownership. New entrants and regional producers are most likely to succeed when they bring a clear technical claim, a defensible cost position, or a service model that addresses a gap in the incumbent offering. Pure price competition in undifferentiated segments, however, is increasingly unsustainable as raw material volatility and compliance costs raise the floor for viable operations.
Recent activity reinforces these strategic patterns. Trade fair presentations and catalog updates in 2025 and early 2026 show that leading manufacturers are continuously refreshing their portfolios and using industry events to signal innovation and application breadth. The emphasis on carbide-tipped expansions, bi-metal optimization, and high-capacity deployments suggests that the competitive conversation is moving toward performance validation, material handling capability, and the ability to support demanding cutting environments.
Forward Outlook: Trends and Opportunities for the Next Three to Five Years
Based on current market dynamics and the trajectory of product development, three trends are likely to shape the band saw blades market through the latter half of the decade.
-
Application-specific blade engineering will become a mainstream purchasing criterion. As fabricators and machining operations place greater weight on total cost of ownership, blades that are optimized for particular material hardness, section size, or production rhythm will gain preference. The opportunity lies in pairing technical claims with field-validated performance data, selection guides, and application support that reduce the risk of suboptimal blade choice. Suppliers that institutionalize this capability will be better positioned to command value in segments where cutting efficiency and blade life directly affect throughput.
-
Material security and cost management will separate durable performers from reactive price-takers. Continued volatility in high-carbon strip steel and high-speed steel alloys will keep cost structures under pressure. Companies that strengthen forward sourcing, improve yield, and align product design with material availability will be more resilient. The commercial opportunity is to convert this resilience into reliable delivery and consistent quality, which are increasingly valued by procurement teams focused on production continuity.
-
Compliance and quality documentation will function as both a barrier and a differentiator. Standards related to inspection, tension testing, ISO 9001, and CE conformity are likely to remain salient, especially in regulated industrial environments. Suppliers that embed quality systems into production and can provide clear evidence of batch consistency and safety conformity will find it easier to win vendor approvals and expand into markets where documentation is a prerequisite. The risk is that companies with weaker documentation infrastructure will face slower access to certain procurement channels, even if their base product performance is adequate.
These trends point to a market where opportunity is concentrated in performance validation, material resilience, and application service. At the same time, uncertainty remains in the pace of raw material price swings, the potential for further regulatory tightening, and the risk that overcapacity in commoditized segments could pressure margins if differentiation fails to keep pace. Participants should therefore monitor not only product innovation but also supply chain strategy and compliance readiness as interconnected drivers of long-term competitiveness.
Strategic Actions for Decision-Makers
For manufacturers and brand leaders, the priority is to convert technical differentiation into measurable customer value. This means investing in application-specific blade designs, documenting performance under realistic cutting conditions, and aligning sourcing and manufacturing processes to absorb raw material volatility without compromising quality. Companies that can demonstrate extended blade life, consistent cut quality, and reliable delivery in demanding metal, wood, and food-related applications will strengthen their position against both established rivals and cost-oriented entrants. It is equally important to treat compliance infrastructure as a strategic asset, using quality certification and safety documentation to widen access to regulated procurement channels.
For investors evaluating the sector, the analytical focus should center on companies that combine defensible product architecture with supply chain discipline and a clear application narrative. Scale and distribution matter, but the more durable advantages are likely to accrue to players that can maintain margin through material cost cycles, prove performance in high-production environments, and serve procurement teams that prioritize total operating cost over unit price. Portfolio exposure should also account for the balance between consolidated leaders and specialized contributors, since the market is being shaped by both concentration dynamics and pockets of application-driven differentiation.
For procurement and operations leaders, the most effective approach is to evaluate band saw blades through a broader cost-and-risk lens. Specification decisions should consider blade life, changeover frequency, tension and inspection requirements, and the availability of technical support for material-specific selection. Where cutting operations handle high-strength steels, super alloys, or variable wood and composite conditions, partnering with suppliers that provide application guidance and consistent batch quality can reduce downtime risk and improve predictability. It is also prudent to build sourcing strategies that account for raw material volatility and compliance documentation, ensuring that supplier selection reflects both performance and operational resilience.
For stakeholders seeking a deeper, segment-level view of market size, regional dynamics, product splits, and company-specific positioning, the full research report provides a more granular foundation for planning. Detailed breakdowns of type, application, and regional revenue, along with expanded competitive profiles and recent development timelines, can support more precise segmentation, pricing strategy, and outlook modeling. In a market where advantage increasingly depends on product specificity, material resilience, and compliance readiness, access to structured, granular intelligence can sharpen decision-making and reduce the risk of acting on incomplete signals.
For detailed analysis of this topic, please visit the official page: Band Saw Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


