



Chitosan Market Insights: Decoding the 19.76% CAGR and Asia Pacific Power Shift

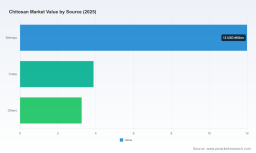
The Chitosan Market at an Inflection Point: Strategic Trends and Commercial Opportunities (2026–2032)
The chitosan market has transitioned from a niche biopolymer segment into a strategically significant arena for industrial, agricultural, and life sciences applications. Measured in millions of USD, the global market expanded from 7.77 in 2020 to 19.15 in 2025, and the trajectory points toward 67.66 by 2032, reflecting a compound annual growth rate of 19.76 percent across the forecast horizon. This scale of acceleration is atypical for mature chemical segments and signals a convergence of regulatory tailwinds, application diversification, and supply-side restructuring. For executives and investors evaluating biomaterial portfolios, chitosan now represents a cross-disciplinary platform rather than a single-product category, with value creation increasingly tied to grade specificity, regulatory positioning, and source diversification.
Market Snapshot and Structural Realities
The historical progression from 2020 through 2025 shows consistent expansion, with each year building on prior demand adoption and capacity additions. The forward curve from 2026 to 2032 compounds at nearly twenty percent annually, implying that incremental growth will be driven less by baseline industrial consumption and more by new application penetration, regulatory clarity, and substitution dynamics in water treatment, cosmetics, pharmaceutical and biomedical use, food and beverages, and emerging agricultural formulations. At the same time, the market structure remains moderately concentrated, with the top three firms capturing approximately 42 percent of revenue and the top five approaching 48 percent. This concentration level indicates that scale players hold meaningful advantages in purity consistency, regulatory documentation, and cost discipline, yet enough fragmentation persists to allow specialized entrants to compete on molecular weight, source origin, or application-specific formulation.
The industry sits at a genuine inflection point. First, the regulatory conversation around chitosan classification is accelerating in key geographies, particularly in organic agriculture and crop protection. Recent technical reviews and subcommittee proposals have opened a pathway to classify chitosan as nonsynthetic under organic crop production rules, with votes and final determinations expected in the near term. This matters because regulatory status directly shapes allowable use cases, labeling claims, and market access for agricultural and processing applications. Second, raw material dependence on crustacean exoskeletons continues to tie chitosan supply chains to seafood processing volumes, aquaculture dynamics, and regional byproduct availability. That linkage introduces volatility in feedstock consistency, contamination risk, and cost structure, especially when capture fisheries or shellfish processing cycles shift. Third, the segment is witnessing a source diversification push, with insect-derived chitin and chitosan production expanding through black soldier fly feedstock processes. This alternative pathway is still developing, but it is already influencing strategic planning among producers seeking to reduce marine dependency and broaden customer eligibility in markets sensitive to shellfish allergen concerns or sustainability criteria.
Core Drivers Reshaping the Market
Several forces are interacting to sustain the current growth path and reshape competitive priorities.
Technological innovation and grade specialization are moving from general-purpose chitosan to application-tailored molecular architectures. High-purity pharmaceutical, food, and agricultural grades now require distinct deacetylation levels, molecular weight ranges, and contamination controls. In parallel, inhaled drug delivery represents a notable frontier, with first commercially available chitosan formulations for inhalation entering the market and opening doors for pulmonary and respiratory applications. Clean-label and sustainable chitosan ranges are also being introduced, reflecting demand from cosmetics, food, and biomedical customers who prioritize traceability, bio-based sourcing, and reduced processing footprints. For manufacturers, differentiation is increasingly defined by the ability to deliver reproducible specifications at scale, not merely by producing chitosan as a commodity.
Worldwide Chitosan Glycolate Market
Policy and regulatory environment is shaping adoption speeds and permissible use cases. In the European Union, chitosan and chitosan hydrochloride remain approved as basic substances for plant protection, with ongoing review and potential renewal under current implementing regulations and recent scientific statements. In the United States, there has been a series of petitions to the organic standards body for uses spanning wine processing aids and pesticide applications, culminating in technical reports and subcommittee proposals under active review. These developments matter for commercial planning because they influence whether chitosan can be positioned as a nonsynthetic input in organic systems, how quickly new agricultural products can reach market, and what documentation burden suppliers must carry to serve regulated end markets. Companies that invest early in regulatory-grade documentation and application testing are better positioned to capture premium segments once approvals or clarifications land.
Demand-side behavior is shifting among both enterprises and end consumers. In agriculture, regenerative farming practices are encouraging adoption of chitosan-based seed treatments and bio-stimulants that support crop defense and nutrient efficiency, particularly where growers seek reduced reliance on synthetic inputs. In cosmetics and personal care, demand continues to favor biopolymers with perceived sustainability and skin compatibility benefits. In pharmaceutical and biomedical contexts, interest is growing around wound care, drug delivery, and functionalized derivatives that can be engineered for specific biological interactions. Across these channels, purchasing decisions are increasingly influenced by specification reliability, source transparency, and application performance, which rewards suppliers with strong technical service capabilities and validated use-case data.
Supply chain and cost structure dynamics remain central to margin outcomes. Because chitosan is predominantly extracted from marine shellfish exoskeletons as a byproduct of the global seafood processing industry, supply availability is influenced by crustacean aquaculture and capture fisheries volumes. This structure creates a strategic tension: producers benefit from byproduct economics, but they also inherit variability in feedstock quality, regional processing capacity, and season-dependent supply. As a result, cost competitiveness increasingly depends on upstream integration, purification efficiency, and the ability to secure consistent raw material streams. The emerging insect-derived route offers an alternative supply logic that may reduce dependence on marine channels over time, though commercial scale, cost parity, and customer acceptance are still being validated.
Competitive Landscape and Strategic Positioning
The competitive set spans industrial-scale marine-sourced producers, specialized pharmaceutical and biomedical formulators, regional agricultural solution providers, and emerging alternative-source innovators. Leadership patterns suggest three strategic archetypes.
Scale producers with grade breadth have built advantage through high-purity output across pharmaceutical, food, and agricultural grades, supported by industrial-scale processing and established export channels. Firms in this group typically compete on consistency, documentation, and breadth of grade offerings, allowing them to serve multiple application verticals from a shared processing base. Their strategic edge lies in converting byproduct availability into a broad commercial portfolio while maintaining quality systems that meet regulated end markets.
Specialists in purity and application focus concentrate on cosmetic, pharmaceutical, and medical uses with customized formulations. These players often differentiate through tight control of molecular properties, tailored product development, and close engagement with downstream formulators. Their value proposition is less about volume dominance and more about specification precision, technical support, and regulatory readiness for sensitive applications. In a market where performance requirements differ sharply by end use, this focused model can command higher value capture per unit of output.
Application-oriented and regionally anchored players are expanding the commercial frontier through targeted product launches and distribution partnerships. In agriculture, chitosan-based seed treatments and bio-stimulants have been introduced for regenerative farming, supported by regional rollouts that address specific crop systems and farming practices. In parallel, some producers are pursuing distribution partnerships to broaden availability in emerging markets, where access and channel development can be as important as product performance. These moves reflect a market in which application value, local support, and supply reach increasingly determine competitive success.
The landscape is evolving along both consolidation and fragmentation axes. Consolidation pressure exists where scale, regulatory documentation, and cost discipline create advantages for larger processors, especially in marine-sourced commodity grades. At the same time, fragmentation persists in specialized biomedical grades, alternative-source production, and application-specific agricultural formulations, where capital intensity is lower but technical expertise and market access are decisive. New entrants are most likely to succeed by targeting unmet specification needs, sustainable source narratives, or regulated use cases that require dedicated development and compliance support. Recent product introductions in inhaled delivery, clean-label ranges, and agricultural bio-stimulants illustrate how targeted launches can open distinct commercial lanes without requiring dominance across the entire market.
Strategic Outlook for 2026–2032
Looking ahead, several trends are likely to shape value creation opportunities over the next three to five years.
Regulatory clarity will unlock application expansion. As organic classification discussions and plant protection reviews progress, the market is likely to see clearer boundaries for chitosan use in crop production and processing. If classification moves in favor of nonsynthetic status in key jurisdictions, agricultural and organic-market demand could accelerate, and suppliers with compliant documentation and application data will be first in line to capture that expansion. The main uncertainty is timing and final scope, since regulatory outcomes can vary by region and by specific use category.
Source diversification will move from option to strategic necessity. Traditional marine dependency will continue to create feedstock volatility, while insect-derived and other alternative pathways will gain traction where sustainability claims, allergen considerations, or supply resilience are priorities. Over the forecast period, the strategic question is not whether alternative sources will grow, but which applications will adopt them first and at what cost premium. Producers that can offer both marine and non-marine options, or that can secure reliable alternative feedstock streams, will have stronger negotiating positions with customers seeking supply continuity.
High-value applications will increasingly define the growth mix. Water treatment, cosmetics, pharmaceutical and biomedical use, food and beverages, and agriculture each bring different specification requirements and margin profiles. In the coming years, the fastest value accumulation is likely to occur where chitosan is positioned as an engineered input rather than a bulk additive, particularly in biomedical delivery systems, targeted agricultural formulations, and specialty cosmetic ingredients. This shift will reward companies with strong R&D, application testing, and customer co-development capabilities, while pressuring generic producers to compete primarily on cost and availability.
Potential risks and uncertainties should be factored into planning. Feedstock variability can disrupt purity consistency and cost assumptions, especially when seafood processing cycles change. Regulatory processes can move slower than anticipated, or result in narrower approvals than hoped, affecting near-term commercialization plans. Alternative-source technologies may face scaling challenges, cost gaps, or customer acceptance hurdles before reaching meaningful share. Finally, as concentration remains moderate, price competition in commodity-grade segments can compress margins if differentiation is weak.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align grade strategy with application economics. Investing in reproducible specification control, regulatory documentation, and application-specific technical service will create more durable positioning than competing solely on volume. Where possible, building flexibility across source options and purification pathways can reduce exposure to marine feedstock variability and open new customer segments.
For investors, the most attractive exposure is likely to come from companies with clear application anchors, defensible purity or formulation capabilities, and credible routes to regulated markets. Due diligence should focus on feedstock resilience, specification consistency, regulatory readiness, and the credibility of application claims in high-value segments such as biomedical delivery, regenerative agriculture, and specialty cosmetics. It is equally important to assess whether growth expectations rely on generic volume expansion or on differentiated use cases with stronger pricing power.
Worldwide Chitosan for Water and Waste Treatment Market
For procurement and sourcing leaders, specification transparency and supply reliability should be weighted alongside price. Given raw material linkages and the increasing importance of grade specificity, multi-source strategies and supplier qualification based on documented purity, contamination controls, and application support can reduce risk. Where organic certification, allergen sensitivity, or sustainability claims matter for downstream markets, sourcing decisions should account for source origin, processing method, and compliance documentation rather than treating chitosan as a uniform input.
PW Consulting
As the market moves through this phase of regulatory evolution, source diversification, and application specialization, the ability to act on detailed segment-level intelligence becomes a competitive advantage. For teams that need deeper segmentation data, regional dynamics, and customized strategic scenarios, the full research report provides additional detail to support planning and execution.
For detailed analysis of this topic, please visit the official page: Chitosan Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


