



FOS Market: Why 8.25% CAGR and Food & Beverage Demand Redefine Growth

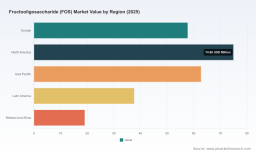
The Fructooligosaccharide (FOS) Market at a Strategic Inflection Point: Growth Dynamics and Commercial Pathways
The global market for fructooligosaccharides (FOS) has moved beyond experimental nutrition into a phase of structural expansion, where demand signals across food, infant nutrition, dietary supplements, and animal feed increasingly intersect with regulatory clarity and formulation innovation. Valued at approximately USD 252.0 million in 2025, the market has traced a discernible upward trajectory since 2020, when it stood near USD 195.0 million. After modest consolidation in 2022, revenue climbed to USD 207.88 million, then accelerated through 2023–2024 before reaching the current baseline. The forward path reflects a projected compound annual growth rate of 8.25 percent across the 2026–2032 horizon, with revenue expected to move from roughly USD 265.1 million in 2026 toward USD 440.0 million by 2032. This trajectory suggests more than incremental growth; it points to a maturing prebiotic category where FOS is being embedded into mainstream ingredient portfolios rather than treated as a niche additive.
Such scaling does not occur in a vacuum. The market has reached a point where volume expansion, application diversification, and regulatory acceptance are beginning to reinforce one another, yet the same forces also expose bottlenecks in supply, formulation, and competitive positioning. For executives evaluating ingredient strategy, this environment rewards those who can align product readiness with consumer expectations, regulatory pathways, and cost structures that remain under pressure in key raw material chains.
Market Context: A Growing Category With Structural Complexity
The scale and pace of FOS adoption are visible in the way the category now spans multiple end-use environments. Rather than relying on a single growth engine, the market is being carried by simultaneous expansion across food and beverages, infant formula, dietary supplements, pharmaceuticals, and animal feed. Each application brings a different set of performance expectations, regulatory thresholds, and procurement cycles. Food and beverage applications tend to prioritize taste modulation, sugar reduction, and digestive health positioning, while infant nutrition demands rigorous safety documentation and tolerance data. Dietary supplements often depend on functional claims and premium positioning, and animal feed applications are shaped by cost sensitivity and gut-health outcomes. This breadth creates resilient demand, but it also requires suppliers to manage distinct validation requirements and formulation constraints.
At the same time, the market is not operating as a loosely organized field of interchangeable producers. Concentration metrics indicate a moderately consolidated landscape, with three leading firms accounting for a meaningful share of activity and a broader top five reinforcing the structure. This level of concentration signals that scale, technical service capability, and regulatory documentation increasingly matter. New entrants and smaller producers can still find openings in specialized niches or regional channels, but broad-based competition often favors organizations that can combine consistent supply, application support, and a credible safety narrative.
Core Challenges and Inflection Points
Despite the favorable growth profile, several challenges are shaping the near-term trajectory of the FOS market. The first is the tension between demand diversification and raw material constraints. Many FOS streams depend on chicory root or sucrose-based enzymatic conversion, and both pathways face volatility related to crop cycles, sourcing geography, and processing economics. Seasonal fluctuations in chicory root supply continue to challenge scaling, particularly where inulin-derived routes form a major part of production. This creates a structural cost risk that can disrupt margins and complicate long-term capacity planning.
The second challenge lies in regulatory and tolerance validation. As FOS moves into infant formula and broader functional food categories, manufacturers must navigate established concentration limits and evolving safety documentation expectations. For example, FOS maintains GRAS status for infant formula at specific usage levels, and additional safety and gastrointestinal tolerance data are being reviewed as new uses are proposed. The presence of multiple regulatory references across jurisdictions means that formulation teams and commercial leaders cannot rely on a single global playbook. A product well positioned in one region may require different documentation, labeling rationale, or usage thresholds in another.
The third inflection point is competitive differentiation in a category where functional benefits are increasingly expected rather than exceptional. As sugar reduction and gut-health positioning become mainstream, FOS is no longer competing only on prebiotic credentials but also on sensory performance, formulation compatibility, and metabolic health narratives. That shift raises the bar for suppliers. The winners will be those who can deliver reliable functionality while supporting customers with clinical or tolerability evidence, application testing, and clear claims guidance.
Core Drivers Reshaping the FOS Landscape
Several forces are pushing the market beyond baseline growth. The first is technology and formulation innovation. Producers are refining enzymatic processes and product grades to balance prebiotic efficacy, solubility, and organoleptic neutrality. The ability to offer short-chain and other FOS variants tailored to specific applications has become a commercial advantage, especially where formulators need solutions that reduce sugar without compromising texture or mouthfeel. This is visible in recent product activity across major suppliers, where companies have expanded FOS offerings to support sugar reduction, functional foods, and infant nutrition. Capacity investments and new functional ingredient line extensions suggest that suppliers are treating FOS not as a commodity line but as a platform for flexible, application-specific solutions.
The second driver is a regulatory environment that is providing both stability and new openings. In several markets, FOS already enjoys a defined regulatory footing for specific uses, which reduces uncertainty for large-scale adoption. In the United States, GRAS notices continue to support expansion into infant products and conventional food and beverage categories, with safety data under review up to early 2025. In the European Union, FOS has long been permitted in restricted amounts in baby formula and follow-on formula, creating a durable pathway for infant nutrition applications. In Canada, FOS is recognized within natural health product frameworks. These approvals do not guarantee automatic growth, but they lower the regulatory friction that often slows ingredient adoption in sensitive categories.
The third driver is a shift in demand-side behavior. Consumers and brand managers are increasingly treating digestive health and sugar reduction as interrelated priorities rather than separate goals. FOS fits naturally into that convergence, which helps explain its growing presence in functional snacks, beverages, and supplement formats. A notable example is the launch of a functional chocolate line in Japan that used FOS to replace added sugar, offering products with substantially less or no added sugar while emphasizing gut health and calorie reduction. This kind of hybrid value proposition illustrates how FOS can be used as a dual-purpose ingredient: supporting metabolic and digestive positioning while helping formulators meet taste and reformulation targets.
A fourth driver is emerging clinical and metabolic research that broadens the narrative beyond traditional gut-health claims. Certain FOS variants have been associated with stimulation of GLP-1 hormone levels in clinical research, opening interest in metabolic health and weight management applications. While such findings do not automatically translate into commercial claims, they create strategic optionality. If subsequent data and regulatory interpretations continue to support metabolic benefits, the FOS category could gain new relevance in lifestyle nutrition and functional health segments that are currently underserved by conventional prebiotic messaging alone.
Supply-side economics also remain influential. The cost and availability of key raw materials continue to shape competitive dynamics. Where inulin-derived routes dominate, seasonal and supply chain volatility creates challenges for consistent scaling. This reinforces the value of diversified sourcing strategies, flexible production routes, and supplier relationships with demonstrated supply reliability. For procurement and strategy teams, this is a reminder that FOS purchasing decisions cannot be reduced to unit price alone; they must also account for continuity, grade consistency, and the ability to support downstream formulation requirements.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive environment reflects a group of established ingredient suppliers with distinct regional strengths, formulation capabilities, and application focus areas. Beneo GmbH operates across Europe with FOS grades such as Beneo-scL85 designed for sugar reduction, functional foods, and infant nutrition, and has been strengthening its position through product modernization and investments that support expanding production capacity. Meiji Holdings brings a strong brand and formulation heritage through products such as Actilight and Meioligo, with applications spanning functional foods, supplements, and prebiotic uses worldwide. Cargill and Ingredion contribute broad ingredient portfolios and formulation support, targeting infant formula, dietary supplements, functional beverages, and nutraceutical applications, often with GRAS-supported or multiple-grade offerings that simplify customer adoption. Tate & Lyle remains focused on enzymatic short-chain FOS with production arrangements aligned to infant products, conventional foods, and beverages.
The competitive picture is not limited to large multinational incumbents. Galam Group produces short-chain FOS and inulin-derived variants for prebiotic and sugar-reduction applications, and has highlighted clinical research related to GLP-1 stimulation that may support future metabolic-health positioning. Cosucra produces chicory-derived FOS and inulin for food, infant nutrition, and functional ingredients, reinforcing the importance of European sourcing and application depth. Roquette Frères supplies FOS and resistant starch blends for infant formula and dietary supplements, suggesting an increasing appetite for combination ingredient systems. Quantum Hi-Tech reflects a more Asia-focused production footprint, serving food, feed, and supplement channels and illustrating how regional supply can become strategically important where local demand and sourcing preferences are strong.
Worldwide Short Chain Fructooligosaccharides Market
Several strategic patterns emerge from this landscape. First, differentiation is increasingly built on more than supply availability. Leading players are distinguishing themselves through grade variety, application support, regulatory documentation, and the ability to match specific use cases such as infant formula tolerance requirements or sugar-reduction targets in consumer foods. Second, the category is showing signs of both consolidation and fragmentation. In core ingredient distribution and major applications, scale and technical service favor larger players. In specialized formats, regional markets, or particular value propositions, smaller or regional suppliers can maintain relevance by serving niches that larger portfolios do not address with the same focus. Third, the market is likely to see continued evolutionary pressure from new product launches, regulatory filings, and capacity expansions that reshape competitive priorities over time.
Recent developments underscore how companies are using regulatory actions and product innovation to reinforce positioning. A GRAS notice filed for short-chain FOS for use in infant products and conventional food and beverage categories reflects ongoing efforts to support broader application scope through documented safety review. At the same time, product launches emphasizing reduced sugar, gut health, and functional benefits show how FOS is being integrated into consumer-facing narratives rather than remaining solely an industrial ingredient. Clinical research on metabolic endpoints further illustrates how suppliers and product developers are exploring adjacent opportunities beyond conventional prebiotic positioning.
Future Trends and Commercial Implications
Looking ahead across the next three to five years, a few trends appear especially consequential. The first is deeper integration of FOS into mainstream reformulation strategies, particularly where sugar reduction and digestive-health claims must coexist in the same product. As consumers become more accustomed to functional ingredients in everyday foods and beverages, FOS may be selected less as a specialty additive and more as a standard tool in formulation toolkits. For suppliers and brand owners, this implies greater demand for grades that perform reliably across varied matrices and for documentation that supports both technical adoption and claim substantiation.
The second trend is the widening of application narratives to include metabolic health and weight-management contexts, supported by emerging clinical signals. If GLP-1-related interest continues to gain traction in scientific and commercial discussions, FOS could find new relevance in products targeting satiety, glycemic support, or broader metabolic wellness. This does not eliminate the importance of gut-health positioning, but it suggests that FOS may be positioned in more layered benefit narratives. The commercial implication is that companies should prepare for potentially more complex claim pathways and validation requirements, while also recognizing the upside if regulatory and scientific consensus expands.
The third trend is a continued push toward supply resilience and cost control as the category scales. With raw material seasonality and production economics remaining constraints, the market may reward suppliers that can demonstrate stable output, flexible grade options, and transparent supply planning. Buyers may increasingly weigh continuity and technical reliability alongside price. This creates an opportunity for organizations that invest in supply chain robustness and multi-source strategies, especially if demand accelerates in applications where interruptions are costly or difficult to manage.
PW Consulting
These trends carry uncertainty. Regulatory review processes can slow expansion into sensitive applications, and new clinical narratives may take time to mature into accepted positioning. Raw material volatility can pressure margins and complicate capacity deployment. In addition, competitive intensity could compress differentiation if sugar-reduction and prebiotic benefits become broadly available across ingredient options. Organizations that monitor these variables carefully will be better positioned to adapt their portfolios, claims, and sourcing strategies as conditions evolve.
Galactooligosaccharides (GOS) Market
Strategic Actions for Decision-Makers
The current market environment suggests several practical priorities for different stakeholder groups.
-
For ingredient manufacturers and suppliers, the priority is to align product roadmaps with the converging demands of sugar reduction, digestive health, and emerging metabolic-interest applications. That means investing not only in production capacity but also in the documentation, application testing, and regulatory readiness that help customers adopt FOS with confidence. Differentiation will increasingly depend on whether a supplier can support formulation performance across multiple food and supplement matrices while maintaining credible safety narratives for sensitive uses.
-
For investors and corporate strategy teams, the market signals a category where demand breadth and moderate consolidation create opportunities, but also where cost volatility and regulatory specificity can shape returns. Due diligence should consider application mix, regional exposure, raw material dependency, and the strength of technical service capability in addition to headline growth. In particular, portfolios with diversified end-use use cases may be more resilient than those concentrated in a single channel exposed to seasonal or regulatory shocks.
-
For procurement and brand owners, the strategic task is to treat FOS selection as a multi-factor decision. Beyond unit cost, buyers should evaluate grade suitability for the intended application, tolerance and safety documentation for regulated uses, supply continuity, and the supplier’s ability to support future reformulation or claim strategies. In sugar-reduction programs especially, the interaction between taste, texture, and prebiotic function can determine whether FOS becomes a viable long-term ingredient or a limited trial.
Given the pace of regulatory filings, clinical exploration, and application innovation, detailed segment-level intelligence can materially improve timing and resource allocation. A fuller view of regional demand patterns, application-level pricing and volume dynamics, competitive positioning by grade, and supply chain sensitivities can help decision-makers move from broad market optimism to implementation choices with clearer risk controls. For executives and investors seeking to act on FOS opportunities, that level of granularity is often the difference between a plausible opportunity and a plan that can be executed with confidence.
For detailed analysis of this topic, please visit the official page: Fructooligosaccharide (FOS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


