



Electric Scooters Market: How 9.8% CAGR and Asia Pacific Growth Redefine Strategy

The Electric Scooters Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The electric scooters market has transitioned from a niche alternative to a structurally embedded component of urban mobility ecosystems. Revenue across the sector expanded from USD 24.32 billion in 2020 to USD 38.23 billion in 2025, with a projected trajectory toward USD 73.5 billion by 2032. This represents a compound annual growth rate of 9.81 percent, signaling consistent momentum rather than cyclical spikes. The growth profile reflects a market that has passed early experimentation and entered a phase where scale, reliability, and regulatory alignment determine commercial viability.
Several developments illustrate this maturation. At CES 2026, Segway-Ninebot and Apollo Scooters each introduced updated e-scooter lineups centered on extended-range battery architectures and enhanced smart connectivity. TVS Motor Company followed in March 2026 with the TVS X 2026 model in India, adding an ABS option and refined powertrain tuning for mainstream commuting. Meanwhile, Navee updated its GT3 Pro and ST3 Pro catalogs in April 2026 with new 48V battery packs and verified 30 to 40 mile range specifications. These releases share a common direction: manufacturers are shifting from feature novelty toward practical durability, standardized electrical systems, and measurable range performance.
Despite clear momentum, the market faces structural headwinds that will shape competitive outcomes over the next several years.
First, trade policy and tariff exposure are reshaping cost assumptions and sourcing strategies. U.S. Customs and Border Protection imposed a 100 percent tariff on electric scooters imported from China effective August 2024, with lithium-ion battery components for EVs subject to 25 percent duties starting in 2026. For companies that rely heavily on Chinese assembly or battery integration, this alters margin expectations and may accelerate regional production shifts, supplier diversification, or product redesigns aimed at tariff optimization.
Second, battery regulation and safety compliance are becoming more prescriptive. The PHMSA lithium battery guide updated in May 2024 extends watt-hour rating marking requirements for lithium-ion batteries over 100 Wh and sets quantity limits when batteries are packed with equipment, with a telephone number phaseout deadline of December 31, 2026. These requirements affect logistics, packaging, and product documentation, particularly for operators managing large fleets or cross-border distribution. Compliance is no longer a back-office task; it directly influences product design, shipment planning, and operational readiness.
Third, the market is navigating the tension between rapid deployment and long-term sustainability obligations. The EU Battery Regulation 2023 mandates a 70 percent battery material recovery rate through hydroelectrically compliant recycling for shared e-scooter fleets. This creates a forward-looking cost and operational consideration for commercial operators and manufacturers that supply fleet units. At the same time, China Customs reported lithium battery exports reached approximately 1.3 billion units in Q1 2026, a 30 percent year-on-year increase, with export value climbing to USD 23.95 billion. The scale of battery supply growth is real, but regulatory and environmental expectations are also intensifying, meaning availability alone does not guarantee compliant or cost-stable deployment.
Taken together, these challenges indicate that market leadership will increasingly depend on regulatory agility, supply chain flexibility, and product designs that can withstand both technical and policy scrutiny.
Key Drivers Shaping the Market
Technology Innovation and Range Performance
Battery and motor refinement remain the most visible drivers of adoption. Recent product cycles emphasize 48V architectures, hub motors with extended-range batteries, and integrated connectivity that supports diagnostics, usage tracking, and fleet management. The practical effect is not simply higher top speed, but improved everyday usability. Commuters and fleet operators increasingly evaluate scooters based on range consistency, charging convenience, and reliability across multiple cycles rather than peak power claims alone.
Electric Motorcycle and Scooter Market
This shift matters commercially because it changes the value proposition from novelty to utility. Products that deliver predictable range and lower maintenance burden are better positioned for personal commuting and commercial deployment alike. In parallel, the emergence of models with swappable batteries, telematics, and AI-optimized performance points toward a broader expectation: electric scooters are being treated as connected mobility assets rather than standalone consumer goods.
Policy and Regulatory Environment
Regulatory dynamics are now a core determinant of where and how electric scooters scale. The combination of import tariffs, battery transport rules, and recycling obligations creates a multi-layered compliance environment. For shared mobility operators, municipal permits, sidewalk and lane usage rules, and fleet caps can accelerate or constrain deployment more immediately than product availability. For manufacturers, differences in safety marking, battery handling rules, and regional certification requirements influence time-to-market and cost structure.
The policy environment also incentivizes certain product strategies. Where recycling and recovery requirements are strict, manufacturers and operators have stronger reasons to design for serviceability, battery replacement, and end-of-life material recovery. Where tariff exposure is high, there is added pressure to evaluate assembly locations, component sourcing, and localized inventory strategies. Policy is no longer a peripheral risk factor; it is becoming part of the product and operating model.
Demand-Side Shifts in Consumer and Enterprise Behavior
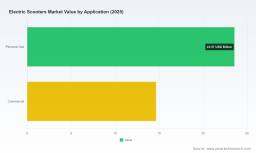
Demand is broadening on both the personal and commercial sides, but with different priorities. Personal users increasingly seek lightweight, foldable, or compact designs that fit multimodal commutes, last-mile connections, and limited storage environments. Commercial users, including fleet operators and urban mobility programs, prioritize durability, predictable operating costs, and integration with dispatch or connectivity platforms.
This divergence is important because it creates distinct product and service requirements. A scooter optimized for budget-conscious personal commuting does not automatically fit a shared fleet or municipal program. Conversely, ultra-light fleet units designed for micromobility programs may not meet the range or payload expectations of daily personal transport. The market is therefore moving toward more explicit segmentation in product design, service contracts, and deployment models.
Supply Chain and Cost Structure Evolution
Battery supply dynamics are a major force behind cost and capacity expectations. The Q1 2026 export data from China Customs underscores how central lithium battery availability has become to the broader electric mobility ecosystem. At the same time, the battery component duties scheduled for 2026 and the more prescriptive transport and marking rules indicate that cost advantages from battery sourcing are increasingly tied to compliance and logistics planning, not just unit pricing.
For manufacturers and operators, this means the cost equation is becoming more multidimensional. Raw material access, shipping rules, duty exposure, and recycling obligations all influence total cost of ownership. Companies that can align battery procurement, packaging, certification, and end-of-life planning are better positioned to maintain stable margins as the market scales.
Competitive Landscape and Leading Strategies
The market features a mix of established micromobility brands, regional manufacturers, and shared-mobility operators, each pursuing different strategic positions. The competitive frontier is not defined solely by volume; it is increasingly shaped by product architecture, connectivity, regulatory readiness, and deployment model specialization.
Among hardware-focused manufacturers, several patterns stand out. Segway-Ninebot continues to emphasize commuting and performance-oriented models with hub motors and extended-range batteries, and its recent CES 2026 introductions reflect a focus on updated battery technology and broader mobility integration. NIU International has built its position around lightweight scooters with integrated connectivity and long-range options, targeting urban mobility users who value smart features and portability. Yadea Technology Group extends the conversation beyond compact scooters into electric two-wheeler scooters and motorcycles with advanced battery and motor systems, broadening the addressable use case across personal and commercial applications.
In India, TVS Motor Company, Ather Energy, and Ola Electric illustrate a regional competitive dynamic centered on mainstream commuting, battery and motor refinement, and charging or swapping infrastructure. TVS’s Orbiter and Star Series e-scooters and the TVS X 2026 model emphasize 48V lithium-ion batteries and zero-emission daily commuting. Ather Energy’s Rizta and 450X models combine AI-optimized performance, swappable batteries, and telematics, aligning with last-mile and urban transport needs. Ola Electric’s S1 Pro and S1 X scooters focus on high-efficiency motors and fast-charging infrastructure for personal and fleet applications. Together, these players show how regional leaders can compete on a blend of product performance, ecosystem support, and localized deployment.
In the United States, a different competitive layer is forming around commuter reliability, performance variants, and budget-conscious options. Apollo Scooters’ Go and Go E2+ models emphasize solid tires and extended battery life for North American urban use, while its recent CES 2026 launches extend smart connectivity and improved 48V systems. Gotrax’s G4 Pro and G3 Plus models cater to buyers seeking 350W to 500W motors and foldable designs for lower-cost commuting. Navee, VMAX, InMotion, LexGo, and Kaabo address higher-performance or rugged-use segments with varied combinations of 48V systems, hub motors, dual-motor options, extended-range batteries, and off-road or long-distance capability. This diversification suggests that U.S. demand is not monolithic; it spans practical commuting, performance-oriented transport, and specialized terrain use cases.
Shared mobility operators add another dimension to the competitive landscape. Lime, Bird, Spin, and Veo focus on dockless fleet units, ultra-light program scooters, and custom fleet solutions for urban transportation authorities. Gogoro differentiates through a battery-swapping ecosystem designed for high-volume urban mobility. Their competitive advantage often lies less in vehicle novelty than in operational scale, city partnerships, compliance management, and fleet reliability.
The market is evolving along two complementary paths. One is consolidation and ecosystem building, where leading hardware manufacturers and platform operators strengthen connectivity, service networks, and battery or charging infrastructure. The other is fragmentation by use case, where brands specialize in personal commuting, commercial fleet deployment, performance riding, or municipal programs. New entrants can still gain traction by targeting a specific segment with clear performance, price, or compliance advantages, but they face a higher bar in a market where regulatory exposure, battery logistics, and brand trust increasingly influence purchasing decisions.
Future Trends and Strategic Opportunities
Trend 1: Product Design Will Align More Closely With Compliance and Lifecycle Management
As battery marking, transport, recycling, and tariff rules become more specific, electric scooters will be designed with compliance and serviceability in mind from the outset. This includes battery architectures that simplify replacement, documentation that supports transport requirements, and product strategies that accommodate material recovery expectations. For commercial operators, this trend creates opportunities in lifecycle management services, battery handling partnerships, and fleet designs that lower compliance friction over time.
The strategic implication is that compliance is becoming a competitive parameter. Companies that treat regulatory requirements as integral to product planning can reduce delays, avoid redesign costs, and position themselves more favorably in regulated markets.
Trend 2: Connectivity and Fleet-Ready Features Will Become Standard Rather Than Premium
The repeated emphasis on telematics, smart connectivity, battery diagnostics, and integrated mobility platforms indicates that data-enabled operation is moving toward the mainstream. This benefits shared fleets directly, but it also supports personal-use models by improving maintenance forecasting, range reliability, and user experience. Over the next few years, connectivity is likely to be less of a differentiator and more of a baseline expectation, particularly in commercial and municipal deployments.
Opportunities here include software-enabled services, predictive maintenance, fleet optimization, and integration with broader urban mobility platforms. For manufacturers, the challenge is to build these capabilities without overcomplicating the product or eroding cost competitiveness.
PW Consulting Automotive & Machinery Research Center
Trend 3: Regional Sourcing and Tariff-Aware Product Strategy Will Gain Importance
Tariff changes and battery component duties are likely to encourage more diversified sourcing, regional assembly considerations, and product planning that accounts for duty exposure. This does not necessarily mean a full exit from existing supply chains, but it does suggest greater scrutiny of where value is created and how exposure is managed. Companies that can balance cost efficiency with tariff and logistics resilience will be better positioned to maintain stable pricing and supply continuity.
At the same time, the strong growth in lithium battery exports highlights that supply availability is expanding, even as policy complexity increases. The opportunity lies in aligning procurement, certification, and distribution strategies so that scale benefits are not offset by compliance or duty-related costs.
These trends carry uncertainty. Regulatory timelines can shift, municipal deployment rules can change quickly, and battery supply conditions may vary by region and product category. Still, the direction is clear: the market is moving toward more standardized, compliance-aware, and connected products, with regional strategy playing a larger role in cost and scale planning.
Actionable Guidance for Decision-Makers
For Manufacturers
Design for compliance and serviceability early. Battery marking, transport rules, and recycling expectations are no longer late-stage considerations; they influence packaging, documentation, product architecture, and market access. Building these requirements into the product roadmap can reduce rework and accelerate rollout in regulated markets.
Clarify segmentation strategy. Personal commuting, commercial fleet use, and performance or rugged applications require different engineering priorities, pricing logic, and service models. A clearer segmentation posture helps avoid product overlap and supports stronger positioning in each segment.
Hoverboard Scooters Market
Plan for tariff-aware sourcing and regional flexibility. Evaluate how import duties and battery component obligations affect total cost and supply continuity. Where feasible, diversify sourcing, anticipate documentation needs, and model product strategies that can adapt if trade conditions change.
For Investors
Prioritize companies with clear regulatory readiness and lifecycle planning. In a market where compliance affects logistics, certification, and end-of-life handling, operational discipline can be as important as product features. Look for evidence that battery management, documentation, and recycling or recovery considerations are integrated into the business model.
Distinguish between hardware growth and ecosystem value. Shared mobility operators, battery-swapping providers, and connectivity-focused manufacturers may create value through service scale and deployment partnerships rather than unit volume alone. Investment theses should account for the specific path to profitability in each model.
Monitor regional divergence. Different markets are developing distinct demand profiles, policy environments, and sourcing constraints. Opportunity magnitude and risk vary significantly by region, so broad generalizations can obscure more useful segmentation-level insights.
For Procurement and Fleet Operators
Evaluate total cost of ownership with compliance and maintenance in mind. Purchase decisions should reflect not only sticker price and range claims, but also battery handling requirements, serviceability, documentation burden, and expected recovery or replacement pathways. Fleets that account for these factors early tend to face fewer operational disruptions later.
Match vehicle specifications to deployment reality. Ultra-light fleet units, commuter scooters, and performance-oriented models serve different use cases. Selecting the right specification for the route, user profile, and service model reduces wear, improves utilization, and supports more predictable operating costs.
Build supplier expectations around connectivity and support. Telematics, diagnostics, and service responsiveness can materially affect fleet reliability. Procurement criteria should weigh operational support and data capabilities alongside hardware specifications.
Conclusion
The electric scooters market is entering a phase where growth is increasingly tied to product reliability, regulatory alignment, and operational maturity. Revenue expansion from 2020 through 2025 and the projected trajectory toward 2032 point to sustained demand, but the most valuable opportunities will go to organizations that can navigate battery compliance, tariff exposure, and segmentation-driven product strategy while delivering practical range and connectivity benefits.
For decision-makers seeking deeper segmentation data, regional breakdowns, and customized strategic recommendations, the full PW Consulting research report provides a more detailed view of the market structure and forward scenarios.
For detailed analysis of this topic, please visit the official page: Electric Scooters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


