



Etch Equipment Market Analysis: Why 7.6% CAGR and Asia Pacific Dominance Redefine the 2026 to 2032 Outlook

Strategic Trends and Commercial Opportunities in the Semiconductor Etch Equipment Market
The semiconductor etch equipment market has entered a period of accelerated expansion, driven by the relentless demand for advanced logic and memory devices alongside increasingly intricate fabrication requirements. From 2020 through 2025, the global market has demonstrated consistent upward momentum, with revenue reaching an estimated 25.13 billion USD in the base year of 2025. Projections for the forecast period spanning 2026 to 2032 indicate a compound annual growth rate of 7.61 percent, positioning the market to exceed 41 billion USD by 2032. This trajectory reflects more than cyclical recovery; it signals a structural shift in how etching technologies are deployed across advanced packaging, high-bandwidth memory, and next-generation logic node development.
A critical examination of the market landscape reveals an industry at an inflection point. Three core challenges define the current environment. First, the technical demands of atomic-scale precision have outpaced conventional equipment capabilities, forcing manufacturers to rethink plasma control, chamber architectures, and process integration strategies. Second, the concentration of market power among a small group of dominant players leaves limited room for undifferentiated competition, compelling mid-tier and emerging suppliers to identify highly specialized niches or form strategic alliances. Third, geopolitical and regulatory dynamics have introduced profound uncertainty around cross-border equipment flows, particularly for advanced etch tools that intersect with sensitive manufacturing capabilities. Navigating these challenges successfully requires more than operational efficiency; it demands strategic foresight and precise market positioning.
PW Consulting Automotive & Machinery Research Center
Technology Drivers and Innovation Trajectories
The primary engine of market growth lies in the continuous push toward tighter feature sizes, three-dimensional device architectures, and novel materials. Etch systems must now deliver uniform material removal at angstrom-level precision while maintaining high throughput and minimizing defect density. This requirement has accelerated adoption of dry etch platforms, which now represent the overwhelming majority of market revenue due to their flexibility in handling complex conductor and dielectric processes. Advanced plasma control technologies, such as direct-drive systems and atomic layer etch capabilities, are becoming essential for manufacturers targeting cutting-edge memory stacks and gate-all-around transistor structures.
Recent product introductions illustrate this innovation wave. In early 2025, Lam Research Corporation unveiled Akara, a conductor etch tool designed with DirectDrive plasma control technology to enable atomic-scale precision for three-dimensional chipmaking. The launch reflects a broader industry emphasis on achieving process stability at dimensions where conventional capacitively coupled or inductively coupled plasma sources no longer provide sufficient control. At the same time, Tokyo Electron Limited announced plans to construct a new production building in Miyagi to expand its plasma etch systems manufacturing capacity. This investment underscores the strategic priority placed on scaling advanced etch hardware in response to sustained demand from high-performance logic and memory producers.
Collaborative innovation is also reshaping the technology frontier. Later in 2025, Lam Research entered a cross-licensing and collaboration agreement with JSR Corporation and Inpria Corporation to advance dry resist technology for atomic layer etching and deposition. Such partnerships highlight a growing recognition that breakthrough etch performance will increasingly depend on ecosystem-level integration rather than isolated equipment improvements. Partnerships linking equipment suppliers with materials developers and research institutions are likely to become more common as the industry addresses the complexity of next-generation patterning and etching sequences.
Plasma Etch System Market
Policy, Regulation, and Geopolitical Dynamics
Regulatory developments have emerged as a defining force in market behavior. The expansion of export controls and entity list actions has introduced new layers of complexity for equipment suppliers, particularly those with global customer bases. In December 2024, the U.S. Bureau of Industry and Security implemented a series of measures affecting advanced semiconductor manufacturing equipment. These actions included adding multiple categories of equipment, including certain etch tools, to the Commerce Control List, expanding the foreign direct product rule to cover foreign-produced equipment destined for China, and adding numerous entities to the Entity List to restrict access to advanced manufacturing technologies.
These policy shifts are not isolated administrative adjustments; they represent a restructuring of how advanced etch capabilities are distributed across global supply chains. For equipment makers, compliance requirements now influence product design, sales territories, service models, and technology roadmaps. For fab operators, procurement strategies must account for regulatory eligibility, spare parts availability, and the long-term viability of certain supply relationships. The practical effect is a bifurcation in market access, where advanced tools may face heightened scrutiny in specific destinations while demand elsewhere continues to grow unimpeded.
In April 2026, the bipartisan MATCH Act introduced further restrictions by prohibiting country-wide sales of cryogenic etch tools and deep ultraviolet immersion lithography systems to any destination within a country of concern. While the immediate impact centers on a limited set of tool categories, the legislation signals an intensifying policy environment where equipment capabilities are evaluated through national security lenses. Manufacturers operating in or serving markets subject to such rules must anticipate additional review mechanisms, potential licensing delays, and the possibility of further classification updates as technology thresholds evolve.
Dry Etching Equipment Market
Demand-Side Shifts and Supply Chain Realities
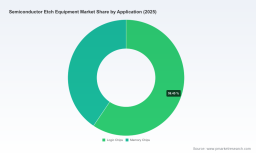
The demand landscape for etch equipment is being reshaped by changes in end-market composition. Logic chip production continues to command a larger revenue share than memory, reflecting sustained investment in advanced computing architectures, artificial intelligence accelerators, and custom silicon for data-intensive workloads. At the same time, memory demand remains robust, particularly for high-bandwidth memory and enterprise storage solutions that require sophisticated conductor and dielectric etch sequences. The revenue balance between conductor and dielectric processes illustrates the breadth of etch requirements, as both categories now depend on increasingly refined process control to support three-dimensional stacking, dense interconnect structures, and critical dimension scaling.
Supply chain considerations add another dimension of strategic importance. Equipment capacity expansions by major manufacturers indicate that demand expectations are strong enough to justify capital-intensive increases in production capability. However, the concentration of market share among a small number of leading firms means that supply constraints or capacity bottlenecks can have outsized effects on lead times and deployment schedules. For fabs planning advanced node transitions, securing equipment slots and aligning process qualification timelines has become a competitive necessity rather than a routine procurement step.
Material and process co-optimization further complicates supply dynamics. As etch requirements converge with advanced resist technologies, deposition tools, and metrology systems, the performance of etch equipment is increasingly tied to its compatibility with surrounding process modules. This interdependence encourages integrated procurement strategies and strengthens the value of long-term supplier relationships that can support co-development, joint debugging, and rapid process iteration.
Competitive Landscape and Strategic Positioning
The market structure is characterized by intense concentration, with a small number of companies commanding the majority of revenue. Such concentration typically correlates with high barriers to entry, including the need for deep process expertise, substantial R&D investment, global service infrastructure, and proven reliability in high-volume manufacturing environments. Within this framework, competitive advantage is increasingly defined not simply by scale, but by the ability to deliver differentiated process performance, broaden application coverage, and respond rapidly to evolving customer roadmaps.
Applied Materials, Lam Research, and Tokyo Electron stand out as central forces shaping market direction. Lam Research has pursued a multi-pronged strategy that blends product innovation, capacity expansion, research collaboration, and ecosystem partnerships. Its recent activities range from the Akara launch and the donation of a multi-chamber etch system to UC Berkeley's Marvell Nanofabrication Laboratory, to the cross-licensing agreement on dry resist technology. These moves position Lam at the intersection of advanced process development and future workforce and materials innovation, reinforcing its relevance across both high-volume production and frontier research.
Tokyo Electron's facility expansion in Miyagi signals a commitment to scaling plasma etch systems production, which supports its ability to meet growing demand while maintaining manufacturing quality. Such investments are strategically significant because they expand the company's capacity to serve multiple advanced logic and memory programs simultaneously, reducing the risk of localized supply disruptions and improving responsiveness to changing fab requirements.
Beyond the top-tier incumbents, a broader set of participants competes in specialized segments of the etch equipment market. Companies such as Oxford Instruments, SPTS Technologies, Plasma-Therm, ASML Holding, ULVAC, NAURA Technology Group, Hitachi High-Tech, and SAMCO operate across different technology niches, regional footprints, and application focuses. Oxford Instruments, for example, supplied its PlasmaPro 100 Cobra atomic layer etch system to Rigetti Computing for quantum device fabrication, highlighting how specialized etch capabilities can open pathways into emerging domains where precision and material compatibility are paramount. Such moves illustrate that competitive differentiation often comes from aligning tool capabilities with specific device technologies, advanced packaging formats, or novel material systems rather than competing directly in mainstream high-volume segments.
The competitive trend is therefore one of partial divergence. Leading suppliers continue to strengthen their broad platform positions through sustained R&D and global service reach, while smaller or specialized firms seek advantage through focused technology depth, regional proximity, custom integration, or support for niche application areas. Over time, this structure may encourage selective partnerships, technology licensing, or targeted acquisitions as larger players seek to fill capability gaps and specialized firms seek routes to scale.
Future Trends and Emerging Commercial Opportunities
Looking ahead three to five years, several interconnected trends are likely to shape market behavior and open commercial opportunities. First, atomic-scale and area-selective etch technologies will move from specialized demonstrations to broader production relevance. As device architectures become more three-dimensional and materials more diverse, the ability to etch with high selectivity and minimal damage will be critical for both conductor and dielectric processes. Equipment suppliers and fab operators that invest early in process integration, recipe development, and in-line metrology for these capabilities can capture value through improved yield, faster ramp cycles, and expanded application coverage.
Second, advanced packaging and heterogeneous integration will continue to expand the role of etch equipment beyond traditional front-end logic and memory fabrication. Tools that can handle precision structuring for interposer layers, through-silicon vias, microbumps, and stacked die arrangements will benefit from growing adoption of multi-die and chiplet-based designs. This trend creates opportunities for suppliers that can adapt etch platforms to packaging-intensive workflows and for fabs that can align etch process development with broader packaging roadmaps.
Third, regulatory and geopolitical divergence will encourage the development of regionalized supply strategies and compliance-oriented business models. Equipment suppliers may need to design product portfolios, service networks, and licensing approaches that accommodate different market access rules without sacrificing technological leadership. For customers, this environment increases the importance of supply resilience, long-term service agreements, and engineering support that can sustain operations even when sourcing options shift. Companies that proactively build flexible procurement and deployment strategies will be better positioned to manage compliance uncertainty while maintaining process continuity.
These trends do not come without risk. Technology transitions can face yield challenges, process integration complexity, and cost pressures that delay adoption. Regulatory frameworks may expand further or shift in scope, affecting equipment eligibility and cross-border support models. Capacity investments by leading suppliers may also reshape competitive dynamics, intensifying pressure on mid-tier players that cannot match scale or cannot clearly differentiate their offerings. Anticipating these risks requires scenario planning, close monitoring of policy developments, and a willingness to adjust product, sourcing, and partnership strategies as conditions evolve.
Strategic Considerations for Decision Makers
For semiconductor equipment manufacturers, the current environment rewards disciplined investment in process differentiation and ecosystem alignment. Priorities include advancing plasma control and atomic-scale etch capabilities, expanding production capacity in coordination with demand signals, and developing partnerships that extend technology reach into materials, resist systems, and advanced packaging workflows. Manufacturers should also evaluate how regulatory exposure may affect product design, market access, and service delivery, ensuring that compliance considerations are integrated into product planning rather than treated as an afterthought.
For investors, the market presents a landscape where growth is supported by structural demand but where competitive outcomes will depend heavily on execution, differentiation, and regulatory navigation. Investment evaluation should account for a company's ability to sustain R&D intensity, expand into application areas with durable demand, and manage geopolitical risk without losing technological edge. Visibility into equipment roadmaps, customer qualification pipelines, and regional exposure can help distinguish operators positioned for durable growth from those exposed to commoditization or access constraints.
For fab operators and procurement leaders, the key imperative is to align equipment strategy with long-term process roadmaps while safeguarding supply continuity. This includes mapping etch requirements across conductor, dielectric, logic, and memory workflows, securing early engagement with equipment suppliers for advanced tool evaluations, and building resilience into spare parts, service support, and qualification timelines. Given the concentration of the market and the complexity of advanced process integration, access to timely, granular intelligence can materially improve sourcing decisions, partnership selection, and capacity planning.
As the market continues to evolve, the value of detailed, up-to-date insight will only increase. A comprehensive research report can provide deeper segmentation data, company-level positioning profiles, regional dynamics, and scenario-based guidance tailored to specific strategic questions. Stakeholders seeking to refine equipment selection, assess competitive exposure, or plan investments around advanced etch capabilities may find that a more detailed source of analysis helps translate broad trends into concrete action.
For detailed analysis of this topic, please visit the official page: Semiconductor Etch Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


