



Class 1E Nuclear Instrumentation Cables Market: 3.6% CAGR Trajectory and 2032 Outlook

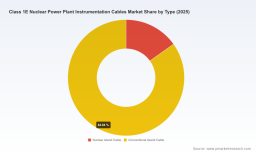
Strategic Trends and Commercial Opportunities in the Class 1E Nuclear Power Plant Instrumentation Cables Market
Market Overview and Core Challenges
The Class 1E instrumentation cables market for nuclear power plants has demonstrated steady growth over the past half-decade, evolving from a niche specialty segment into a critical infrastructure component with defined long-term trajectory. Between 2020 and 2025, the global market expanded from approximately $31.51 million to $38.25 million, reflecting a compound annual growth rate that positions the sector for continued expansion. Projections through 2032 indicate the market will reach nearly $50 million, with a forecasted CAGR of 3.6 percent. This growth profile is notable in an industry often characterized by long lead times and conservative capital allocation, suggesting that instrumentation cable demand is becoming increasingly decoupled from the traditional cycles of new plant construction and more tightly linked to lifecycle management, digitalization, and regulatory modernization.
Despite the positive trajectory, the market faces several structural challenges that will shape competitive dynamics and investment decisions over the next decade. The first challenge lies in the tension between aging fleet management and new build programs. A significant portion of installed nuclear capacity in North America and Europe operates beyond original design life assumptions, requiring continuous cable replacement, requalification, and system upgrades. Simultaneously, the pipeline of new nuclear projects, particularly small modular reactors and advanced designs, introduces different qualification pathways and interface requirements that legacy cable manufacturers must adapt to without compromising performance or compliance. Balancing these two demand streams creates operational complexity for suppliers and procurement teams alike.
The second challenge centers on qualification rigor and regulatory consistency. Class 1E cables are safety-related components, and their qualification frameworks are deeply embedded in standards such as IEEE 323, IEEE 383, and 10 CFR 50.49. While these frameworks provide necessary assurance for loss-of-coolant accident and high-energy line break environments, they also impose lengthy testing cycles, documentation burdens, and configuration control requirements. Any divergence in how regulators or utilities interpret environmental qualification, field splice approval, or aging management can create delays, cost variability, and supplier risk. This dynamic makes regulatory alignment a strategic variable rather than a static compliance checkbox.
A third challenge involves material evolution and environmental compliance. The push to eliminate certain brominated flame retardants, including DecaBDE, has reshaped wire and cable formulations. Suppliers must maintain nuclear-grade performance while adhering to evolving chemical restrictions, such as those enforced under U.S. EPA regulations. This transition affects insulation integrity, jacket durability, and long-term aging behavior, requiring revalidation of qualifications and potentially altering supply chain sourcing strategies. Companies that manage this transition smoothly gain a credibility advantage, while those that lag face technical and commercial exposure.
Key Drivers Shaping Market Dynamics
Several interconnected forces are driving the growth and transformation of the Class 1E instrumentation cables market. Understanding these drivers provides a foundation for evaluating where commercial opportunities are most likely to materialize.
Mineral Insulated Cables Market
Technological Innovation and Long-Life Design Requirements
Technological progress in cable design is a primary catalyst. The industry trend toward 60-year service life expectations places emphasis on radiation resistance, thermal stability, and mechanical durability under accident conditions. Leading cable solutions now target qualification levels that support operation in loss-of-coolant accident and high-energy line break environments while maintaining signal integrity for monitoring, data recording, and control functions. For example, certain Class 1E instrumentation cables are engineered to endure harsh nuclear environments and support safety-critical circuits for reactor coolant pumps, safety valves, and control rod positioning. This level of performance is not merely a technical specification; it directly influences plant safety case submissions, asset life extension strategies, and the willingness of operators to standardize on fewer qualified suppliers.
Innovation also extends to cable types and application coverage. Instrumentation cables serve distinct roles inside and outside the reactor island, and the requirements differ materially. Cables installed inside the reactor environment must address higher radiation doses, stricter LOCA/HELB exposure scenarios, and tighter integration with safety systems. Cables outside the reactor face different environmental and electrical stressors but remain subject to rigorous qualification because they support safety-related instrumentation. Meanwhile, nuclear island and conventional island cable categories continue to evolve as plant designs integrate more digital I&C architectures and require greater separation between safety and non-safety functions. These design shifts are pushing suppliers to develop qualified product families that can be configured for multiple plant zones without compromising compliance.
Policy and Regulatory Environment
Regulatory frameworks remain a defining driver of market structure and supplier qualification strategies. The alignment of cable qualification with IEEE 323, IEEE 383, and 10 CFR 50.49 creates a common baseline, but the operational interpretation of these standards influences purchasing behavior and project timelines. Regulatory guidance that reinforces environmental qualification expectations and field splice requirements increases the value of suppliers that can demonstrate robust documentation, traceability, and quality systems. In this environment, the presence of a NQA-1 quality program and compliance with 10 CFR Appendix B becomes a commercial differentiator, not just a quality administrative measure.
Policy momentum around nuclear as a low-carbon baseload source is also indirectly strengthening instrumentation cable demand. As governments and utilities reassess energy security and decarbonization pathways, nuclear fleet retention, life extension, and selective new build programs receive greater attention. Even when new construction timelines remain long, the associated engineering, qualification, and supply chain preparations begin early. This means instrumentation cable suppliers that can support both legacy fleet upgrades and emerging reactor designs are better positioned to capture demand across multiple project phases.
Demand-Side Changes and Operational Priorities
Utilities and plant operators are increasingly prioritizing reliability, aging management, and digital integration. As plants pursue license renewals and output optimization, instrumentation systems must maintain accuracy and availability over extended horizons. This drives replacement and retrofit activity for cables that support safety-related monitoring and control functions. At the same time, the shift toward more data-intensive operations increases the importance of instrumentation cabling that can reliably transmit measurement and status information without introducing noise or degradation risks. Demand is therefore not limited to new installations; it is equally shaped by the need to preserve and modernize existing safety systems.
Procurement behavior is also evolving. Operators are placing greater weight on supplier qualification records, installed base references, and demonstrated compliance histories. In safety-critical contexts, the perceived risk of adopting unproven cable solutions often outweighs marginal cost differences. As a result, suppliers with extensive installation footprints and clear qualification narratives gain preference in competitive evaluations. This dynamic reinforces the importance of track record, technical documentation, and long-term service commitments in shaping demand patterns.
Supply Chain and Cost Structure Considerations
Cost structures in this market are influenced by raw material selection, qualification overhead, and manufacturing controls. The move toward DecaBDE-free formulations illustrates how environmental compliance can intersect with material cost and performance validation. Suppliers that proactively adjust formulations and maintain qualification status reduce the risk of project disruption and rework. In parallel, quality program requirements and rigorous testing increase the fixed cost of participation, which tends to favor established manufacturers with scalable processes and documented quality systems. This does not necessarily fragment the market; instead, it raises the barrier to entry and rewards suppliers that can manage both technical and regulatory complexity efficiently.
Supply chain resilience is becoming more relevant as utilities seek to reduce uncertainty in long-lead safety-related components. For instrumentation cables, resilience is not only about volume availability but also about consistency of qualification, traceability of materials, and the ability to support field modifications or replacements without compromising safety cases. Suppliers that can provide transparent documentation and repeatable production controls are better positioned to meet these expectations.
Competitive Landscape and Leading Strategies
The competitive landscape is characterized by a concentrated group of specialized manufacturers with strong regional footprints and differentiated qualification narratives. Market concentration reflects the high barriers associated with safety-related cable qualification, installed base development, and ongoing compliance maintenance. With the top three competitors holding a combined share around 55 percent and the top five near 57 percent, the market favors incumbents that have invested in long-term qualification programs and accumulated references across multiple plant environments.
Prysmian, based in Italy, has built its positioning around fully environmentally qualified Class 1E instrumentation cables that support monitoring, data recording, and information transmission within safety-critical circuits. Its offering is designed to meet IEEE 323, IEEE 383, and 10 CFR 50.49 requirements for LOCA/HELB environments and is structured around long service life expectations. A notable aspect of its strategy is the emphasis on environmental compliance, including DecaBDE-free formulations aligned with U.S. EPA prohibitions. This combination of nuclear qualification and environmental regulatory alignment gives Prysmian a dual narrative: technical assurance for safety-related applications and forward compatibility with chemical restriction trends.
Marmon IEI, headquartered in the United States, differentiates through radiation-resistant LDVC, control, and instrumentation cables, including its RSCC® product line, with installations reported across more than 130 nuclear plants worldwide. Its strategy emphasizes proven field deployment and quality system rigor, with manufacturing conducted under a 10 CFR Appendix B, NQA-1 quality program. This installed base and quality framework create a strong reference advantage in utility evaluations, particularly where operators value documented performance across diverse plant conditions and long operational horizons.
Shawflex, based in Canada, focuses on EQ/Class 1E nuclear-grade power, control, and instrumentation cables and assemblies tailored for CANDU, LWR, and SMR plants. Its qualification scope includes IEEE 323, IEEE 383, and CSA N290.13, with performance targets up to 250 Mrad/200°C and 60-year life expectations. By spanning multiple reactor types and supporting both traditional and emerging designs, Shawflex positions itself as a flexible supplier for markets where reactor diversity and program-of-record considerations matter. This multi-design capability is especially relevant as SMR interest expands and operators seek suppliers that can adapt to different environmental and qualification contexts.
Habia Cable, headquartered in Sweden, supplies Habiatron™ LOCA and non-LOCA Class 1E instrumentation cables, including thermocouple types, for applications such as reactor coolant pumps, safety valves, and control rod positioning. Its designs are built around a 60-year operational life in nuclear safety systems. Habia's strategic emphasis on safety system-critical applications reinforces its positioning as a specialist in high-consequence instrumentation circuits, where qualification integrity and application specificity are paramount.
Okonite Company, also based in the United States, offers Okoguard and FMR-N Class 1E nuclear power, control, and instrumentation cables qualified per IEEE 383 and 10 CFR 50.49 for safety-related applications in nuclear generating stations. Its approach aligns with the broader U.S. market emphasis on regulatory conformity and safety-related use cases, supporting utilities that prioritize documented compliance and established product families for in-service and new installation contexts.
Across these competitors, several strategic themes emerge. First, qualification depth is a core competitive asset. Suppliers that can demonstrate alignment with multiple standards and provide clear environmental qualification narratives are better positioned to win preference in utility procurements and life-extension projects. Second, installed base and reference installations matter significantly. In a market where safety cases and aging management decisions influence purchasing, demonstrated deployment across many plants reduces perceived risk. Third, product family breadth is increasingly valuable. Suppliers that can serve both nuclear island and conventional island needs, or support multiple reactor technologies, gain flexibility in bid responses and can better align with operator standardization goals.
PW Consulting
The market is likely to evolve through a combination of consolidation among qualified specialists and selective entry by suppliers capable of meeting the qualification and quality system thresholds. Pure price competition is less effective in this context because qualification, documentation, and compliance overhead create natural cost floors. Instead, differentiation will come from technical assurance, application coverage, regulatory readiness, and the ability to support both legacy fleet and new build requirements. New entrants will face steep barriers unless they bring differentiated qualification pathways, strong quality system infrastructure, or unique application expertise.
Future Trends and Commercial Opportunities
Looking ahead to the 2026 to 2032 period, several trends are likely to shape the Class 1E instrumentation cables market and create distinct commercial opportunities.
One key trend is the acceleration of lifecycle management demand for existing fleets. As more assets approach or exceed original design horizons, operators will continue to invest in cable replacement, requalification, and system upgrades to support license renewal and reliability objectives. This trend favors suppliers that can offer qualified replacement solutions, clear aging management guidance, and efficient integration with ongoing plant modifications. Commercial opportunities will arise not only in cable sales but also in technical support services that help operators manage qualification continuity and minimize interruption to safety-related systems.
A second trend is the growing relevance of reactor design diversity, including SMRs and advanced concepts. While new build volumes may remain uneven, the preparatory engineering and qualification work associated with these designs will stimulate demand for instrumentation cables that can meet varied environmental and regulatory expectations. Suppliers that can map their qualification portfolios to multiple reactor types and demonstrate adaptability to different safety system architectures will be better placed to capture early engagement opportunities. Over time, if SMR deployments scale, standardized cable solutions that can be reused across projects may create volume efficiencies and reduce qualification redundancy.
A third trend is the continued intersection of nuclear qualification and environmental material compliance. As chemical restrictions and sustainability expectations evolve, cable formulations will keep adapting. This creates opportunities for suppliers that can maintain nuclear performance while meeting broader environmental goals. It also introduces a strategic consideration for procurement teams: material transitions should be evaluated not only for regulatory compliance but also for qualification implications, long-term aging behavior, and supply continuity. Suppliers that proactively manage these transitions can convert a compliance requirement into a competitive advantage.
These trends carry inherent uncertainties. Regulatory interpretation can shift, project timelines can slip, and material qualification updates can introduce delays if not managed carefully. In addition, the balance between fleet life extension and new build momentum will vary by region, affecting where demand concentrates and how suppliers should allocate development resources. Market participants should therefore treat these trends as directional signals rather than guaranteed outcomes, and build flexibility into their qualification, sourcing, and engagement strategies.
Extra High Voltage Cables Market
Actionable Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to strengthen qualification narratives and reduce friction in compliance demonstration. This includes maintaining robust documentation across IEEE 323, IEEE 383, and 10 CFR 50.49 expectations, ensuring quality systems align with NQA-1 and 10 CFR Appendix B expectations where relevant, and preparing clear pathways for material transitions such as DecaBDE-free formulations. Suppliers should also consider expanding application coverage to address both nuclear island and conventional island needs, and evaluate how their product families can support multiple reactor types without fragmenting qualification efforts. Differentiation will increasingly come from the ability to combine technical assurance, regulatory alignment, and practical deployment experience.
For investors, the market offers exposure to a specialized, compliance-driven segment with steady long-term demand characteristics. The most relevant indicators are not short-term volume spikes but the durability of qualification programs, the breadth of installed references, and the capacity to serve both life-extension and new build contexts. Due diligence should focus on whether a company's qualification assets are portable across projects, whether its quality systems can withstand regulatory scrutiny, and whether its material and supply strategies are resilient to evolving environmental requirements. Investments in suppliers that can sustain 60-year service life narratives and maintain compliance efficiency are better positioned to benefit from the market's projected growth path.
For procurement teams and utility decision-makers, the focus should be on reducing long-term risk through supplier selection that emphasizes qualification continuity, documented compliance, and application fit. Given the safety-related nature of Class 1E instrumentation cables, preference should be placed on suppliers with strong reference installations and transparent quality frameworks, especially when cables must support aging management, field modifications, or integration with modernized I&C architectures. Procurement strategies should also account for the potential impact of material transitions on qualification status and service life, ensuring that compliance decisions do not inadvertently create technical or schedule risk. Detailed segment-level intelligence can help clarify which supplier profiles and product families best match specific fleet conditions, reactor types, and project phases.
For readers seeking a deeper breakdown of segment dynamics, regional demand patterns, and tailored strategic scenarios, the full PW Consulting report provides expanded data and decision frameworks beyond the overview presented here.
For detailed analysis of this topic, please visit the official page: Class 1E Nuclear Power Plant Instrumentation Cables Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


