



Beyond the 6.09% CAGR: What’s Really Driving the $11.34B Mascara Market Through 2032

The Mascara Market at an Inflection Point: Strategic Trends and Commercial Opportunities (2026–2032)
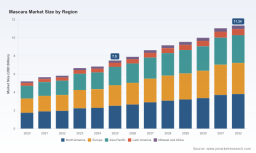
The global mascara market has matured into a high-contrast landscape where volume growth coexists with intensifying structural pressures. Over the historical period from 2020 to 2025, the category expanded from approximately 5.2 billion USD to 7.5 billion USD, reflecting steady consumer demand and repeated product innovation cycles. The trajectory continues into the forecast window through 2032, with the market projected to reach 11.34 billion USD and a compound annual growth rate of 6.09 percent. These figures are not just a measure of incremental sales; they signal a category that is broadening its functional promises, migrating across channels, and being reshaped by sustainability mandates and packaging engineering. For executives and investors, the central question is no longer whether mascara will grow, but which value pools will capture disproportionate share and how fast the cost and compliance curves will move.
Beneath the headline expansion sits a market that is consolidating around a small number of global players while simultaneously fragmenting at the formulation, applicator, and packaging levels. The top three participants command roughly 65 percent of category revenue, and the top five extend that share to nearly 78 percent. This concentration indicates that scale advantages in acquisition, distribution, and brand architecture remain powerful, yet the same concentration also invites targeted disruption from niche formulators, regional manufacturers, and contract partners that can move faster on ingredient innovation, applicator design, and sustainable packaging. The market’s evolution is therefore best understood as a dual dynamic: broad-based growth on the outside, competitive differentiation on the inside.
Market Snapshot: Growth with Consolidation
The category’s growth curve has been supported by multiple reinforcing forces: repeat purchase behavior in daily wear, demand for specialized effects such as lengthening, volume, and curl retention, and a broadening pipeline of prestige and mass-market SKUs. Yet the distribution of revenue concentration also underscores a strategic reality. Scale players benefit from global supply visibility, retail relationships, and cross-brand leverage, but they must continually reinvest in formulation, claims substantiation, and packaging upgrades to defend shelf space and e-commerce visibility. Mid-tier and private-label manufacturers, by contrast, compete on speed, customization, and cost-efficient production, positioning themselves as critical nodes for brands that want to expand their mascara assortments without building in-house capacity.
For decision-makers, this snapshot translates into a clear takeaway: growth is real, but it is not evenly distributed across players, formats, or geographies. The opportunity lies in identifying which sub-segments of the value chain are most exposed to margin expansion, which formats are most likely to command premium pricing, and where entry barriers are low enough to reward agile innovation rather than brute scale.
Current Structural Challenges and Turning Points
The category faces three interconnected challenges that are reshaping how companies plan capacity, R&D, and go-to-market strategy. First, formulation and applicator performance are increasingly scrutinized by consumers who expect lash-care benefits, precise application, and long-lasting wear without smudging or flaking. Achieving these claims simultaneously creates engineering tension: richer formulas can compromise brush glide, while lighter formulas may reduce pigment intensity or curl retention. Companies that can integrate lash-conditioning attributes with high-pigment delivery and ergonomic application will be better positioned to defend premium price points.
Second, sustainability and material compliance are moving from marketing narratives to operational constraints. The packaging and applicator segments are under pressure to reduce fossil-based plastics, lower carbon intensity, and increase recycled content. This transition is not cosmetic; it affects tooling, supplier qualification, quality control, and cost structures. Where sustainable materials were once a differentiation layer, they are now becoming a baseline expectation in many retail and channel environments. Firms that delay material transitions risk facing procurement friction and brand perception gaps, while those that move early can secure supplier relationships and design leadership.
Lipstick Market
Third, competitive intensity is compressing the room for undifferentiated entry. The high concentration at the top means that new claims, packaging novelty, and branded storytelling must be unusually sharp to gain attention. At the same time, contract manufacturers and private-label suppliers are expanding their capabilities, making it easier for brands to launch with credible production backing. The result is a market where speed-to-shelf and formulation distinctiveness matter as much as scale. Pure price competition is increasingly risky because it erodes the investment needed for sustained innovation and compliance.
Key Drivers Reshaping the Mascara Category
The market’s direction is being pulled by a mix of technology, regulation, consumer behavior, and supply economics. Understanding how these forces interact is essential for assessing where durable advantage can be built.
Innovation in Formulation and Applicator Engineering
Performance expectations have expanded beyond basic volume and length. Consumers increasingly look for brush designs that improve precision and product deposition, formulas that support lash condition, and finishes that balance wear time with natural movement. Brush geometry and fiber selection directly influence how mascara coats lashes, how easily it separates clumped product, and how well it holds a curl. Innovation in this area is becoming a tangible source of differentiation rather than a purely aesthetic exercise.
Recent activity in the applicator space reflects this shift. At major industry events, suppliers have showcased packaging and applicator technologies with stronger sustainability profiles and design novelty. One German manufacturer presented a collection built around new brush designs and shadow printing decoration on packaging made from 100 percent post-consumer recycled plastic, an approach that also reduces CO₂ emissions by up to 26 percent. A UK-based packaging supplier introduced a cellulose-derived renewable fiber applicator intended as a renewable alternative to synthetic materials for mascara and brow products. These developments are significant because they combine performance engineering with material transition, showing that sustainability and application quality can be advanced together rather than traded off.
For manufacturers and brand owners, the implication is clear: applicator and packaging innovation is becoming a competitive lever that affects both consumer perception and operational sustainability. Companies that treat brush design and material science as core R&D priorities can create more defensible product architectures and reduce exposure to future material restrictions.
Regulatory and Sustainability Pressure as a Design Constraint
Sustainability commitments are increasingly embedded in brand and supply strategies rather than treated as separate CSR initiatives. In the mascara category, this means greater attention to formulation origin, biodegradability or natural derivation targets, recyclable packaging, and lower-carbon manufacturing outcomes. Public commitments from major groups have set ambitious timelines for making a high share of mascara formulations biodegradable or naturally derived, reinforcing a direction that is likely to influence sourcing standards, ingredient selection, and supplier qualification across the industry.
This regulatory and reputational environment creates both risk and opportunity. On the risk side, companies dependent on legacy synthetic formulations or non-recyclable packaging may face rising compliance costs and potential channel resistance. On the opportunity side, brands that align formulation, packaging, and communications early can build authenticity in a category where consumers are increasingly attentive to material claims. Importantly, credibility depends on consistent execution across the value chain, not on isolated packaging swaps. A sustainable brush paired with an unchanged formula or a vague messaging strategy can undercut the intended effect.
Consumer and Channel Behavior Shifts
Demand patterns are evolving around use context, not just product type. Daily wear remains the dominant usage environment, which sustains high baseline demand and repeated purchase cycles. At the same time, event and professional makeup applications continue to support premium SKUs and specialized finishes. The practical effect is that the category is served by a dual rhythm: a high-frequency core that rewards reliability, ease of use, and value, and a higher-margin periphery that rewards performance claims, packaging prestige, and trend responsiveness.
Channel dynamics reinforce this bifurcation. E-commerce and digitally native brands have lowered the barrier for launches and made it easier for smaller labels to reach niche audiences. Retail environments, however, still reward shelf impact, repeat conversion, and strong claims substantiation. In practice, this means that brands must reconcile two demands: the consumer-facing promise that drives first purchase, and the consistent performance that drives repurchase and recommendation. Mascara is a category where disappointing performance is difficult to hide, so formulation reliability and applicator consistency are not just product attributes; they are commercial safeguards.
Supply Chain and Cost Structure Pressures
Material availability, packaging input costs, and production flexibility are becoming more prominent in strategic planning. As brands shift toward recycled and renewable materials, they also shift their dependency map, which can introduce new qualification cycles and short-term cost variability. At the same time, manufacturers that can offer a broad texture range, multiple packaging options, and scalable private-label production are increasingly valuable partners for brands managing portfolio complexity.
This environment favors companies that can balance cost discipline with innovation readiness. In practical terms, that means maintaining a supplier base capable of meeting sustainability specifications, investing in process stability to reduce rework and waste, and designing product architectures that can be adapted across markets without excessive rework. For procurement and operations leaders, the goal is not only to manage today’s input costs, but to build a supply architecture that can absorb material transitions without compromising quality or delivery.
Competitive Landscape and the Shape of Advantage
Scale Leaders and Their Strategic Postures
The market’s leading participants are pursuing different but overlapping forms of advantage. One global group anchors its mascara portfolio across mass and prestige brands, using strong brand architecture to cover a wide range of performance claims and price points. Another large corporation competes in the premium and clinical-influenced space with an emphasis on wear technology and curl retention across several established labels. A third major consumer goods company focuses on accessible volume and lengthening performance through mass-market brands, leveraging distribution breadth and price accessibility.
These scale players share common strengths: global reach, significant R&D resources, established retail relationships, and the ability to cross-leverage brand equity across regions. Their strategic challenge is to keep portfolios fresh enough to maintain relevance while maintaining the consistency required to defend volume. In a concentrated market, leadership is less about presence and more about continuous renewal of claims, formats, and packaging stories.
Prestige Positioning and Regional Specialists
On the prestige side, luxury houses and regional specialists compete through differentiated application mechanisms, refined aesthetic signatures, and targeted lash-care narratives. Some players emphasize advanced brush technology and long-lasting pigmentation to justify premium positioning; others focus on precise application and conditioning benefits in Asian markets, where preferences for curl, length, and clean formulation can be especially pronounced. There are also K-beauty-aligned developers working on curling and lengthening effects that respond to regional styling expectations.
This segment is less about raw scale and more about design credibility, application elegance, and regional nuance. For premium brands, the opportunity lies in making performance claims feel both sophisticated and demonstrable, while for regional specialists the opportunity lies in translating local preferences into exportable innovation.
The Expanding Role of Contract and Private-Label Manufacturing
A significant portion of category expansion is enabled by manufacturers that provide end-to-end production, custom formulas, and diverse applicator and packaging options. These partners support a wide spectrum of brand strategies, from budget-priced launches to more premium private-label projects. Their value proposition is increasingly tied to speed, flexibility, and the ability to produce multiple texture ranges without requiring the brand to build its own factory footprint.
Several manufacturers in this space operate with long track records in color cosmetics and a strong export orientation, while others offer customizable formulas and packaging support for direct and private-label markets. This layer of the industry is strategically important because it lowers the execution risk for new product development and allows brands to test concepts with less capital intensity. For investors and brands evaluating partnerships, the key is to assess a supplier’s capability not just in volume output, but in claim-ready formulation control, packaging consistency, and sustainable material readiness.
PW Consulting
How the Landscape Is Evolving
The competitive field is not simply consolidating; it is reconfiguring around capability clusters. At one end, global brands seek scale, portfolio coverage, and sustainability credibility. At the other, contract manufacturers and applicator suppliers create the infrastructure that enables more launches, faster iteration, and more material options. Between them, private-label and regional players can win by offering either cost-efficient execution or distinctive formulation and packaging combinations that larger players may not prioritize immediately.
The most likely trajectory is continued concentration among the largest branded players, alongside a vibrant mid-tier and supplier ecosystem that expands the number of viable market entrants. This means the market will keep generating both acquisition targets and partnership opportunities. The brands and investors that benefit most will be those that can distinguish between genuine capability and surface-level novelty when evaluating potential collaborations or acquisitions.
Outlook: Three Trends Shaping 2026–2032
Trend 1: Performance-Material Integration as a New Standard
The most durable opportunity in the category is the convergence of performance engineering and sustainable material design. Brush architecture, fiber selection, formula delivery, and recyclable or renewable packaging are increasingly evaluated together, not in isolation. Products that can combine lash condition, precise application, and credible material transitions will have an advantage in both consumer acceptance and long-term regulatory resilience. The commercial payoff is not just premium pricing; it is reduced exposure to future input constraints and stronger brand trust in a category where performance disappointment is highly visible.
The accompanying risk is execution complexity. Integrating new materials may require tooling changes, supplier requalification, and reformulation work that affects cost and lead time. Brands that underestimate these operational demands may find sustainability positioning difficult to sustain at scale.
Trend 2: Claim Substantiation and Credibility as Commercial Moats
As claims around volume, length, curl hold, and lash care multiply, substantiation becomes a competitive necessity. Consumers and retail partners increasingly expect supported statements rather than aspirational language alone. In practice, this trend elevates the importance of testing, consistency, and formulation discipline. Companies that build robust evidence pipelines can defend price and shelf space more effectively, while those relying on vague promises will face growing pressure as the category becomes more crowded and more scrutinized.
A key risk here is overclaiming relative to actual performance. In mascara, weak substantiation can quickly translate into reviews, repurchase issues, and brand erosion. The upside is similarly strong: credible, well-communicated performance can drive both trial and loyalty, especially in daily-use categories where repetition matters.
Trend 3: Regional Specialization and Exportable Innovation
Preferences for curl, length, conditioning, and finish are not uniform across markets, and the category’s growth will continue to be shaped by regional taste profiles as well as global brand reach. Asian markets, for example, have shown strong interest in precision application and conditioning-oriented benefits, while other regions may prioritize long-wear, waterproof resilience, or volume. This diversity favors companies that can localize formulas and brush designs without losing production efficiency, and it creates export opportunities for regional innovators who can translate local preferences into formats that travel well.
Face Mask Market
The main uncertainty is globalization versus localization balance. Over-standardizing can blunt regional relevance, while over-fragmenting can raise cost and complexity. The winning model is likely to combine a core platform with region-specific adaptations, allowing scale where possible and differentiation where necessary.
Strategic Implications for Decision-Makers
The mascara category is expanding, but the value is being created by companies that align innovation, sustainability, and execution discipline rather than by those that rely on growth alone. The following priorities are most relevant across common stakeholder groups.
- For manufacturers and brand owners, prioritize applicator and packaging innovation as core product strategy, not as a secondary packaging decision. Treat brush design, fiber choice, and material transitions as levers that influence both performance perception and long-term compliance readiness.
- For investors, distinguish between branded scale that is being renewed through credible formulation and packaging programs and scale that is resting on legacy assets. The stronger opportunities are likely in platforms that can demonstrate sustainable material readiness, substantiated performance, and flexible manufacturing partnerships.
- For procurement and supply chain leaders, build resilience into material sourcing by qualifying suppliers capable of meeting recycled and renewable specifications without sacrificing quality consistency. Map the transition risks early so that sustainability targets do not create unexpected production bottlenecks.
Across all three perspectives, timely and detailed market intelligence is valuable because the category is moving on multiple fronts at once: formulation expectations, applicator technology, packaging materials, and concentration dynamics. Decisions made without a clear view of where capacity, differentiation, and regulatory pressure are heading can lead to missed entries, underestimated costs, or weak claim positioning. A more complete picture of segment-level dynamics, regional variation, and supplier capability typically separates reactive planning from proactive positioning.
For teams that need a deeper breakdown of segmentation details, regional patterns, and competitive capability mapping, the full PW Consulting market report provides expanded data and customized analytical context to support more precise strategic planning.
For detailed analysis of this topic, please visit the official page: Mascara Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


