



Wedding Dress Market 2026: Why 6.08% CAGR Reshapes Growth Beyond $280M

The Wedding Dress Market: Navigating Growth, Innovation, and Strategic Positioning
Market Snapshot and Core Challenges
The wedding dress market has entered a phase of steady, structurally driven expansion. Revenue grew from approximately 120.0 million USD in 2020 to 186.0 million USD in 2025, reflecting a compound annual growth rate of 6.08 percent across the historical period. The trajectory is expected to continue, reaching an estimated 280.7 million USD by 2032. This growth is not merely a post-pandemic rebound; it signals a maturing consumer base willing to allocate discretionary spending to wedding apparel, supported by broader economic recovery and shifting social habits around engagement and celebration.
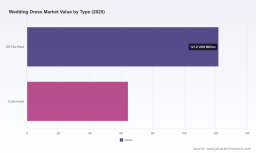
Despite the favorable top-line momentum, the industry faces three defining challenges that will shape competitive outcomes over the next several years. First, market concentration remains moderate, with the top three players holding roughly 25 percent of revenue and the top five capturing about 30 percent. This fragmentation means scale advantages are limited, and leadership cannot rely on dominance alone. Instead, differentiation, brand trust, and operational resilience determine share gains. Second, the apparel supply chain continues to navigate cost volatility, material availability, and lead-time uncertainty. Manufacturers and designers must balance premium craftsmanship expectations with the pressure to deliver predictably, especially as wedding calendars become more compressed and customization requests grow. Third, the market is experiencing a shift in how gowns are sourced and used. The relative weight of off-the-rack and customized offerings, alongside usage patterns spanning personal purchase, rental, and photographic studio needs, indicates that consumers are no longer choosing based on category alone. They are evaluating total experience, flexibility, and perceived value. Companies that treat these categories as siloed segments risk missing cross-category demand signals.
Wedding Ring Market
For executives, the practical implication is clear: healthy growth does not automatically translate into profitable growth. The winners will be those who address structural friction in sourcing, inventory, and customer experience while building brand narratives that justify price points and repeat engagement.
Key Drivers Shaping Market Dynamics
Several forces are converging to reshape how value is created in the wedding dress market. Understanding these drivers is essential for anticipating where competitive advantage will emerge.
Technological Innovation and Operational Breakthroughs
Digital design tools, fit simulation, and data-informed inventory planning are reducing the cost of experimentation while improving speed to market. Designers can prototype more variations with fewer physical samples, and retailers can align stock levels more closely with demand patterns. These capabilities matter because the wedding dress category has traditionally relied on intuition and seasonal collections. Technology is now enabling more responsive design cycles, better sizing accuracy, and fewer unsold units. For manufacturers, the same tools support more efficient production scheduling and clearer communication with buyers, which is especially valuable in a market where customization and detail-oriented craftsmanship carry premium expectations.
Party Costumes Market
Policy and Regulatory Environment
Operational transparency, labor standards, and material sourcing requirements are becoming more visible across the apparel sector. While the wedding dress market is not subject to a single defining regulation, broader expectations around responsible sourcing and production practices are influencing procurement decisions. Brands and factories that can document sourcing practices, maintain consistent quality controls, and demonstrate reliable compliance are increasingly preferred by retailers and international buyers. This trend does not fundamentally alter demand, but it raises the barrier for informal or opaque supply chains and rewards operators with disciplined processes and traceable operations.
Demand-Side Shifts in Consumer and Business Behavior
Consumers are approaching wedding apparel with more deliberate criteria. Personal purchase remains a major driver, but the purchase decision is increasingly shaped by fit, style longevity, sustainability considerations, and the overall service experience rather than brand name alone. At the same time, rental and photographic studio applications continue to represent meaningful demand pools, reflecting a broader willingness to treat wedding apparel as part of a flexible celebration ecosystem rather than a single-use asset. This is pushing businesses to think beyond the gown as a standalone product and toward integrated offerings that combine styling, access, and presentation.
On the business side, buyer preferences are also changing. Retailers and distribution partners want predictable replenishment, clearer differentiation, and strong visual identity. The market’s moderate concentration means many brands compete on aesthetics and localization, but the most resilient operators are those that connect product quality with measurable service reliability.
Supply Chain and Cost Structure Evolution
The cost environment remains a central concern. Material prices, labor conditions, shipping variability, and production lead times all influence margin stability. In response, many operators are reassessing make-versus-buy decisions, supplier concentration, and inventory depth. The practical shift is toward greater diversification and more disciplined planning. Rather than relying on a single production model, leading participants are building flexibility into sourcing and capacity, allowing them to respond to regional demand changes and minimize disruption. This flexibility is becoming a strategic asset, particularly for companies that must serve both premium custom work and higher-volume lines without compromising delivery performance.
Competitive Landscape and Leading Strategies
The competitive field is broad and geographically diverse, spanning established American-designed brands, European manufacturing capacity, Asian production capabilities, and specialized luxury or contemporary players. This diversity is one of the market’s defining features. It creates opportunities for niche differentiation, but it also raises the need for clear positioning.
Strategic Positioning Among Key Players
Several themes emerge when looking at how leading companies compete. American-designed brands tend to emphasize design identity, detail, and perceived craftsmanship. Some highlight handmade construction or in-house production, using that narrative to support premium pricing and loyalty. Others focus on contemporary aesthetics or romantic detailing to attract buyers looking for distinctiveness rather than conventional styles. Luxury-oriented brands build their value proposition around exclusivity, fit, and collection storytelling, often reinforced through events and seasonal launches that keep the brand in front of buyers and press.
Meanwhile, manufacturing-centric participants compete on scale, reliability, and customization support. Large production facilities in Europe and Asia serve as critical capacity nodes for broader industry demand, offering wholesale and made-to-order capabilities that allow brands and retailers to access consistent output. Their advantage lies in volume flexibility, repeatable quality, and the ability to support a range of design specifications. In parallel, some brands are leaning into modern, sustainable, or niche aesthetic directions to stand out in a crowded field, recognizing that differentiation often comes from a coherent point of view rather than from broad assortment alone.
PW Consulting
Differentiation as the Core Competitive Lever
Because market concentration is moderate, no single company dominates the category through size alone. That makes positioning especially important. The strongest operators combine a recognizable design language with dependable execution. They do not simply sell a gown; they sell a coherent experience that includes fit, presentation, delivery, and brand trust. Events such as trade show attendance, collection launches, and designer-focused gatherings play a visible role in maintaining that presence. Recent industry activity illustrates this rhythm: Ricca Sposa appeared at Barcelona Bridal Fashion Week in April 2026, Anne Barge introduced its Fall 2026 collection at New York Bridal Fashion Week in May 2026, Kaya Wedding attended European Bridal Week in April 2026, and Allure Bridals hosted designer events including Once Upon a Dress in May 2026. These moments are not merely calendar items; they are mechanisms for reinforcing brand relevance, testing demand cues, and maintaining relationships with retailers, press, and buyers.
How the Landscape Is Evolving
The market is evolving along multiple paths at once. On one side, there is room for continued fragmentation, as new designers and regional brands enter with targeted aesthetics or direct-to-consumer models. On the other side, consolidation pressure exists for players that need scale in production, distribution, or brand reach. The most likely outcome is not a simple winnowing, but a layered market in which a few broadly recognized names anchor consumer awareness while many specialized players compete in distinct niches. New entrants that can articulate a clear design identity, demonstrate reliable fulfillment, and build digital visibility will have a realistic path to relevance. Established players, meanwhile, will need to protect their positioning by refreshing collections, strengthening supply discipline, and deepening relationships with the channels that matter most to their customers.
Outlook for the Next Three to Five Years
Looking ahead, three trends are likely to define strategic opportunities and risks.
- Design and sourcing will become more integrated. As digital tools and production planning improve, brands that can connect design intent with manufacturing capability more tightly will gain speed and consistency. This integration supports both premium custom work and broader line efficiency, reducing the tension between uniqueness and scalability.
- Consumer expectations will keep moving toward experience-rich purchasing. Fit, personalization, presentation, and post-purchase service will matter as much as the gown itself. Companies that create a smoother journey from discovery to delivery will be better positioned to defend margins and build repeat engagement, including through rental and studio-related demand where appropriate.
- Regional production and supply diversification will remain strategic priorities. The market’s growth will continue to depend on reliable capacity and predictable lead times. Businesses that concentrate all sourcing in one channel or region may face unnecessary exposure, while those that build a balanced supplier base and maintain contingency options will be more resilient to cost and logistics shocks.
These trends open practical opportunities. Design-led brands can deepen loyalty by strengthening fit, service, and collection coherence rather than relying solely on aesthetic novelty. Manufacturers and wholesalers can capture value by becoming more responsive partners, offering clear customization pathways, and demonstrating dependable output. Retail and distribution players can use stronger supplier relationships and better assortment planning to reduce inventory risk while maintaining visual freshness. At the same time, uncertainty remains. Economic fluctuations can affect discretionary spending, costume and accessory demand can shift as celebration habits evolve, and competitive pressure can intensify if too many brands chase the same aesthetic or price point. The market’s growth is durable, but profitability will still depend on disciplined execution.
Strategic Recommendations for Decision-Makers
Different participants will need different priorities, but several actions apply broadly.
For Manufacturers and Brand Operators
Invest in the capabilities that connect design to delivery. That means clearer production planning, flexible sourcing, and fit or sizing improvements that reduce returns and rework. Build a distinctive design position that can be communicated consistently across channels, and treat events and seasonal launches as strategic touchpoints rather than optional marketing activities. Consider where customization, wholesale, and own-brand offerings can coexist without diluting operational focus.
For Investors
Focus on operators with a credible differentiation story and evidence of execution discipline. In a moderately concentrated market, scale alone is less decisive than brand clarity, supply reliability, and channel relationships. Evaluate whether a company’s design identity is sustainable, whether its production model can support demand without compromising quality, and whether its go-to-market approach aligns with changing consumer behavior. Look for signs that the business can manage cost volatility while preserving margin integrity.
For Retailers and Procurement Teams
Prioritize partners that can deliver consistency, transparency, and flexibility. Assortment decisions should balance recognizable style leadership with inventory discipline, and sourcing strategies should not over-concentrate risk in a single supplier or region. Where rental, studio, or multi-use demand is relevant to the customer base, partner selection should reflect the ability to support varied use cases, not just standard retail distribution. Commercial terms and delivery reliability will matter as much as design appeal when planning for seasonal peaks.
Strategic decisions in this market are most effective when informed by detailed segmentation, regional dynamics, and competitive benchmarks. Broad trends indicate direction, but precise choices about product mix, sourcing, pricing architecture, and channel focus require deeper data. Readers seeking a more granular view of segment splits, company positioning, and forward demand scenarios can explore the full PW Consulting Wedding Dress Market research report for expanded analysis and tailored strategic guidance.
For detailed analysis of this topic, please visit the official page: Wedding Dress Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


