



Induction Cooktop Market: How 5.6% CAGR and Asia Pacific Demand Reshape 2032

Induction Cooktop Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
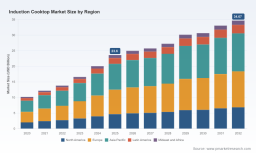
The global induction cooktop market has entered a period of sustained expansion, with total industry revenue climbing from USD 10.2 billion in 2020 to an estimated USD 23.6 billion in 2025. The trajectory reflects a compound annual growth rate of 5.6 percent through 2032, a pace that signals structural rather than cyclical momentum. By the end of the forecast window, revenue is projected to approach USD 34.7 billion, driven by a steady shift in residential and commercial kitchens away from traditional gas and coil electric surfaces. This growth is not uniform across all segments, however. The market is increasingly shaped by diverging regional adoption curves, pricing pressure in entry-level categories, and a competitive field where the top three players control roughly 36 percent of revenue and the top five hold approximately 45 percent.
For executives and investors watching the sector, the headline numbers obscure several inflection points that will determine who captures value in the coming years. First, the transition from early-adopter households to mainstream consumers has exposed gaps in installer readiness, electrical infrastructure, and consumer education. Many retrofit projects stall because older homes lack the dedicated circuits or panel capacity required for high-wattage induction surfaces. Second, the commercial segment is growing but faces a distinct set of hurdles: kitchen operators must reconcile higher upfront equipment costs with labor savings, ventilation reductions, and heat-load benefits that are not always straightforward to quantify in a single payback period. Third, the supply chain for core components, particularly ceramic glass and induction coils, remains concentrated in a small number of sourcing regions, creating vulnerability for manufacturers who have not diversified or stocked strategic inventory.
These challenges are not insurmountable, but they do require a more granular approach to product planning, channel strategy, and risk management. Companies that treat induction as a simple swap-in replacement for gas or electric cooktops will likely underinvest in the installation support, warranty structures, and total-cost messaging that mainstream buyers and commercial operators need.
Stainless Steel Cookware Market
Key Drivers Shaping the Market
Technology Innovation and Breakthroughs
Induction cooktops are no longer defined solely by speed and efficiency. Recent product introductions demonstrate a clear push toward surface durability, granular temperature control, and outdoor applications that extend the technology beyond the indoor kitchen. A March 2026 launch introduced a matte finish engineered to reduce visible scratches by a factor of five, directly addressing one of the most common consumer objections to glass-ceramic surfaces. In August 2025, a premium brand unveiled a temperature-controlled induction cooktop that had earned recognition at a major kitchen and bath industry show, signaling that precision cooking features are becoming a differentiator rather than a niche luxury. Earlier, in February 2025, the industry saw the first built-in outdoor induction cooktop capable of precise control across a 150°F to 450°F range, opening a new use case for patios, restaurants with open-air concepts, and multi-zone residential setups.
These innovations matter because they broaden the addressable market. Scratch-resistant surfaces reduce the perceived maintenance burden for families and high-traffic commercial kitchens. Fine-grained temperature control supports culinary outcomes that appeal to passionate home cooks and professional chefs alike. Outdoor-capable units create opportunities in markets where gas infrastructure is restricted, costly, or undesirable from a safety and air-quality standpoint. For manufacturers, the strategic implication is clear: the next wave of volume growth will come from features that solve practical pain points, not from raw wattage alone.
Policy and Regulatory Environment
Government and utility initiatives are steadily reshaping the economics of adoption. In June 2025, the Global LEAP Awards released a buyer's guide for induction cooktops designed to help governments and manufacturers identify high-quality, energy-efficient models. This kind of curated reference material lowers the search cost for procurement teams and public-sector buyers who may otherwise hesitate without trusted benchmarks. Meanwhile, regional incentive programs are beginning to put direct financial support behind residential upgrades. A program effective from January 2026 offers rebates of up to $500 for ENERGY STAR certified induction cooktops, a meaningful reduction that can tip the decision for price-sensitive households.
PW Consulting
On the efficiency front, public messaging from the U.S. Department of Energy continues to emphasize that induction appliances can be up to 10 percent more energy-efficient than conventional electric smooth-top ranges and roughly three times more efficient than gas stoves. This narrative is increasingly relevant in markets where building codes, climate targets, and indoor air-quality concerns are converging. The practical effect is twofold: policy support reduces the effective price gap for consumers, and regulatory alignment gives manufacturers a more predictable demand environment in which to plan production and channel investment.
Demand-Side Shifts in Consumer and Commercial Behavior
The demand story is more nuanced than a single narrative of electrified kitchens. In residential settings, the strongest pull comes from buyers who value faster heating, cooler surrounding surfaces, and easier cleanup, alongside a growing segment motivated by indoor air quality and lower ambient heat in the kitchen. In commercial environments, the value proposition leans on operational factors: reduced ventilation requirements, lower cooling loads, and precise heat modulation that can improve consistency and reduce waste. Commercial adoption is still being calibrated, however, because the equipment cost premium and the need to retrain staff on new workflows can slow rollout even when the operational case is sound.
What unites these demand shifts is a move from abstract efficiency claims to concrete, task-specific benefits. Consumers and operators respond faster when the message is tied to a daily experience—how quickly a pot comes to a boil, how little residual heat remains on the surface, how little smoke or combustion byproduct lingers in the room. Marketing and sales teams that can translate technical performance into these everyday outcomes are gaining an edge in conversion.
Supply Chain and Cost Structure Dynamics
Component sourcing remains a strategic pressure point. Ceramic glass and induction coils used in cooktops are still largely imported from China, a concentration that exposes manufacturers to shipping volatility, tariff uncertainty, and lead-time risk. The practical consequence is that cost structures can shift quickly when trade conditions tighten or when demand spikes outpace available capacity. Companies that rely on single-source or just-in-time logistics for critical components face the greatest exposure, especially during product launches or seasonal demand surges.
The cost story is not purely a risk factor; it also creates a differentiation opportunity. Manufacturers that secure multi-region sourcing, build buffer inventory for key inputs, or invest in supplier partnerships with clearer quality and delivery commitments can stabilize margins and protect launch timelines. In a market where premium surface coatings, temperature-control electronics, and outdoor-rated components are becoming more common, the ability to reliably source and integrate these elements is increasingly part of the competitive formula.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of large appliance majors and specialized commercial players, each with a distinct route to value. GE Appliances markets a full line of induction cooktops, including a profile series built around precision control and connected features, positioning the brand at the intersection of performance and smart-home integration. Samsung Electronics brings Flex Zone and power boost technologies to the table, emphasizing flexible zoning and rapid heating for efficient home cooking. Miele & Cie competes in the premium tier with an emphasis on durability and long-term reliability, a positioning that resonates with buyers who view the cooktop as a long-lived kitchen investment. Whirlpool Corporation spans multiple brands, leveraging JennAir, KitchenAid, and Whirlpool to cover a wide price and style spectrum while offering advanced temperature control and wipe-clean surfaces.
Electrolux Group, through Frigidaire, focuses on surface engineering, most notably with the introduction of a matte surface designed to reduce visible scratches and preserve appearance over time. BSH Hausgeräte operates across Bosch, Thermador, and Gaggenau, offering high-output and full-surface options that serve both mainstream and luxury segments. The Vollrath Company occupies a specialized niche with commercial-grade induction cooktops built for professional foodservice and restaurant environments, where ruggedness and serviceability matter as much as cooking performance.
These players illustrate three strategic archetypes. The first is broad-scale differentiation through ecosystem and brand breadth, where a portfolio of brands and connected features aims to capture consumers across price tiers. The second is premium durability and control, where the pitch is long service life, refined cooking precision, and surfaces that hold up to daily use. The third is vertical specialization, where a company concentrates on commercial-grade engineering and the specific operational requirements of foodservice operators. Each archetype is defensible, but each also carries different risks: broad portfolios can dilute focus if execution falters across brands, premium positioning depends on consistently delivering perceived quality, and commercial specialization requires strong service and support networks to sustain customer relationships.
The market structure is evolving along several lines. Consolidation pressure is likely to remain moderate but real, as larger groups seek to strengthen channel coverage and component procurement leverage. At the same time, there is room for targeted fragmentation in outdoor, commercial, and ultra-premium niches where specialized features command attention. New entrants are less likely to win on commodity segments and more likely to gain traction by pairing a clear feature advantage with a credible installation or service proposition. Recent launches underscore this dynamic: matte surface durability, temperature-controlled cooking, and outdoor-built-in capability are not incremental tweaks, they are market-expanding moves that reset expectations for what an induction cooktop can do.
Worldwide Induction Coils Market
Future Trends and Commercial Opportunities
Looking ahead three to five years, three trends are likely to shape where value accrues. First, premiumization through practicality will continue to gain ground. Scratch-resistant matte finishes, temperature precision, and outdoor capability are turning induction from a performance upgrade into a lifestyle and operational upgrade. Manufacturers that can deliver these features at a defensible cost position will be able to command stronger margins and better brand loyalty than those competing only on price.
Second, policy-supported adoption will become a more reliable demand driver in select regions. The combination of efficiency messaging, curated quality guides, and rebate programs reduces friction for mainstream buyers and public-sector purchasers. Companies that build offerings to align with recognized certification standards and that can clearly communicate eligible incentive value will have an easier path to conversion. This is especially relevant where energy costs, air-quality regulations, and electrification targets are reinforcing each other.
Third, supply-chain resilience will move from a back-office concern to a competitive differentiator. As advanced surface treatments, control electronics, and specialized form factors become more common, the ability to source reliably and manage component risk will influence launch speed, warranty exposure, and ultimately customer satisfaction. Firms that diversify sourcing, strengthen supplier relationships, and plan for lead-time variability will be better positioned to sustain growth through trade or logistics disruptions.
These trends create concrete commercial opportunities. Premium residential lines can be built around surface durability and precision cooking features that justify higher price points without relying solely on brand heritage. Commercial offerings can target operators who need robust equipment, predictable service, and clear documentation of operational savings through reduced heat load and ventilation demands. Outdoor and multi-zone solutions can open new installation scenarios in markets where gas is restricted or where homeowners want flexible cooking spaces. Each opportunity, however, carries its own set of risks: premium features must deliver measurable quality improvements, commercial sales must be backed by installation and service capacity, and outdoor products must perform reliably in variable environmental conditions.
Actionable Guidance for Decision Makers
For manufacturers, the priority is to align product roadmaps with the features and use cases that are expanding the market rather than merely defending existing share. Surface durability, temperature precision, and outdoor-rated designs are no longer niche experiments; they are signals of where consumer expectations are moving. At the same time, sourcing strategies for ceramic glass and induction coils should be revisited to reduce exposure to concentrated import dependency. Building redundancy into critical component supply, clarifying quality commitments with suppliers, and ensuring launch timing is supported by inventory buffers can protect both margin and brand reputation.
For investors, the most informative question is not whether induction will continue to grow, but where the value is being created and captured. Portfolio breadth, premium durability positioning, and commercial specialization each offer defensible paths, but they require different execution capabilities and carry different margin profiles. The recent wave of product launches suggests that differentiation through practical features is a credible growth lever, and that companies able to pair innovation with reliable supply and channel execution are better placed to convert market growth into durable returns.
For procurement and kitchen operators, the decision framework should move beyond upfront price and toward total cost and operational fit. Incentives and rebate programs can materially improve economic outcomes when models meet recognized efficiency standards, and commercial buyers should weigh ventilation, cooling, and workflow benefits alongside equipment cost. Selecting products with strong surface engineering and clear service support can reduce long-term maintenance exposure, while outdoor or multi-zone options can unlock flexible layouts that gas or conventional electric surfaces may not support as cleanly.
Detailed segment-level sizing, regional growth patterns, and company-specific positioning data can sharpen these decisions further. The full research report provides the granular breakdowns and customized recommendations needed to translate these strategic trends into specific investment, product, and sourcing choices.
For detailed analysis of this topic, please visit the official page: Induction Cooktop Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


