



Isononyl Alcohol Market: Why 5.55% CAGR Changes Everything Through 2032

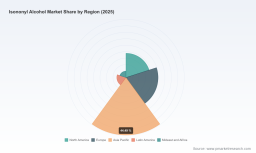
Isononyl Alcohol Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The isononyl alcohol market has matured into a cornerstone of specialty chemical supply chains, anchored by consistent growth in plasticizer and surfactant applications. Valued at approximately $1.5 billion in 2025, the market has expanded steadily over the past half-decade, with historical revenues climbing from $1.2 billion in 2020 to current levels. Forecasts indicate a continued upward trajectory, projecting revenues to surpass $2.1 billion by 2032 at a compound annual growth rate of 5.55 percent. This growth pattern reflects both cyclical demand recovery and structural shifts toward higher-performance, non-phthalate intermediates.
Behind the headline figures, the industry confronts several pivotal challenges that will shape competitive positioning over the next decade. The first is the tension between cost efficiency and sustainability compliance. As regulatory frameworks tighten and end-use customers demand verified circular sourcing, producers must justify capital expenditures for bio-based feedstocks, traceable supply chains, and certified manufacturing processes without sacrificing margin performance.
The second challenge lies in demand concentration and substitutability risk. A significant share of isononyl alcohol consumption flows into plasticizer formulations, where formulation engineers continuously evaluate alternatives such as alternative oxo alcohols, bio-derived esters, and phosphate-based systems. Suppliers cannot rely on legacy volume assumptions; they must demonstrate differentiated performance, regulatory readiness, and supply reliability to retain share in evolving formulations.
The third challenge is geographic and capacity imbalance. Production capacity remains clustered among a handful of integrated manufacturers, while demand growth is accelerating in regions with expanding PVC processing, personal care manufacturing, and industrial lubricant consumption. New capacity additions in East Asia and Southeast Asia are reshaping supply dynamics, but they also intensify competition for feedstock access, logistics optimization, and customer qualification. These pressures create a market where incumbents must defend margins through operational excellence and sustainability credentials, while newer entrants seek footholds through technology licensing, strategic partnerships, and targeted application specialization.
Key Demand Drivers
Several interconnected forces are steering the market’s direction, and each carries distinct implications for sourcing strategies, capacity planning, and product development.
Technological Innovation and Process Differentiation
Advancements in oxo synthesis and hydroformylation continue to redefine quality parameters and cost structures. Modern catalyst systems, improved isomer control, and integrated downstream purification enable producers to deliver higher-purity grades suitable for sensitive applications, including specialty esters and electronics-adjacent formulations. Process refinements also support narrower specification ranges, which matter for downstream formulators seeking consistent plasticizer performance and reduced variability in surfactant blends. Manufacturers that pair process reliability with flexible grade portfolios are best positioned to capture premium segments and reduce the cost of customer qualification.
A parallel wave of innovation centers on sustainability-linked production. Certification frameworks and circular sourcing commitments are moving from optional differentiators to operational requirements. Recent certification activity at major production sites signals that sustainable sourcing and circular economy compliance are becoming embedded in commercial offerings rather than remaining aspirational. For buyers and partners, this shifts the conversation from whether a supplier can provide certified material to how consistently it can do so across volumes and geographies.
Regulatory and Compliance Evolution
Regulatory oversight remains a decisive factor in formulation choices and supply chain design. Registration and compliance documentation for isononyl alcohol underpin its continued use in plasticizers and related applications, giving formulators confidence in long-term availability. At the same time, the broader regulatory environment is nudging the market away from traditional phthalate architectures and toward alternatives that preserve performance while meeting evolving safety and environmental expectations. This does not eliminate isononyl alcohol’s role; rather, it reinforces its position as a versatile intermediate when paired with compliant manufacturing practices and transparent documentation.
The practical impact is twofold. First, compliance readiness becomes a competitive asset, particularly for suppliers serving multiple jurisdictions with differing registration and traceability requirements. Second, the regulatory trajectory encourages investment in grades and processes that can adapt to reformulated end products, reducing the risk of stranded capacity as customer specifications change.
Demand-Side Shifts in End-Use Industries
Demand patterns are being reshaped by formulation trends in plastics, personal care, and industrial lubricants. In plasticizer applications, the push toward non-phthalate and high-performance alternatives sustains interest in isononyl alcohol as a building block for DINP and related systems, especially where flexibility, durability, and processing characteristics remain critical. In personal care and fragrance-adjacent uses, formulators are seeking emollient ingredients that offer consistent skinfeel and stability, driving niche but high-value demand for specialty grades. Lubricant applications add another layer of demand resilience, as industrial and automotive segments pursue formulations that balance performance with extended drain intervals and efficiency goals.
These demand-side shifts reward suppliers that can offer application-specific grades, technical support, and reliable lead times. The market is increasingly less about commodity volume alone and more about the ability to match grade attributes to formulation requirements, which in turn supports more stable pricing and deeper customer relationships.
Supply Chain and Cost Structure Dynamics
Cost structures are influenced by feedstock availability, energy pricing, and the geographic distribution of production assets. Integrated producers with access to reliable olefin streams and efficient hydroformylation operations hold a structural advantage in managing input cost volatility. At the same time, regional capacity additions are altering logistics patterns, with new facilities positioned to serve fast-growing demand centers and reduce freight exposure for local customers.
Capacity expansion announcements, including large-scale projects utilizing established technology licenses, indicate that supply will continue to broaden in key regions. These developments can improve availability and create competitive price tension, but they also place a premium on qualification speed, supply consistency, and technical service. In practical terms, the cost equation is no longer determined solely by feedstock prices; it increasingly reflects the value of certified continuity, grade flexibility, and regional proximity to demand.
Competitive Landscape and Leading Strategies
The market features a concentrated group of global manufacturers alongside regional specialists and new capacity entrants. Leading firms differentiate through a combination of process technology, grade breadth, certification readiness, and application-focused commercial support. Their strategic positioning offers a useful lens for understanding where value is being created and how the landscape is likely to evolve.
Strategic Positioning of Core Players
German-based producers have strengthened their standing by combining integrated oxo alcohol capabilities with a focus on sustainability certification and application breadth. One major manufacturer operates isononyl alcohol production tied to its C4 chemicals platform, supplying plasticizer and surfactant grades through hydroformylation of C8 olefins, and has reinforced its sustainability positioning through certification valid through mid-2026. Another industry leader leverages partnership structures and its own facilities to serve plasticizer applications at scale, supported by ongoing regulatory compliance documentation that facilitates use across multiple markets.
Specialty oxo intermediates producers have built reputation on grade consistency and global distribution, offering both plasticizer and specialty chemical grades that serve diverse formulation needs. In the United States, large chemical companies provide isononyl alcohol through established oxo processes at major complexes, with emphasis on DINP and high-purity plasticizer applications. One North American supplier focuses on specialty esters and non-phthalate plasticizer supply, aligning its offering with shifting formulation preferences. In Asia, integrated producers with large complexes supply PVC plasticizer grades for domestic and export markets, benefiting from regional demand growth and logistics advantages.
Additional players contribute to the landscape through portfolio breadth and targeted application focus. A Swedish producer offers isononyl alcohol within a broader C8-C10 oxo alcohol portfolio for plasticizers and lubricants, while a Japanese manufacturer supports high-purity grades for electronics and automotive uses through licensed oxo processes. A South African producer supplies the chemical within its oxo alcohol portfolio for plasticizer and surfactant applications. Most recently, a major Chinese refining and chemical company has moved to build a world-scale isononyl alcohol facility using licensed technology, with startup targeted for 2026, signaling a meaningful addition to regional supply.
Isononanoic Acid Market
Differentiation Themes and Competitive Advantages
Across these players, differentiation converges on a few recurring themes. Process control and grade purity are foundational, particularly for customers in sensitive applications where specification consistency reduces downstream risk. Sustainability certification and traceable sourcing are increasingly weighted in supplier selection, especially where end customers require documented circular economy alignment. Commercial agility matters as well: producers that can balance large-volume plasticizer supply with specialty grades and provide technical support are better equipped to retain customers during formulation changes.
Regional presence and logistics efficiency also shape advantage. Suppliers with production assets close to fast-growing demand centers can reduce lead times and freight exposure, while those with global distribution networks can serve multinational customers more consistently. Finally, technology licensing and partnership models are enabling new capacity to enter the market with established process knowledge, accelerating scale-up and reducing execution risk relative to wholly custom development paths.
PW Consulting
Evolving Market Structure
The competitive structure is gradually shifting from a purely incumbent-centric model to one that balances established scale with targeted new entry. On one side, large incumbents are defending their positions through certification, application focus, and integration benefits. On the other, new capacity in Asia and Southeast Asia is expanding regional supply and intensifying competition for both volume and specialty demand. This does not necessarily imply a race to the bottom; rather, it suggests a market where differentiation narrows the field. Customers are likely to consolidate spending with suppliers that can demonstrate reliable certification, consistent grade quality, and strong technical support, while price competition intensifies in commoditized segments.
Over time, this dynamic may encourage further consolidation among smaller players lacking scale or certification readiness, while rewarding those that can combine capacity with application expertise. The emergence of large, licensed facilities also raises the importance of customer qualification pipelines and long-term supply agreements, as new volumes must be absorbed into established formulation ecosystems.
Worldwide Isononyl Acrylate Market
Forward Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to define the market’s trajectory and open practical opportunities for aligned businesses.
Sustainability-Linked Supply as a Commercial Baseline
Certified, traceable production is expected to move from advantage to baseline expectation in many customer segments. As procurement teams embed sustainability criteria into supplier evaluation, producers with valid certifications and documented circular sourcing will face lower barriers to qualification and retention. Commercial opportunities here include premium-grade offerings that pair performance with compliance, long-term supply arrangements that reward certified continuity, and regional partnerships that reduce the logistical footprint of sustainable supply. The risk is that capability gaps in certification or traceability could limit access to certain customer segments, especially where end-market requirements are stringent.
Grade Specialization and Application-Focused Targeting
The market is likely to reward narrower, application-specific grade strategies over undifferentiated volume plays. In plasticizer formulations, high-purity and performance-tuned grades will remain important where formulators seek predictable processing and end-product characteristics. In personal care, fragrance, and lubricant applications, specialty grades that meet specific sensory, stability, or efficiency requirements can command stronger positioning. Businesses that invest in grade flexibility, technical service, and customer co-development are better placed to capture value in these segments. The uncertainty lies in the pace of formulation change: if alternative chemistries gain traction faster than expected in certain applications, suppliers must be ready to adapt grade portfolios without overcommitting to legacy demand assumptions.
Regional Capacity Rebalancing and Supply Chain Reconfiguration
New capacity additions in East Asia and Southeast Asia will continue to reshape supply geography, creating opportunities for regional price competitiveness, faster service, and reduced logistics risk for nearby customers. For buyers, this can translate into more options for local sourcing and improved resilience. For suppliers, it raises the stakes in qualification speed, distribution capability, and customer relationship depth. The risk is that rapid capacity additions could create temporary oversupply in specific regions or grades, pressuring margins unless offset by demand growth or differentiated offerings. Strategic positioning will depend on aligning capacity with demand centers while maintaining cost discipline and certification readiness.
Actionable Guidance for Decision-Makers
Different stakeholders face distinct priorities, but a few strategic actions apply broadly and can help convert market trends into tangible outcomes.
-
Manufacturing and supply leaders should prioritize certification continuity and grade flexibility as core commercial assets. Maintaining valid sustainability certification, strengthening documentation for regulatory compliance, and expanding the ability to supply application-specific grades can improve qualification speed and customer retention. Where possible, align production and logistics with regional demand growth to reduce lead times and freight exposure.
-
Investors and corporate development teams should evaluate opportunities through the lens of differentiation rather than scale alone. Capacity additions that pair licensed process technology with sustainability credentials and application focus are more likely to secure qualified demand than undifferentiated volume projects. Attention to customer qualification pipelines, regional demand timing, and downstream formulation trends can materially affect the risk-adjusted returns of new capacity or partnership investments.
-
Procurement and sourcing professionals should build supplier evaluation frameworks that weigh certified continuity, grade consistency, and technical service alongside price. In a market where regulatory compliance and sustainability documentation are increasingly important, multi-source strategies that include both scaled incumbents and regionally positioned suppliers can improve resilience. For critical applications, securing long-term arrangements with suppliers able to demonstrate stable certification and consistent specifications can reduce disruption risk and support formulation stability.
The isononyl alcohol market is entering a phase where growth is real but value capture depends on execution quality. Sustainability certification, grade specialization, regional supply strategy, and application-focused technical support are becoming central to competitive success. Businesses that treat these elements as strategic priorities, rather than operational afterthoughts, will be better positioned to navigate demand shifts, regulatory evolution, and new capacity entry.
For organizations seeking deeper segmentation data, regional demand profiles, and customized scenario analysis, PW Consulting’s full market research report provides detailed breakdowns and tailored recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Isononyl Alcohol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


