



Fuel Cell Electric Vehicles Market: Decoding 26.6% CAGR Growth Trajectory to 2032

Strategic Horizons: Navigating Commercial Opportunities in the Fuel Cell Electric Vehicle Market
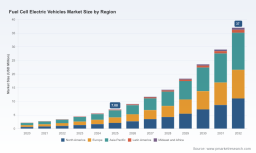
The fuel cell electric vehicle (FCEV) sector is entering a phase of accelerated expansion, driven by technological maturation and targeted policy support. Market valuation in the base year of 2025 reached 7.08 million USD, reflecting a compound annualized growth rate of 26.6 percent across the forecast horizon extending to 2032. This growth trajectory marks a decisive shift from early-niche adoption toward broader commercial deployment, with revenue projections scaling toward 37 million USD by the end of the decade. While passenger segments continue to refine hydrogen integration for range and efficiency, heavy-duty and logistics applications are increasingly anchoring demand, creating asymmetric opportunities across vehicle classes and operational profiles.
PW Consulting Automotive & Machinery Research Center
Defining the Competitive Arena
Market structure currently reflects moderate concentration, with the top three participants capturing roughly 48 percent of total activity and the leading five firms accounting for approximately 52 percent. This distribution suggests room for specialized entrants and regional specialists, particularly where localized infrastructure development or vertical integration creates defensible positions. Leadership is increasingly defined not by aggregate volume but by the ability to align fuel cell architecture, hydrogen sourcing, and operational economics around specific use cases. Companies that treat the stack as a modular component rather than a proprietary black box are gaining flexibility in scaling across passenger, commercial, and stationary applications.
Critical Inflection Points
Three structural challenges are reshaping how stakeholders should evaluate opportunity and risk in this space. The first concerns the pace of refueling network expansion relative to vehicle rollout. Without coordinated station development, adoption patterns risk becoming fragmented, limiting total addressable demand even as vehicle supply improves. The second challenge sits in cost parity, particularly for fuel cell stacks, balance-of-plant systems, and hydrogen procurement contracts. Progress is visible, but sustained reductions depend on manufacturing scale, material innovation, and standardized maintenance models that lower lifetime operating expenses. The third challenge relates to demand-side framing: buyers are weighing total cost of ownership, uptime reliability, and regulatory compliance rather than technology credentials alone, meaning that value propositions must be expressed in operational terms rather than technical specifications.
Key Drivers Reshaping the FCEV Opportunity Set
Technology Pathways and Performance Gains
Advances in stack durability, power density, and cold-start behavior are expanding the practical operating envelope for hydrogen vehicles. Integrated designs that pair fuel cells with buffer batteries are improving transient response and enabling short zero-emission electric ranges, which is particularly valuable for urban delivery, off-road cycles, and environments with access restrictions. These architectures also reduce the burden on hydrogen fueling during stop-start duty cycles, helping operators manage downtime and energy costs.
Recent product activity illustrates how manufacturers are translating these gains into customer-facing value. Honda began customer leasing of the 2025 CR-V e:FCEV through select California dealerships, combining a domestically produced fuel cell module with plug-in battery capability that delivers up to 29 miles of electric range alongside hydrogen refueling. This approach positions the vehicle as a flexible tool for fleets that need both emissions performance and operational resilience. Hyundai reinforced its passenger lineage by debuting an all-new NEXO at the 2025 Japan Mobility Show, previewing a production model that builds on more than two decades of fuel cell development. Meanwhile, BMW has signaled a series-production timeline targeted for 2028, indicating growing confidence in scaling fuel cell platforms beyond demonstration fleets.
Policy Architecture and Regulatory Tailwinds
Regulatory frameworks are increasingly used to channel investment toward specific decarbonization outcomes rather than blanket technology support. In California, the Air Resources Board's 2025 annual evaluation reported 14,128 FCEVs registered as of April 2025, alongside a first recorded year-over-year decline of 291 units. This inflection underscores the sector's transition from early growth momentum to a more measured phase where infrastructure readiness, vehicle availability, and buyer economics must align. At the same time, the evaluation projects a network of up to 112 stations capable of supporting as many as 16,210 FCEVs by 2028, framing the policy task as one of synchronized build-out rather than unconstrained expansion.
Broader industry coordination is reinforcing this direction. The 2025 Hydrogen and Fuel Cell Seminar highlighted commercialization strategies and latest FCEV products, with a notable emphasis on heavy-duty applications where emissions intensity and duty cycles make hydrogen particularly relevant. Policy alignment with decarbonization targets is encouraging fleet operators and equipment manufacturers to experiment with hydrogen in segments where battery-only configurations face practical constraints. The implication for decision-makers is that incentives and mandates are becoming more targeted, and success will depend on matching vehicle deployment to the specific regulatory and operational context of each market.
Demand-Side Behavior and Fleet Economics
Buyers are increasingly evaluating FCEVs through the lens of operational continuity, refueling time, payload capability, and total cost of ownership. In commercial settings, hydrogen's appeal lies in its ability to support long ranges and rapid replenishment without the charging downtime associated with battery-only vehicles, which is especially relevant for heavy-duty trucking, regional logistics, and high-utilization routes. Passenger buyers are weighing similar trade-offs, though their decisions are more sensitive to fuel availability, residual value, and the perceived convenience of the energy pathway. This divergence means that demand creation is uneven: some segments require infrastructure confidence before volume scales, while others can move faster where refueling access and fleet incentives are already in place.
Electric Vehicles and Fuel Cell Vehicles Market
Supply Chain and Cost Dynamics
Cost structures are evolving through a combination of manufacturing scale, component standardization, and hydrogen supply contracts. As fuel cell stacks and related subsystems move from bespoke engineering toward repeatable production, the economics of per-unit cost and service intervals improve. Hydrogen supply is equally important: long-term sourcing agreements, on-site generation where feasible, and logistics optimization can materially affect operating expenses. Companies that vertically coordinate stack production, vehicle integration, and fuel supply are better positioned to manage variability in input costs and to offer predictable service arrangements. Conversely, reliance on fragmented supply chains can expose operators to price swings and availability risk, particularly in early-adopter regions where demand spikes may outpace supply flexibility.
Competitive Landscape and Strategic Positioning
Differentiation Strategies Among Leading Players
Leadership in this market is increasingly articulated through platform strategy, application focus, and ecosystem partnerships rather than headline vehicle counts. Toyota continues to advance its Mirai passenger FCEV, emphasizing integrated hydrogen fuel cell technology and a refined passenger experience. The company's positioning reflects confidence in hydrogen for segments where range, refueling speed, and technology credibility matter, even as it navigates the realities of limited refueling access in some markets. Hyundai has expanded its footprint across both passenger and commercial domains, with the Xcient heavy-duty FCEV and the Nexo passenger vehicle illustrating a dual-track strategy that targets high-utilization commercial demand alongside consumer adoption. This breadth allows Hyundai to apply learning from one segment to another, particularly where stack durability and operational data can be cross-leveraged.
Honda has adopted a modular and flexible approach by combining a U.S.-made fuel cell module with plug-in battery capability in the CR-V e:FCEV, supporting both hydrogen refueling and short electric range. This dual-energy configuration broadens the vehicle's usability and reduces dependence on any single refueling event, which is attractive for early adopters in areas where hydrogen availability is still developing. BMW's focus on series production targeted for 2028 signals an emphasis on manufacturing discipline and product readiness, suggesting a strategy built around scalable architecture rather than limited demonstration runs. Collectively, these positions point to a market in which differentiation is increasingly about how well a company integrates technology, supply, and customer use cases.
Market Evolution and Consolidation Dynamics
The competitive field is likely to evolve through a mix of consolidation, specialization, and selective entry. Established automakers are strengthening their positions through platform investments and product cadence, while component suppliers and hydrogen-focused companies are exploring opportunities to enter at the system, fueling, or service layer. In commercial applications, there is growing potential for partnerships that bundle vehicles, hydrogen supply, and maintenance into integrated offerings, reducing friction for fleet buyers and improving lifetime economics. At the same time, regional disparities in infrastructure and policy create natural fragmentation, where local champions may emerge around specific corridors, ports, or logistics hubs. The result is a landscape where broad scale and localized execution both matter, and where successful players will need to manage multiple business models simultaneously.
Recent events reinforce this multi-speed environment. California's latest evaluation highlights both the maturity of the current registration base and the urgency of expanding the station network to sustain further growth. The FCEV seminar circuit continues to serve as a venue for sharing commercialization strategies and product developments, indicating that the industry is moving from concept discussion to deployment detail. As these dynamics mature, companies that can align product timing with infrastructure milestones and customer readiness will gain an advantage over those that rely solely on technology leadership without considering the operating environment.
Forward Outlook: Trends and Risk Factors for 2026-2030
Trend One: Application-Led Growth in Commercial Heavy-Duty Segments
Heavy-duty and commercial applications are expected to play an outsized role in shaping demand over the next several years. The operational characteristics of long-haul routes, port operations, and high-utilization delivery cycles make refueling time, payload retention, and range reliability especially valuable, which aligns well with hydrogen's strengths. This trend suggests that commercial segments will not only drive volume but also provide the utilization data and service models needed to lower costs and refine stack design. For businesses, the opportunity lies in identifying routes and duty cycles where hydrogen offers a clear total-cost advantage and in structuring supply and maintenance arrangements that reduce operational uncertainty.
Trend Two: Infrastructure Synchronization as a Growth Determinant
Vehicle availability will increasingly need to be matched with station expansion and hydrogen supply reliability. As deployment scales, operators and buyers will scrutinize station uptime, geographic coverage, and pricing consistency, since these factors directly affect fleet planning and consumer confidence. Regions that coordinate station planning with vehicle rollouts and fleet incentives are likely to see faster adoption and more stable economics, while areas where supply and demand develop unevenly may experience slower momentum. This trend elevates the strategic importance of partnerships between vehicle manufacturers, fuel suppliers, and infrastructure developers, as well as the value of standardized operating practices that improve reliability across sites.
Trend Three: Modular Architectures and Dual-Energy Configurations
The integration of fuel cells with buffer batteries and plug-in capability is likely to become more common, offering flexibility in how energy is used across different driving conditions. Such architectures can improve transient performance, support short electric-only operation, and reduce dependence on frequent hydrogen refueling in mixed-use scenarios. This trend also opens the door to more adaptable business models, where vehicles can be configured for specific routes or customer preferences without sacrificing core fuel cell performance. The trade-off is complexity in design and service, so the winners will be those who manage modularity without compromising durability or maintenance simplicity.
Risk Considerations
Several uncertainties could shape the pace and distribution of growth. Infrastructure expansion may lag vehicle availability in some markets, constraining demand even where technology and policy support are strong. Hydrogen pricing and supply reliability remain sensitive to production methods, transport logistics, and contract structures, which can affect operating economics for both fleets and individual buyers. Policy environments may also shift as jurisdictions refine incentives and compliance mechanisms, creating variability in the timing and scale of demand. Finally, competition from battery-electric alternatives in chosen segments could pressure hydrogen's role in passenger applications, making it more important to anchor the value proposition in use cases where hydrogen offers clear differentiation.
Actionable Strategic Recommendations for Decision-Makers
For Vehicle Manufacturers and System Suppliers
Align product planning with the rhythms of infrastructure development and fleet readiness rather than pursuing volume in isolation. Prioritize applications where refueling time, range, and uptime translate into measurable operational advantages, and use those deployments to gather durability data and refine service models. Consider modular or dual-energy architectures that broaden customer appeal in early-adopter markets while preserving a clear core fuel cell value proposition. Build partnerships that connect stack production, vehicle integration, and hydrogen supply, since coordinated offerings can improve economics and reduce buyer friction. Monitor regions where station networks and policy frameworks are converging, and stage product introductions to coincide with practical refueling access rather than projected but unverified capacity.
Hydrogen Vehicle Market
For Investors and Capital Allocators
Evaluate exposure across the value chain with a focus on segments where utilization and total cost of ownership most favor hydrogen. Commercial heavy-duty applications, regional logistics corridors, and integrated fuel-and-service models present opportunities where operating economics can be validated more quickly than in broad passenger markets. Assess companies on the strength of their supply agreements, manufacturing scalability, and ability to manage service intervals, since these factors increasingly determine margin stability and customer retention. Be attentive to policy timing and infrastructure milestones, because demand in early markets can be highly sensitive to station availability and incentive structures. Diversify across complementary positions, including component suppliers, fuel logistics providers, and application-focused integrators, to capture value from different layers of the ecosystem.
For Fleet Operators and Procurement Leaders
Structure procurement around operational confidence and total cost rather than vehicle specifications alone. Prioritize routes and duty cycles where hydrogen's refueling speed, range, and payload characteristics deliver measurable benefits, and pilot deployments in areas with reliable fueling access. Negotiate long-term hydrogen supply terms and service arrangements that reduce variability in operating expenses and downtime. Use early deployments to collect data on fuel consumption, maintenance needs, and vehicle availability, then feed those insights into broader fleet planning. Where feasible, coordinate with multiple stakeholders to strengthen local station coverage and supply reliability, since improved infrastructure benefits not only a single fleet but the entire demand environment.
The Value of Targeted Intelligence
Success in this market depends on reading the interaction between technology, policy, infrastructure, and buyer economics in real time. Broad trends provide direction, but the details that matter most—station rollout timing, supply contract structures, stack durability outcomes, and application-specific economics—require focused analysis. Decision-makers benefit from access to segmented data and scenario-based guidance that connects market movement to operational choices, whether that means sizing a commercial pilot, sequencing product launches, or evaluating where capital will be most efficiently deployed. As the landscape continues to evolve, timely and granular intelligence becomes a practical tool for reducing uncertainty and improving execution.
For detailed analysis of this topic, please visit the official page: Fuel Cell Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


