



Vitamin E Market 2026: Why a 5.3% CAGR Propels Revenue to $3.32 Billion by 2032

Vitamin E Market Outlook 2026–2032: Strategic Trends and Commercial Opportunities
The vitamin E market is navigating a phase of measured expansion, supply-side recalibration, and evolving demand priorities across multiple end-use sectors. With a global market base of approximately USD 2.21 billion in 2025 and a projected compound annual growth rate of about 5.3 percent through 2032, the sector is expected to reach roughly USD 3.32 billion by the end of the forecast period. This trajectory reflects steady demand from nutraceuticals, animal nutrition, functional foods, and personal care, but it also masks underlying structural shifts that will determine which players capture disproportionate value in the coming years.
Several forces are reshaping competitive dynamics. Demand patterns are becoming more differentiated by geography and application, while sourcing, regulatory compliance, and formulation science are increasingly important differentiators. At the same time, capacity constraints, input volatility, and shifting labeling requirements are forcing companies to rethink procurement, product architecture, and commercial strategy. The following analysis outlines where the market stands today, what is driving change, how incumbents are positioning themselves, and where the most actionable opportunities lie for decision-makers over the next three to five years.
Market Snapshot: Growth Trajectory and Structural Challenges
A Market Expanding at a Moderate but Consistent Pace
The vitamin E market has grown from roughly USD 1.65 billion in 2020 to an estimated USD 2.21 billion in 2025, with forward projections pointing to a 2032 valuation near USD 3.32 billion. The implied 2026–2032 CAGR of about 5.3 percent reflects steady, rather than explosive, growth. This pace is consistent with a mature but still expanding category, where volume and price dynamics are influenced by both demand-side pull and supply-side friction.
Demand is broadly distributed across dietary supplements, animal nutrition, functional food and beverages, and cosmetics and other applications. The supplement segment remains the largest contributor to total demand, supported by consumer interest in immune health, antioxidant benefits, and aging-related nutrition. Animal nutrition continues to be an important volume driver, particularly in feed premixes and livestock health formulations. Functional foods and beverages, along with cosmetic applications, represent smaller but increasingly differentiated demand pools that reward higher-purity, naturally sourced, or specialized forms of vitamin E.
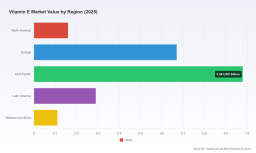
Regionally, the market is not uniform. Asia Pacific accounts for the largest absolute share of demand, reflecting scale in manufacturing, nutrition product formulation, and feed production. Europe and North America remain significant, with demand shaped by regulatory frameworks, premiumization trends, and specific labeling or sourcing requirements. Latin America and the Middle East/Africa contribute smaller shares but are noteworthy for localized growth dynamics and evolving formulation standards.
Three Structural Challenges Shaping the Near-Term Outlook
Despite the overall growth trajectory, the market faces several interrelated challenges that will influence pricing, availability, and competitive positioning.
Supply-tight conditions and origin diversification. Market intelligence from early 2026 indicates that vitamin E supply opened the period in a firm and supply-tight position, with constrained availability reported from both Chinese and non-Chinese origins. This tightness highlights the market’s sensitivity to capacity utilization, crop availability, and geopolitical or logistical disruptions. Companies that depend on a single sourcing corridor face heightened risk when availability narrows across multiple origins simultaneously.
Input cost volatility and raw material exposure. Vitamin E production remains closely linked to vegetable oil markets and related agricultural inputs. Seasonal variations, agricultural challenges, and geopolitical pressures contribute to production cost volatility, which can compress margins or force price adjustments downstream. In a market where pricing power varies by segment and customer type, cost volatility disproportionately affects producers and formulators with less flexible sourcing or limited ability to pass through price increases.
Regulatory and labeling complexity. Regulatory frameworks continue to shape product formulation and labeling practices, particularly in the dietary supplement and functional food segments. For example, the U.S. Food and Drug Administration has required manufacturers to use updated Nutrition Facts and Supplement Facts labels that list vitamin E in milligrams, with conversion rules from international units. While smaller manufacturers were given transition flexibility, the broader implication is clear: regulatory and labeling requirements add complexity to product development, compliance, and market access. This complexity favors companies with strong regulatory capabilities and standardized documentation, while raising the operational bar for smaller entrants.
Key Drivers Reshaping the Market
Technological Innovation and Formulation Capabilities
Innovation in vitamin E is increasingly less about basic product availability and more about differentiation through purity, stability, sourcing, and delivery format. High-purity grades, microencapsulated beadlets, and specialized excipient forms such as tocopherol polyethylene glycol succinate (TPGS) illustrate how formulation science is expanding the range of usable vitamin E applications. Microencapsulation, for instance, can improve stability and handling in food and nutraceutical matrices, while TPGS-based formats support solubility and bioavailability in pharmaceutical and supplement applications.
These technical capabilities matter commercially because they allow suppliers to serve higher-value use cases and create more defensible product positions. A supplier that can offer consistent particle size, reliable solubility, and documented efficacy claims is better positioned to support customer innovation in functional foods, premium supplements, and pharmaceutical-grade formulations. In practice, technical differentiation is becoming a key lever for pricing and customer stickiness, especially where end-products are marketed on quality, stability, or clean-label attributes.
Regulatory and Policy Environment
Regulation remains a defining force in how vitamin E is labeled, documented, and commercialized. Labeling changes that shift vitamin E disclosure from international units to milligrams are not just compliance exercises; they influence product positioning, consumer communication, and formulation decisions. Companies that navigate these changes effectively can reduce time-to-market friction and maintain clarity in consumer-facing claims.
Vitamin D Market
Beyond labeling, regulatory expectations around sourcing transparency, traceability, and quality documentation are increasingly relevant. Suppliers that can provide full traceability, consistent quality standards, and regulatory support are better positioned for markets where compliance is a gatekeeper to entry. This is especially true for natural, non-GMO, or food-grade product claims, where documentation and process control are central to customer confidence.
Demand-Side Shifts in Consumer and Business Behavior
On the demand side, several behavioral shifts are reshaping where and how vitamin E is used. In dietary supplements, consumers continue to seek antioxidant and immune-support benefits, but they are also paying more attention to ingredient origin, clean-label positioning, and perceived naturalness. This has elevated the relative appeal of natural vitamin E in certain premium segments, even as synthetic forms remain important where cost-efficiency and functional performance are the priority.
In animal nutrition, demand is tied to livestock productivity, feed efficiency, and health management strategies. Vitamin E’s role in oxidation prevention and animal health supports its continued use in feed premixes, but the segment is also sensitive to overall agricultural cycles, feed cost pressures, and regional production patterns.
Meanwhile, functional food and beverage applications are expanding where manufacturers can integrate vitamin E into delivery formats that preserve stability and sensory quality. Cosmetics and personal care applications similarly depend on formulation compatibility and perceived efficacy. Across these demand pools, the common thread is that customers increasingly select vitamin E not only for its nutritional function but also for how well it fits into the broader product architecture and brand story.
Supply Chain and Cost Structure Dynamics
Supply chain resilience is now a central strategic issue. Raw material volatility, seasonal crop dynamics, and geopolitical factors can affect both availability and pricing. In a market that is already supply-tight at times, the ability to manage sourcing risk becomes a competitive advantage. Companies with diversified origin exposure, flexible contract structures, and vertically integrated or closely coordinated supply chains are better equipped to maintain continuity of supply and manage margin pressure.
PW Consulting
At the same time, procurement practices are evolving. Digital procurement tools, more transparent ordering platforms, and improved supply chain visibility can reduce friction in ingredient purchasing. For example, new e-commerce and digital procurement initiatives in the ingredients sector are easing sourcing for U.S. buyers and signaling a broader shift toward more efficient, data-informed purchasing. This trend matters for vitamin E because it can improve accessibility, shorten procurement cycles, and increase price transparency across smaller and mid-sized buyers.
Competitive Landscape: Strategic Positioning and Market Evolution
Differentiating Strengths Among Core Players
The competitive landscape includes a mix of large, globally diversified suppliers and more specialized producers. Several strategic patterns stand out.
Natural-source differentiation. Companies with strong positions in natural vitamin E and mixed tocopherols are leveraging plant-based sourcing, clean-label compliance, and brand recognition to serve dietary supplement, functional food, and nutraceutical customers. For some of these players, natural sourcing is not just a product attribute but a broader positioning platform tied to efficacy, traceable origin, and consumer-friendly formulation narratives.
Scale, purity, and format breadth. Other major suppliers emphasize high-purity vitamin E across oil and powder formats, broad formulation support, and reliable production capability. Microencapsulated beadlets and backward-integrated production are examples of how scale suppliers create consistency and reliability for customers who need stable supply and standardized quality across large volumes.
Specialized sourcing and regulatory depth. One notable strategic position is held by a supplier that produces natural, non-GMO vitamin E from sunflower oil with patent-protected manufacturing and full traceability. This kind of positioning is especially valuable in markets where origin, non-GMO status, and regulatory documentation are critical purchase criteria. The ability to provide concentrated natural vitamin E with documented process control creates a defensible niche even in a market with multiple global players.
Pharmaceutical and excipient-focused capabilities. Some participants compete by focusing on pharmaceutical-grade vitamin E, specialized excipients, and GMP-certified manufacturing. This positions them closer to drug delivery and supplement formulation markets where quality standards, solubility support, and regulatory expertise matter more than pure commodity volume.
Geographic and application diversification. Producers in China and broader Asia, as well as processors linked to palm and other vegetable oil supply chains, add scale and optionality to the market. Their relevance often depends on the balance between synthetic and natural product lines, application focus, and ability to serve both food/feed and nutraceutical segments. Where integrated production and expanding capacity align with demand growth, these players can strengthen their role in global supply.
How the Competitive Field Is Evolving
The market is not consolidating into a single dominant structure. Instead, it is evolving along multiple axes. On one hand, scale players continue to invest in production reliability, format breadth, and formulation support to defend their position in high-volume segments. On the other hand, specialized suppliers are carving out defensible niches based on natural sourcing, non-GMO positioning, pharmaceutical-grade quality, or application-specific functionality.
A useful way to think about the landscape is that it is both consolidating and fragmenting at the same time. Consolidation pressure exists where customers seek consistent global supply, documented quality, and strong regulatory support. Fragmentation persists where specialized product attributes, regional sourcing preferences, and application-specific formulation needs create room for differentiated suppliers. This combination means that competitive advantage increasingly depends on matching the right product architecture to the right customer segment rather than simply competing on volume alone.
New entrants and platform-based procurement models also matter. Digital procurement and ingredient marketplaces can lower barriers for smaller buyers and increase visibility across suppliers. At the same time, they can intensify price comparability and shift some bargaining power toward buyers who can quickly evaluate multiple sourcing options. Suppliers that can combine reliability, documentation, and technical service with competitive pricing are better placed to retain customer relationships in this environment.
Outlook for 2026–2032: Emerging Trends and Commercial Implications
Trend 1: Continued Tightness in Supply and Greater Emphasis on Sourcing Strategy
Given the supply-tight positioning observed in early 2026, it is likely that availability and price stability will remain sensitive to crop outcomes, capacity utilization, and geopolitical or logistical disruptions over the next few years. This does not necessarily imply persistent shortages, but it does suggest that sourcing strategy will be a recurring strategic issue.
For commercial players, the implication is clear: supply resilience should be treated as a core capability rather than an operational afterthought. Companies that diversify origin exposure, maintain strategic inventory buffers where appropriate, and strengthen supplier relationships across multiple geographies will be better positioned to manage volatility. For buyers, this trend reinforces the value of long-term agreements, qualified alternative sources, and clear specifications that reduce the risk of reformulation disruption when availability tightens.
Trend 2: Growing Premiumization and Natural-Source Relevance in Selected Segments
Demand for natural vitamin E and mixed tocopherols is likely to remain especially relevant in dietary supplements and certain functional food and personal care applications, where ingredient origin and clean-label narratives carry commercial weight. Natural-source positioning will not replace synthetic vitamin E across all applications, but it will continue to command strategic importance in segments where brand positioning, consumer perception, and regulatory documentation support a premium.
This trend creates opportunities for suppliers that can deliver consistent natural-source quality, clear traceability, and strong formulation support. It also creates opportunities for brands that can align vitamin E sourcing with broader product claims around naturalness, transparency, and efficacy. At the same time, premiumization can increase sensitivity to raw material costs, so margin management and sourcing efficiency remain important even in higher-value segments.
Trend 3: Formulation Science and Specialized Applications as Growth Multipliers
A second important trend is the growing role of specialized formats and application-aligned product design. Microencapsulation, solubility-enhancing excipients, and pharmaceutical-grade quality standards are expanding the set of commercially viable vitamin E applications. These formats can support better stability, easier handling, and stronger efficacy storytelling, which in turn enable product innovation in supplements, functional foods, and pharmaceutical-adjacent markets.
For companies looking to capture growth, this trend suggests that product leadership will increasingly come from solving formulation and performance problems, not just supplying bulk ingredient volume. Suppliers and formulators that invest in application expertise, stability data, and customer co-development can create stronger commercial positions than those competing primarily on price in undifferentiated segments.
Risks and Uncertainties to Monitor
Several uncertainties could influence how these trends play out. Continued raw material volatility could pressure margins, particularly for producers with limited cost flexibility. Regulatory changes, including evolving labeling or documentation requirements, could increase compliance burdens and favor better-resourced players. Supply disruptions affecting either Chinese or non-Chinese origins could create periodic tightness that reshapes pricing and availability. In addition, competitive pressure from digital procurement and greater price transparency could compress margins in segments where differentiation is weaker.
A further uncertainty is demand responsiveness. If economic conditions or consumer spending patterns shift, discretionary supplement and premium functional food categories could experience slower growth, while animal nutrition and more essential feed applications may prove more stable. Companies should therefore avoid assuming uniform growth across applications and regions.
Strategic Recommendations for Decision-Makers
For Manufacturers and Ingredient Suppliers
First, invest in application-level differentiation rather than competing solely on volume and price. Formulators and suppliers can strengthen commercial positioning by expanding capabilities in high-purity grades, stabilized formats, and specialty excipients that solve specific customer problems. Technical service, stability performance, and regulatory support are increasingly part of the value proposition.
Second, build a sourcing strategy that reduces single-point dependency. Diversifying origin options, qualifying alternative suppliers, and maintaining flexible contract structures can help manage the risk of supply-tight periods. Where natural-source or non-GMO positioning is strategically important, ensure that traceability and documentation are robust enough to support customer claims and regulatory requirements.
Third, use formulation and stability expertise as a customer retention tool. In categories where product consistency and shelf life matter, suppliers that can help customers optimize performance in the final formulation are more likely to secure repeat business and co-development relationships.
Synthetic Vitamin E Market
For Investors
The vitamin E market offers a mix of steady demand and periodic supply volatility, which means that investment theses should account for both structural growth and operational resilience. Favorable exposure may be found in suppliers with diversified application portfolios, strong format breadth, and credible natural-source or pharmaceutical-grade positions. Companies with vertically integrated production, traceability capability, and demonstrated ability to manage raw material volatility are better positioned to defend margins through cycles.
Investors should also pay attention to where premiumization and formulation complexity are expanding value pools. Segments that reward specialized performance, documentation, and clean-label positioning may offer stronger differentiation than high-volume commodity-style segments. At the same time, due diligence should include sensitivity to input cost volatility, regulatory shifts, and the impact of digital procurement on pricing dynamics.
For Procurement and Commercial Teams
Procurement teams should treat vitamin E sourcing as a strategic risk-management function, not just a price-shopping exercise. Evaluating suppliers on the basis of origin diversity, quality documentation, supply reliability, and application support can reduce disruption risk and improve long-term outcomes. Where possible, dual or multi-origin qualification can provide a buffer when one supply corridor becomes constrained.
Commercial teams should also monitor how regulatory and labeling requirements affect customer needs. Clear documentation, consistent unit disclosure, and formulation alignment can reduce compliance friction for customers and strengthen supplier relationships. In practice, the more a supplier can help customers navigate labeling, quality, and formulation challenges, the more defensible its position becomes.
Conclusion
The vitamin E market is set to expand at a moderate pace through 2032, but the real strategic story lies in how supply resilience, regulatory complexity, formulation innovation, and demand-side premiumization interact. The sector is not defined by a single dominant theme; rather, it rewards participants that can align product capabilities with specific customer needs while managing the operational risks embedded in raw material volatility and supply tightness.
For manufacturers, the opportunity is to move up the value curve through format specialization, traceability, and application support. For investors, the opportunity lies in identifying players with resilient supply positions and credible differentiation in natural-source, pharmaceutical-grade, or application-specific segments. For procurement and commercial teams, the priority is to treat sourcing as a strategic capability that reduces disruption risk and improves long-term supplier alignment.
Given the range of interrelated factors shaping this market, decision-makers will benefit from more granular visibility into regional demand dynamics, application-level growth patterns, pricing behavior, and supplier-specific capability profiles. Detailed segmentation data and customized strategic assessment can help translate these market-level trends into company-specific action plans. For teams seeking a deeper, more targeted view of the vitamin E competitive landscape and forward opportunities, the full research report provides the additional detail needed to support planning, sourcing, and investment decisions.
For detailed analysis of this topic, please visit the official page: Vitamin E Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


