



Toilet Tank Fittings Market: Why Flush Valve Dominance & 7.5% CAGR Shift Next Decade

The Toilet Tank Fittings Market at an Inflection Point: Strategic Trends and Commercial Opportunities
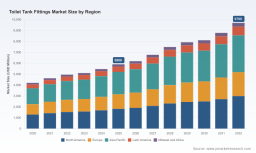
The toilet tank fittings market is undergoing a structural shift. What was once a commoditized segment of plumbing hardware is now shaped by tightening water efficiency mandates, rising material and energy costs, and evolving end-user expectations for reliability and water conservation. Between 2020 and 2025, the market expanded from approximately 4.2 billion USD to 5.9 billion USD, and the trajectory suggests continued growth through the early 2030s, with a compound annual growth rate of roughly 7.5 percent. By 2032, total revenue is projected to approach 9.7 billion USD. These figures point to a market that is scaling steadily, but the value creation is increasingly concentrated among players who can navigate regulation, supply chain volatility, and shifting application demand.
The growth story is not simply about volume. It reflects a re-pricing of performance, compliance, and serviceability. For executives, investors, and procurement leaders, the key question is no longer whether demand will expand, but where margins will be defended, which product architectures will win, and how quickly the competitive landscape will consolidate around differentiated capabilities.
Mapping the Current Market Landscape
The market today is characterized by a moderate level of concentration. The top three players account for about 55 percent of revenue, while the top five reach approximately 70 percent. This concentration indicates that scale, distribution breadth, and brand trust still matter, yet there is room for specialized entrants and regional winners to gain share through product fit, faster innovation cycles, or superior after-market support.
In terms of product architecture, flush valves and fill valves together form the core of the revenue base, with a residual share spread across complementary fittings and accessories. The application side remains anchored in residential demand, which continues to represent the largest share of volume, while hotels and commercial buildings contribute a meaningful but smaller portion of the total. Regionally, the market is broad-based, with significant footprints across North America, Europe, and Asia Pacific, alongside smaller but growing contributions from Latin America and the Middle East and Africa.
The strategic takeaway is that the market is large enough to support multiple winners, but not so fragmented that differentiation is optional. Leaders are already separating themselves through product availability, fit-for-purpose repair solutions, concealed system expertise, and supply chain reliability.
Core Challenges and Turning Points
Three challenges are reshaping how companies compete in this space.
- Regulatory stringency is raising the performance floor. Efficiency requirements are no longer isolated pilots. EPA WaterSense mandates high-performance, low-flow fittings in tank-type toilets with maximum full flush volumes of 1.6 gallons per flush, while California Title 20 standard requires tank-type dual-flush toilets manufactured on or after January 1, 2025 to limit full flush to 1.28 gallons per flush. These thresholds are compressing design freedom and rewarding manufacturers that can deliver consistent low-flow performance without sacrificing durability or user satisfaction.
- Input cost pressure is eroding the margin buffer. Recent pricing actions illustrate the sensitivity of the category to plastics and energy costs. Geberit implemented a 2 percent price increase on plastic piping and select products effective June 2026 to offset rising energy and plastics costs linked to geopolitical factors. This is not an isolated event; it signals that cost volatility is now a recurring theme, and companies that cannot pass through cost changes or redesign for material efficiency will face margin compression.
- Aftermarket and repair dynamics are becoming a strategic battleground. As original installations age and retrofit cycles accelerate, the ability to deliver universal repair kits, replacement flappers, fill valves, and flush components is increasingly important. A market that generates recurring demand from maintenance and replacement creates an opening for players with strong SKU coverage, clear compatibility mapping, and dependable availability.
Together, these forces are turning the market into a test of execution. Regulatory compliance is rewriting product specifications. Cost dynamics are exposing the limits of static pricing models. And the repair ecosystem is rewarding companies that can reduce friction for installers and homeowners alike.
Key Drivers Behind the Next Growth Cycle
Technology Innovation and Product Architecture
Innovation in toilet tank fittings is less about radical reinvention and more about precision engineering in service of water performance, durability, and ease of maintenance. Fill valves and flush valves are being refined to deliver reliable operation at lower flow rates, while minimizing noise, leakage, and installation complexity. The emphasis is shifting toward designs that maintain performance over a longer lifecycle, resist wear from frequent use, and simplify replacement in both new construction and retrofit scenarios.
Concealed tank systems are a notable example of where product architecture and installer preferences intersect. These systems can improve aesthetics and spatial efficiency in residential and commercial settings, but they also require informed replacement and service strategies. Players that publish updated parts and service documentation, and that maintain compatibility across common installations, gain an operational advantage. Geberit's release of a North America product and parts catalog in early 2026, focused on concealed tank systems and replacement flushing components, reflects the broader industry emphasis on making serviceable systems easier to specify and maintain.
From a strategic perspective, innovation that reduces total cost of ownership, improves fit across major toilet platforms, and aligns with efficiency mandates is more valuable than innovation that simply adds features. The winning designs are those that help customers meet compliance without introducing installation risk or user dissatisfaction.
Policy and Regulatory Environment
Regulation is now one of the strongest forces shaping product roadmaps and demand patterns. The EPA WaterSense framework and California Title 20 standard are not abstract guidelines; they directly influence what can be specified, purchased, and installed. As these requirements become embedded in procurement standards and building codes, manufacturers need to ensure that tank fittings and associated toilet systems meet flow thresholds consistently across product lines.
This regulatory environment has several implications. First, it rewards scale players and technically capable suppliers that can validate performance and provide assurance to specifiers and buyers. Second, it raises the importance of documentation, testing, and compatibility claims, especially where local authorities or large buyers require proof of compliance. Third, it can accelerate substitution toward designs that perform well at reduced flow rates, which may alter the relative attractiveness of different product segments over time.
Toilet Partitions Market
For commercial and hospitality end users, these regulations intersect with broader sustainability goals and operating cost pressures. Water efficiency is no longer just a compliance checkbox; it is an operating expense lever. That connection strengthens demand for fittings that deliver dependable low-flow performance and reduces the tolerance for products that fail to meet expectations over time.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, behavior is changing in ways that favor reliability, water savings, and efficient maintenance. In residential settings, homeowners and remodelers increasingly look for repair solutions that are easy to install, broadly compatible, and unlikely to require repeated service calls. This is especially relevant in older housing stock where toilet systems may be a frequent source of maintenance issues. The appeal of universal repair kits and straightforward replacement components remains strong because they reduce uncertainty and labor cost.
In hospitality and commercial buildings, procurement decisions are increasingly influenced by lifecycle considerations. Facility operators want fittings and flushing systems that reduce complaint volumes, simplify maintenance, and support sustainability reporting. The result is a slower but higher-value demand pattern: fewer impulse purchases, more specification-driven buying, and greater scrutiny of total performance rather than upfront price alone. This environment tends to reward brands that can demonstrate consistency, availability, and clear compatibility across common installation types.
One important nuance is that demand is not uniform. Residential replacement activity can be highly cyclical and sensitive to housing turnover, renovation spending, and regional repair cultures. Commercial and hospitality demand, by contrast, is more tied to occupancy, renovation cycles, and operational budgets. Understanding these differences is essential when planning product mix, inventory, and channel strategy.
Supply Chain and Cost Structure Dynamics
Supply chain dynamics are exerting pressure on both cost and service levels. Plastics, energy, and logistics inputs have become more variable, and geopolitical factors can quickly translate into pricing adjustments or availability constraints. The recent 2 percent price increase on plastic piping and select products by Geberit in June 2026 is a concrete illustration of how cost pressures are being managed at the product level.
Pipe Fittings Market
This environment is reshaping competitive advantage in several ways. Companies that can design for material efficiency, standardize across platforms, and manage bill-of-materials complexity are better positioned to absorb cost shocks. Those with stronger supplier relationships, flexible manufacturing footprints, and disciplined inventory practices can also protect service levels when demand spikes or input availability tightens. Conversely, players that rely on rigid cost structures or narrow supplier bases may be forced into reactive pricing moves that affect competitiveness.
The broader implication is that cost leadership in this market is increasingly about control over design, sourcing, and serviceability, not just manufacturing scale. The ability to balance compliance, durability, and material cost will determine which companies protect margins as the market expands.
Competitive Landscape and Leading Strategies
Positioning of Key Players
The competitive field includes companies with distinct value propositions, distribution strengths, and product philosophies.
- Fluidmaster has built a strong association with universal toilet tank fill valves, flappers, and complete repair kits for residential and commercial use. Its positioning centers on compatibility and breadth of repair solutions, which aligns well with the aftermarket and replacement demand that sustains much of the category.
- Korky manufactures universal toilet tank repair kits and components, including fill valves, flush valves, and flappers made in the USA. The emphasis on domestically produced components can be a differentiating point in segments where supply origin, quality consistency, and local availability matter to distributors and end users.
- Danco provides toilet tank repair kits with fill valves, flappers, and hardware for universal application across brands. Its approach reinforces the broad-compatibility model, supporting installers and consumers who need reliable fixes across a wide range of existing toilet platforms.
- Geberit offers concealed tank systems, flushing mechanisms, and replacement parts for residential and commercial installations. Its positioning is more oriented toward engineered systems and specification-driven environments, where performance, service documentation, and parts availability are central to long-term value.
These profiles show two complementary routes to competitiveness. One is the universal repair and replacement model that focuses on compatibility, SKU coverage, and immediate serviceability. The other is the engineered systems model that emphasizes concealed architectures, specification support, and durable replacement ecosystems. Both can win, but they require different operational capabilities and different go-to-market approaches.
Strategic Differentiation in Practice
Leading players are differentiating along several dimensions that matter to buyers and installers.
PW Consulting
- Compatibility and coverage. Broad fit across major toilet brands reduces friction in the aftermarket and increases the likelihood that a repair kit or replacement part will be the right solution the first time.
- Service documentation and parts availability. Updated catalogs and clear replacement pathways help specifiers, distributors, and maintenance teams act quickly. This is particularly important for concealed systems and commercial applications where downtime carries a higher cost.
- Performance under regulation. Products that consistently meet low-flow requirements while maintaining durability create trust with water-conscious buyers and compliance-sensitive procurement teams.
- Pricing discipline in a volatile cost environment. The ability to adjust pricing transparently, manage input cost exposure, and preserve product value is becoming a competitive signal in its own right.
The market is not simply rewarding the lowest price. It is rewarding predictability: predictable performance, predictable availability, and predictable total cost. That is a meaningful shift for a category that has historically competed heavily on convenience and replacement fit.
How the Landscape Is Evolving
Several trends are shaping the evolution of the competitive field.
- Moderate consolidation pressure. With top players already holding a substantial share, larger platforms may seek to expand through brand portfolios, distribution reach, or targeted acquisitions that add compatibility breadth or geographic coverage. At the same time, the existence of strong niche positions suggests that consolidation will be selective rather than blanket.
- Differentiation by application. Residential replacement remains a volume engine, but commercial and hospitality applications can support higher-value specifications and longer-cycle relationships. Companies that can serve both segments well, without diluting focus, are likely to capture a more resilient revenue base.
- New entrants and specialized challengers. The market still allows room for challengers that focus on specific product weaknesses, underserved compatibility gaps, or regional service advantages. Success for new entrants will depend on solving a clear pain point rather than competing broadly from day one.
- Increasing importance of service ecosystems. As concealed systems and more complex flushing mechanisms become more common in certain segments, the value of replacement parts, installation guidance, and support documentation will rise. Companies that treat service as part of the product proposition will be better positioned over time.
The overall direction is toward a market where breadth, compliance, and service reliability matter as much as the core mechanical function of the fitting. That creates opportunities for firms that can connect product performance with practical installation and maintenance outcomes.
Forward Trends and Commercial Implications
Trend One: Compliance-Driven Product Design Will Become Table Stakes
Over the next three to five years, low-flow performance and regulatory alignment will move from competitive advantage to baseline expectation. As standards are adopted more broadly and buyer expectations rise, product lines that cannot reliably meet efficiency requirements will face declining relevance in many specification and replacement contexts. The commercial opportunity lies in designing for compliance without sacrificing durability or ease of service, and in communicating performance clearly to specifiers and buyers. The risk is that companies treat regulation as a checkbox rather than a design constraint, which can lead to inconsistency, complaints, and slower adoption in higher-value segments.
Trend Two: Material Cost Volatility Will Reward Design and Sourcing Discipline
Cost pressure from plastics, energy, and logistics is likely to remain a recurring theme rather than a temporary disruption. Companies that can reduce material intensity, standardize components, and manage supplier exposure will be better positioned to protect margins and maintain pricing credibility. There is also an opportunity in redesigning products to use materials more efficiently while preserving performance. The downside risk is reactive pricing that erodes trust or slows demand, especially in price-sensitive residential replacement segments.
Trend Three: Aftermarket and Serviceability Will Gain Relative Importance
As installations age and retrofit activity continues, the market's recurring replacement layer will remain strategically important. Product lines that make repair faster, reduce compatibility uncertainty, and support clear part identification will benefit from repeat demand and stronger channel relationships. This is particularly relevant where concealed systems and commercial installations create higher stakes for downtime and maintenance efficiency. The opportunity is to treat the aftermarket as a design input, not an afterthought. The risk is underinvesting in SKU availability, documentation, or compatibility mapping, which can weaken a otherwise strong product portfolio.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
- Prioritize product architectures that meet current efficiency mandates while preserving durability and user satisfaction, especially in flush and fill valve designs.
- Strengthen compatibility mapping and repair kit coverage to reduce installation friction and capture recurring replacement demand.
- Build pricing and sourcing strategies that can respond to input cost volatility without undermining channel trust or demand stability.
- Treat service documentation and parts availability as part of the product value proposition, particularly for concealed systems and commercial applications.
For Investors and Strategic Buyers
- Look for companies with strong aftermarket relevance, broad compatibility, and demonstrated ability to manage compliance and cost complexity.
- Assess exposure to regulatory-driven demand shifts, especially where efficiency standards are expanding beyond early-adopter regions.
- Evaluate supply chain resilience and material efficiency as indicators of margin defense, not just operational hygiene.
- Recognize that value creation may come from better service ecosystems and documentation as much as from core product innovation.
For Procurement and Specification Teams
- Focus on total performance and lifecycle reliability, not just upfront unit price, especially in commercial and hospitality contexts.
- Verify compliance with current efficiency requirements and confirm compatibility before specifying fittings or repair solutions at scale.
- Favor suppliers that can provide clear documentation, dependable availability, and predictable replacement pathways to reduce maintenance risk.
The strategic stakes in the toilet tank fittings market are rising. Growth is supported by a large and diversified demand base, but the value is being reallocated toward players who can align product performance with regulation, cost reality, and service expectations. For decision makers, the most valuable insight is that the market reward system is shifting from convenience alone to predictable performance across compliance, maintenance, and cost. Detailed segment-level data, regional dynamics, and company-specific assessments can sharpen these choices further, and a full research report can provide the granularity needed to translate these trends into product plans, investment theses, and procurement strategies.
For detailed analysis of this topic, please visit the official page: Toilet Tank Fittings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


