



Oscilloscope Market 2032: How 6.95% CAGR and 72.3% CR3 Reshape Competition

Strategic Trends and Commercial Opportunities in the Oscilloscope Market
The oscilloscope market is undergoing a structural transformation driven by escalating signal complexity, the proliferation of high-speed digital architectures, and a widening gap between traditional benchtop instrumentation and software-defined measurement workflows. As electronic systems push into multi-gigabit bandwidth regimes and real-time diagnostics become embedded in product development cycles, oscilloscopes are evolving from standalone capture devices into integrated analysis platforms. This shift is reshaping demand patterns, competitive positioning, and investment priorities across the test and measurement ecosystem.
Market Overview and Core Challenges
Commercial Trajectory and Structural Dynamics
The global oscilloscope market has demonstrated steady expansion over the past half-decade, with revenue crossing 200 billion dollars in recent years and continuing its upward trajectory into the mid-twenties. The market's compounded annual growth rate of approximately 6.95 percent through the forecast horizon reflects a maturing yet still expanding category, where incremental adoption is increasingly tied to advanced capability upgrades rather than base-level replacement. Revenue distribution across form factors reveals a dominant benchtop foundation, complemented by a rapidly growing portable segment and a substantial PC-based footprint that underscores the industry's pivot toward software-centric workflows. Bandwidth segmentation highlights a concentration of demand in the mid-range spectrum, while the sub-500 MHz tier remains a steady volume driver for general-purpose applications. Higher bandwidth categories, particularly those exceeding 4 GHz, represent a smaller but strategically critical slice tied to high-speed digital design, signal integrity validation, and next-generation communication testing. Industry-level demand spreads across automotive and transportation, IT and telecommunications, consumer electronics, aerospace and defense, medical and life sciences, and a diversified remainder, reflecting the instrument's cross-sector relevance.
The market is characterized by pronounced concentration, with a small group of established players commanding a substantial share of global revenue. This consolidated structure has historically reinforced premium pricing, long product lifecycles, and deep application-specific support. However, the same concentration also creates pressure points as demand fragments across more diverse testing scenarios and price-sensitive segments expand in emerging manufacturing hubs.
Key Challenges and Inflection Points
The industry faces several intertwined challenges that are redefining how manufacturers, buyers, and investors evaluate opportunity. First, the boundary between hardware performance and software capability is blurring. Advanced waveform analysis, automated compliance testing, and AI-assisted interpretation are becoming differentiators that matter as much as raw bandwidth or sampling rate. Companies that continue to compete primarily on analog specifications risk ceding ground to platforms that deliver faster time-to-insight and tighter integration with design environments.
Second, supply chain and component availability for high-performance analog front-ends, precision clocks, and high-speed digitizers remain sensitive to geopolitical and semiconductor cycle dynamics. Leading manufacturers are navigating longer validation cycles and elevated lead times for critical subsystems, which affects time-to-market for next-generation series and complicates capacity planning in high-growth regions.
Third, the purchasing behavior of engineering teams is shifting. Design organizations increasingly favor instruments that support bench-to-field workflows, remote collaboration, and seamless data export into simulation and verification tools. This demand-side evolution is pressuring incumbents to rethink channel strategies, service models, and the balance between entry-level volume products and high-margin specialized systems.
Key Demand Drivers
Technology Innovation and Capability Gaps
The most consequential driver is the accelerating pace of signal complexity in modern electronic architectures. High-speed serial links, advanced packaging, RF-intensive designs, and mixed-signal integration are pushing test requirements beyond traditional capture capabilities. In this environment, oscilloscopes are being asked to deliver higher waveform capture rates, deeper memory, lower noise floors, and more sophisticated analysis libraries. The recent emphasis on real-time instruments tailored for high-speed digital and compliance testing illustrates how vendors are aligning product roadmaps with these technical demands. Simultaneously, the introduction of compact mixed-signal platforms designed for seamless bench-to-field workflows signals a broader push toward portability, multi-channel flexibility, and field-deployable diagnostics without sacrificing analytical depth.
A second technology-related driver is the integration of intelligent analysis features. Automation of measurements, pattern recognition, and guided troubleshooting are reducing the dependency on highly specialized operators and enabling faster iteration in development cycles. This trend is particularly relevant for teams working on 5G-related validation, quantum computing instrumentation, and advanced signal integrity applications, where the volume and complexity of captured data make manual interpretation impractical.
PW Consulting
Policy and Regulatory Environment
Regulatory and compliance requirements are shaping demand in subtle but persistent ways. Automotive safety standards, emissions testing mandates, and industry-specific certification frameworks are expanding the scope of required validation, especially in sectors where electronic control units, power Electronics, and communication modules must meet rigorous performance thresholds. In aerospace and defense, traceability, measurement confidence, and long-term supportability continue to favor established instrumentation with documented calibration and verification pathways. These requirements create a steady baseline of demand for compliant, well-supported platforms, while also raising the barrier for new entrants that lack institutional credibility or comprehensive service networks.
Demand-Side Shifts in Engineering and Manufacturing
Engineering organizations are under increasing pressure to shorten design cycles and reduce rework. The adoption of mixed-signal architectures, broader use of embedded sensors, and tighter integration between hardware and software teams are driving demand for instruments that can support multiple use cases without requiring separate toolchains. Portable and PC-based formats are gaining relevance in environments where measurements must be taken outside traditional lab settings, including field commissioning, production line debugging, and remote diagnostics. At the same time, larger enterprises are prioritizing platforms that connect to enterprise data workflows, enabling measurement results to feed directly into quality systems, design reviews, and compliance documentation.
Supply Chain and Cost Structure Evolution
Cost dynamics are increasingly influenced by the balance between performance differentiation and affordability. In entry-level and mid-range segments, competitive pressure is intensifying as manufacturers expand feature sets that were once reserved for higher tiers. This compression is prompting a recalibration of pricing strategies and encouraging a segmentation approach in which value is created through application-specific bundles, software subscriptions, and support services rather than hardware alone. On the supply side, the need for high-quality analog components and precision fabrication continues to favor scaled manufacturers with strong procurement relationships and multi-sourced component strategies. Companies that can maintain stable production while introducing differentiated analysis capabilities are better positioned to protect margins in a more crowded competitive field.
Competitive Landscape and Leading Strategies
Strategic Positioning of Core Players
The competitive environment is shaped by a mix of established multinational manufacturers and focused regional players, each pursuing distinct value propositions. One U.S.-based leader has built a strong identity around high-performance oscilloscopes for high-speed digital, 5G, and quantum computing applications, reinforced by AI-assisted analysis capabilities. Its recent launch of a real-time oscilloscope series targeting high-speed digital and compliance testing demonstrates a strategy centered on pushing the performance envelope while embedding smarter interpretation tools. The emphasis on advanced compliance workflows indicates a deliberate move toward use cases where measurement accuracy, repeatability, and regulatory alignment carry substantial commercial weight.
A second U.S. incumbent is widely recognized for digital phosphor and mixed-signal oscilloscopes that extend into high-frequency ranges with advanced waveform analysis. Its introduction of a mixed-signal oscilloscope designed for bench-to-field workflows reflects an effort to bridge laboratory precision with field usability, a positioning that appeals to engineering teams seeking continuity across development, validation, and deployment environments. This approach underscores a broader strategic theme: reducing friction in measurement workflows rather than competing solely on specification sheets.
A German manufacturer has carved out a strong position with compact and entry-level oscilloscopes offering multiple channels and high waveform capture rates, particularly in general and automotive testing. Its focus on accessible multi-channel configurations suggests a strategy aimed at capturing volume in sectors where testing throughput and channel density are critical, while still maintaining a credible presence in performance-oriented applications. A U.S. specialist remains closely associated with high-bandwidth sampling oscilloscopes for signal integrity and high-speed testing, a niche that rewards deep domain expertise and application-specific optimization. A Japanese measurement company continues to emphasize precision test and measurement oscilloscopes for industrial and engineering applications, leveraging a reputation for reliability and long-tail support.
On the other side of the competitive spectrum, Chinese manufacturers are expanding their footprint in affordable digital oscilloscopes for bench and educational use, as well as high-resolution instruments for high-speed signal integrity testing. Their growth is closely tied to price competitiveness, feature densification at lower price points, and growing acceptance in cost-sensitive markets and training environments. A UK-based provider has focused on USB-based oscilloscopes for portable and PC-integrated signal capture, an approach that aligns with the broaderPC-based and portable momentum and serves users who prioritize integration simplicity and flexibility over standalone instrument form factors.
Market Evolution and Competitive Dynamics
Several structural dynamics are influencing how the competitive landscape is evolving. One is the tension between consolidation and segmentation. While the market remains concentrated at the top, demand is fragmenting across more application-specific requirements, form factors, and price points. This creates space for both specialized leaders and agile challengers, depending on the segment. High-performance and compliance-driven segments tend to reward established credibility and deep support ecosystems, while entry-level and mid-range segments are more contested and sensitive to feature-to-price ratios.
Multimeters Market
Another dynamic is the growing importance of software and services as sources of differentiation. As measurement workflows become more connected and analysis more automated, the value of an instrument increasingly depends on how well it fits into the broader engineering environment. Product launches that emphasize workflow continuity, advanced capture rates, and intelligent analysis suggest that leading manufacturers recognize software-defined value as a durable competitive advantage. At the same time, new entrants and regional players are using affordability and targeted feature sets to gain traction, particularly where procurement budgets and training needs prioritize accessible, versatile tools.
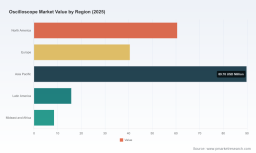
A third dynamic is geographic diversification of demand and supply. While mature markets continue to anchor high-value deployments, growth in Asia Pacific and other developing regions is expanding the addressable base for both premium and cost-effective instruments. This geographic spread is encouraging manufacturers to adapt product portfolios, service coverage, and channel strategies to local engineering practices and procurement norms.
Future Outlook for 2026–2032
Trend 1: Software-Defined Measurement and Intelligent Analysis Become Table Stakes
Over the next several years, the differentiator set for oscilloscopes will increasingly favor platforms that combine strong hardware foundations with software capabilities that accelerate interpretation and decision-making. AI-assisted analysis, automated compliance routines, and deeper integration with simulation, documentation, and quality systems are likely to become more standard across mid-range and high-end offerings. This trend opens commercial opportunities for vendors that can package analysis workflows as repeatable, auditable processes, and for buyers who can reduce engineering cycle time through better measurement-to-insight pathways. The risk is that software expectations rise faster than hardware roadmaps, creating mismatch risk for products that advertise intelligence without corresponding workflow maturity or data interoperability.
Trend 2: High-Speed Digital, Signal Integrity, and Compliance-Driven Demand Will Keep Pulling the High-End Forward
Demand for higher bandwidth, deeper capture, and more precise signal integrity validation is expected to remain a primary engine of premium segment growth. Applications in high-speed digital design, advanced communication testing, and specialized research environments will continue to reward instruments that can handle complex waveforms with low noise and high repeatability. Commercial opportunity here lies in bundled solutions that pair high-performance hardware with application-specific libraries, calibration support, and compliance-oriented documentation. The uncertainty is that the high-end pipeline is sensitive to component availability and validation timelines, which can cause uneven release cadences and temporary gaps between market demand and available capacity.
Trend 3: Form Factor Diversification Will Broaden the Addressable Use Case Set
Portable and PC-based oscilloscope formats are likely to continue gaining relevance as measurement moves beyond the lab and into field, production, and remote settings. Benchtop systems will remain central for high-performance and complex multi-channel work, but the broader market will increasingly value instruments that adapt to varied environments without sacrificing analytical rigor. This creates opportunities for manufacturers that can deliver flexible channel configurations, robust portability, and easy integration with PCs and enterprise tools. The risk is that form factor proliferation complicates product management and service coverage, especially for organizations trying to serve both centralized labs and distributed engineering teams with a unified portfolio.
Dermatoscope Market
Strategic Implications for Decision Makers
For Manufacturers and Product Leaders
Balancing performance leadership with workflow usability will be essential. Investing in analysis software, automated measurement packages, and seamless data export can strengthen stickiness and justify premium positioning, especially in high-speed digital, compliance, and signal integrity markets. At the same time, manufacturers should monitor the entry-level and mid-range segments closely, where feature densification and competitive pricing are reshaping buyer expectations. A clear segmentation strategy, supported by disciplined component sourcing and predictable release cycles, can help protect margins while preserving access to growth regions and application verticals.
For Investors and Strategic Allocators
The most durable value creation in this market is likely to come from businesses that combine credible hardware performance with software-enabled differentiation and strong service ecosystems. Investors should pay attention to product launch cadences that demonstrate alignment with high-growth use cases, as well as to the ability of incumbents and challengers to sustain margin discipline amid rising software expectations and supply chain sensitivity. Companies that can expand recurring value through software, support, and application bundles may offer more resilient growth profiles than those relying primarily on hardware replacement cycles.
For Procurement and Engineering Leaders
Buying decisions should increasingly reflect total measurement workflow value rather than headline specifications alone. Priorities may include waveform capture rates, analysis automation, multi-channel flexibility, portability where field use matters, and integration with existing design and quality systems. Procurement teams should also evaluate long-term supportability, calibration pathways, and the availability of application-specific guidance, particularly in regulated or high-stakes environments. For organizations operating across multiple sites or engineering contexts, instruments that support consistent workflows from bench to field can reduce training overhead and improve measurement continuity.
Closing Perspective
The oscilloscope market is moving from a specification-centric competition model toward a workflow- and analysis-centric one. Growth is being shaped by higher signal complexity, expanding compliance demands, and the need for measurement tools that fit into broader engineering environments rather than standing apart from them. The commercial opportunity lies in aligning product strategy with these realities: delivering high-performance capability where it matters, embedding intelligent analysis where it accelerates decisions, and offering flexible form factors where measurement must travel beyond the lab. For organizations seeking to navigate this landscape with greater precision, a deeper dive into segment-level demand patterns, regional procurement shifts, and competitive release roadmaps can provide the granularity needed to de-risk planning and prioritize the most valuable opportunities.
For detailed analysis of this topic, please visit the official page: Oscilloscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


