



Isononanoic Acid Market: Why the 5.2% CAGR to $318M by 2032 Changes Everything

Strategic Trends and Commercial Opportunities in the Isononanoic Acid Market
The isononanoic acid market is entering a period of structural transformation where traditional supply chain assumptions no longer hold and value capture is shifting toward companies that can align feedstock strategy, regulatory compliance, and application advantage. Valued at approximately 175.0 million USD in 2020, the market expanded to roughly 220.0 million USD by 2025, and forward indicators point to a trajectory of 318.0 million USD by 2032. This progression corresponds to a compound annual growth rate of 5.2 percent, but the meaning of that growth lies less in the headline number than in the composition of demand, the geography of consumption, and the pricing power embedded in specialized grades. For executives and investors, the central question is not whether the market will expand, but where margins will be earned and which capabilities will allow firms to participate safely in a more volatile, regulation-driven environment.
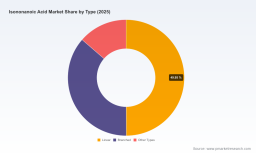
The wide base of consumption across plastics, lubricants, coatings, metalworking fluids, and specialty intermediates means that isononoic acid benefits from diversified end-use pull. However, this diversification also creates uneven exposure to macro cycles. Linear and branched variants serve different performance profiles and price sensitivity levels, while regional consumption patterns reflect both industrial maturity and local regulatory pace. At the current stage, the market is neither a commodity slugfest nor a niche specialty segment; it is a performance chemical space where feedstock access, grade purity, and formulation partnerships determine which players can convert volume growth into durable profitability.
Market Snapshot
The historical arc from 2020 through 2025 shows steady expansion with a notable mid-cycle adjustment in 2024 before a rebound in 2025. That pattern is consistent with a market absorbing raw material swings, inventory recalibrations, and shifting demand mix across industrial customers. Looking ahead, the forecast window to 2032 suggests continued expansion, with the largest absolute gains accumulating toward the late part of the period as replacement demand matures and new formulations in lubricants and polymer systems reach broader adoption.
What matters strategically is that the growth path is not uniform across applications or regions. Demand is being shaped by substitution away from legacy environments, the performance requirements of engineered fluids, and the ongoing push toward lower-emission formulations. Companies that can translate these shifts into captive grade development, reliable logistics, and application-specific technical service are positioned to earn a premium relative to pure volume players.
Core Challenges and Inflection Points
The first inflection point is regulatory substitution. Legacy phthalates have been drawn into heightened scrutiny under frameworks such as EU REACH, accelerating the use of non-phthalate alternatives in flexible PVC compounding and lubricants. Isononanoic acid-based chemistry is benefiting from this structural shift, but substitution is not instantaneous. Formulators must qualify new systems, manage performance trade-offs, and secure supply consistency. For producers, the opportunity is real but dependent on technical support and qualification timelines rather than simple price competition.
Worldwide Isononanoyl Chloride Market
The second inflection point is feedstock and pricing volatility. Isononanoic acid production relies on C9 alcohol intermediates derived from propylene oligomerization or Fischer-Tropsch feedstocks, and volatility in n-butene and propylene prices directly affects supply chains. Upstream C5 hydrocarbon isopentane prices have held relatively steady in select regional markets as of April 2025, but that stability is not guaranteed to persist across all geographies or time horizons. The result is a market where cost structures are sensitive to both petrochemical cycles and localized supply conditions. Businesses that rely on spot procurement without hedging strategy or long-term alignment are exposed to margin erosion during transition periods.
The third inflection point is the regulatory push on blowing agents and emissions. Mandates around high-GWP hydrofluorocarbon blowing agents are driving migration toward hydrocarbon-based isopentane co-feedstocks for downstream ester production, while low-VOC directives in Europe and analogous North American regulations are accelerating demand for lower-emission alkyd resins and coatings that incorporate isononanoic acid monomers. Together, these dynamics are reshaping end-use priorities and rewarding producers and distributors who can provide compliant grades and formulation support. The challenge is execution: compliance is not only a documentation exercise but a product development and supply assurance commitment.
Key Drivers Shaping the Market
Technical Innovation Across Grades and Applications
Differentiation in this market increasingly depends on grade design and application fit. Linear forms remain central where consistent performance and broader compatibility are required, while branched variants address specific rheological, solvency, or stability needs. High-purity grades have become especially relevant for refrigeration lubricants and engineered fluids, where impurity control affects system reliability and service life. Producers investing in specialized carboxylic acid portfolios and dedicated capacity for performance grades are better positioned to serve customers that require consistent specifications and repeatable batches rather than standard commodity output.
Innovation is also showing up in how grades are integrated into downstream systems. In lubricant applications, isononoic acid supports polyol ester synthetic lubricants and functional fluids that demand thermal stability and compatibility with advanced base stocks. In coatings and alkyd systems, the monomer's role in low-emission formulations aligns with regulatory momentum and customer preference for reduced VOC profiles. The commercial implication is that technical service, grade selection guidance, and application testing are becoming value drivers alongside volume supply.
PW Consulting Chemical & Energy Research Center
Policy and Regulatory Environment as a Structural Tailwind
Regulation is no longer a peripheral risk factor; it is a central driver of substitution and product design. EU REACH's classification of legacy phthalates as substances of very high concern has accelerated replacement by isononanoic acid-based alternatives in flexible PVC and lubricants. Parallel developments in the United States and other jurisdictions have mandated the phase-out of high-GWP blowing agents, encouraging migration to hydrocarbon-based co-feedstocks that tie into downstream ester chemistry. European VOC directives and North American low-VOC requirements are further expanding demand for low-emission alkyd resins and coatings that incorporate isononoic acid monomers.
In parallel, sustainability certification is influencing procurement choices. ISCC PLUS requirements for bio-based content are encouraging manufacturers to invest in circular and bio-based pathways within carboxylic acid supply chains. This is not a short-lived trend; it reflects a wider shift toward verifiable feedstock provenance and reduced lifecycle impact. Companies that can supply certified content or document circularity attributes are likely to gain preference in customer qualification processes, particularly where brand owners and OEMs face their own sustainability commitments.
Isononyl Alcohol Market
Demand-Side Shifts in Lubricants, Coatings, and Engineered Fluids
On the demand side, the most consequential change is the redefinition of performance expectations across multiple end-use categories. Synthetic lubricants and refrigeration lubricants require fluids that maintain stability under demanding operating conditions, and high-purity isononoic acid is a building block in those systems. At the same time, coatings formulators are under pressure to reduce emissions without sacrificing durability or application performance, which creates demand for monomers and intermediates that support lower-VOC architectures. In personal care intermediates and metalworking fluids, the value is more application-specific, but it is still shaped by the same themes: regulatory compliance, performance consistency, and supply reliability.
These demand-side changes reward suppliers that can act as formulation partners rather than passive distributors. When end users are adapting to new regulatory constraints and performance targets, they look for suppliers who can provide sample support, specification guidance, and dependable delivery. This dynamic strengthens the position of firms with technical capability and application focus, particularly in regions where industrial customers are undergoing rapid reformulation.
Supply Chain and Cost Structure Realignment
Feedstock linkage to propylene and n-butene markets means that isononoic acid supply chains are exposed to upstream price swings. Recent dynamics underscore the sensitivity of cost structures to both commodity movements and geopolitical disruption. Following the Middle East conflict, Perstorp Oxo AB implemented a global price increase effective March 1, 2026, citing sharply increasing raw material and energy prices, and then implemented a further increase effective April 1, 2026, reflecting supply and demand balance changes. These steps illustrate how quickly cost conditions can shift and how pricing power is being reasserted in a tight environment.
At the same time, regional feedstock conditions are not identical. The relative steadiness of isopentane pricing in certain Chinese markets as of April 2025 suggests that local balances can diverge from broader petrochemical trends. For procurement and planning teams, the lesson is that regional sourcing logic, inventory strategy, and contractual flexibility matter more than generic assumptions about cost trends. Businesses that build multi-source options and anticipate lead-time variability are better placed to manage volatility without sacrificing service levels.
Competitive Landscape and Leading Strategies
Incumbent Producers and Differentiated Positioning
BASF SE operates a global carboxylic acids portfolio with production footprint including Germany and Malaysia, supporting applications such as polyol ester synthetic lubricants, paint dryers, and metal salts. Its advantage lies in scale, portfolio breadth, and the ability to serve multiple downstream markets with integrated chemical capabilities. For customers seeking broad availability and a supplier with strong application reach, BASF represents a strategic anchor in the value chain.
OXEA GmbH is a dedicated manufacturer of isononoic acid and related grades, with focus on synthetic lubricants, corrosion inhibitors, functional fluids, and polymer stabilizers. This specialization supports consistent grade control and application alignment, which is valuable where formulators need repeatable purity and specification stability. In a market where performance differentiation increasingly matters, dedicated producers can command stronger commercial positioning by offering predictable quality and focused technical support.
Perstorp Oxo AB supplies isononoic acid for refrigeration lubricants and engineered fluids, with emphasis on high-purity grades and complete building block portfolios. Its positioning is particularly relevant where thermal stability and purity requirements are stringent. The recent pricing actions taken in 2026 reflect not only cost pressure but also the strategic use of pricing to manage supply-demand balance in a constrained environment. This approach underscores the importance of proactive supply planning for customers reliant on high-purity inputs.
KH Neochem Co., Ltd. provides isononoic acid under the KYOWANOIC-N trade name, with industrial applications spanning lubricants, coatings, and personal care intermediates. Its role illustrates the importance of branded, application-anchored supply in markets where buyers value traceability and consistent quality. Neuchem, as a North American distributor and supplier with long-standing exclusive supplier relationships, supports lubricants, metalworking fluids, and chemical processing through flexible packaging options ranging from drums to bulk. Its model shows how distribution depth and logistics flexibility can create value in regional markets where service reliability is as important as product availability.
Univar Solutions and Parchem Fine & Specialty Chemicals operate as active distributors of technical-grade material for synthetic lubricants, corrosion inhibitors, alkyd resins, and coatings. Their presence broadens access to isononoic acid across multiple applications and geographies, but it also highlights a structural reality in the market: distribution capability and application knowledge can be as important as production scale. For many buyers, the choice of channel depends on required grade, lead time, technical support, and the ability to integrate supply into broader formulation workflows.
Market Structure and Evolving Dynamics
Concentration remains moderate, with a significant share held by a limited number of leading producers and distributors. This creates a landscape where scale and portfolio depth matter, but where specialization, grade control, and regional service also determine commercial success. The market is not consolidating into a single dominance pattern; rather, it is evolving into a segmented structure in which different players lead in different application niches and geographies.
Several forces are likely to shape the next phase of competitive dynamics. First, the continued push toward certified and renewable feedstocks may favor producers that can document sustainability attributes and secure bio-based or circular inputs. Second, regulatory substitution will elevate the importance of application-specific grades, benefiting firms that can support qualification and scale-up with customers. Third, volatility in feedstocks and energy will test the resilience of cost structures, rewarding those with flexible procurement strategies and strong supplier relationships. In this environment, new entrants will find the greatest traction where they can credibly address a specific application need or regional service gap rather than compete broadly on price alone.
Future Trends and Commercial Opportunities
Acceleration of Non-Phthalate and Low-Emission Formulations
Over the next three to five years, substitution trends are likely to deepen as regulatory frameworks mature and end-user qualification cycles advance. The movement away from legacy phthalates and toward lower-VOC coatings and alkyd resins supports ongoing demand for isononoic acid-based building blocks. The commercial opportunity lies in capturing formulation partnerships early, offering grade options that meet evolving requirements, and providing documentation that simplifies customer compliance. Producers and distributors that invest in technical service and qualification support will be better positioned to convert regulatory momentum into repeat business.
The related risk is that substitution speed can vary by sector and geography. In some markets, legacy systems persist due to cost constraints, performance concerns, or slow qualification. Businesses should therefore plan for a phased transition rather than assuming immediate adoption across all applications.
Feedstock Strategy and Pricing Discipline as Margin Defenders
Given the dependence on propylene-related intermediates and the demonstrated exposure to energy and raw material shocks, feedstock strategy will remain central to profitability. Companies that secure reliable intermediate supply, maintain contractual flexibility, and align inventory policy with demand variability will be better able to protect margins during volatile periods. The recent pricing actions in early 2026 also suggest that pricing discipline can be exercised when supply-demand balance tightens, but only if customers perceive risk and reliability as worth paying for.
The opportunity here is twofold. For producers, stronger feedstock alignment and cost discipline can support better margin control and more predictable commercial terms. For buyers, diversifying sources and planning for lead-time variability can reduce exposure to abrupt price changes and availability disruptions. The risk is that any over-reliance on single-source supply or rigid procurement models increases vulnerability to upstream shocks.
Growth Concentrated in Specialized Grades and Certified Content
Expansion to 2032 is likely to be supported not by uniform volume growth across all forms, but by concentration in higher-value grades and applications where performance and compliance create willingness to pay. High-purity grades for refrigeration and engineered fluids, non-phthalate alternatives for flexible PVC and lubricants, and low-emission coating inputs all represent areas where value addition can outpace commodity inflation. In parallel, demand for verified bio-based or circular content may increasingly influence procurement decisions, particularly where downstream brands require sustainability documentation.
The strategic opportunity is to align product development and supply assurance with these premium segments. Businesses that can deliver consistent purity, certification readiness, and application support will be more resilient to price competition in commodity segments. The uncertainty lies in the pace of certification adoption and the degree to which sustainability attributes translate into purchasing preference across all regions and customer segments.
Actionable Guidance for Decision-Makers
For Manufacturers and Formulators
Prioritize grade selection based on application performance and regulatory fit rather than treating isononoic acid as a generic input. Where reformulation is underway, invest in early technical engagement with suppliers to reduce qualification time and avoid performance surprises. Build supply arrangements that combine reliability with flexibility, and consider multi-source strategies where feedstock or logistics risk is elevated. If sustainability documentation is increasingly required by your customers, evaluate sourcing options that support certification or traceability claims without disrupting production continuity.
For Investors
Focus on the segments where premiumization and substitution are most evident: high-purity engineered fluid inputs, non-phthalate replacements, and low-emission coating-related monomers. Evaluate companies and supply chains based on feedstock resilience, grade differentiation, and the ability to support customer qualification. Be attentive to the implications of regional feedstock volatility and energy cost exposure, since these factors can affect margin stability even when demand trends are favorable. Where possible, favor businesses with demonstrated technical service capability, as that capability often underpins pricing power in performance chemical markets.
For Procurement and Supply Chain Leaders
Treat feedstock-linked volatility as a planning variable rather than an exceptional event. Incorporate lead-time variability, regional pricing divergence, and regulatory-driven demand shifts into inventory and contract strategy. Where dependence on high-purity or certified grades is significant, secure visibility into supplier capacity, packaging options, and documentation processes. A diversified sourcing approach, combined with clear specification requirements and service-level expectations, can reduce the operational impact of market disruptions while maintaining access to the grades most relevant to your applications.
The strategic value of timely, granular intelligence in this market lies in understanding how substitution pace, feedstock conditions, and regional regulation interact to shape both opportunity and risk. Detailed segmentation data, regional pricing dynamics, and application-specific demand shifts can materially improve planning accuracy and commercial execution. For decision-makers seeking deeper insight into market size breakdowns, regional trajectories, and customized recommendations aligned to specific business models, the complete PW Consulting research report offers expanded coverage and tailored analysis to support more precise strategic choices.
For detailed analysis of this topic, please visit the official page: Isononanoic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


