



Optical Fiber Fusion Splicer Market: 6% CAGR Signals Shift to Asia Pacific

The Optical Fiber Fusion Splicer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
Market Trajectory and Scale
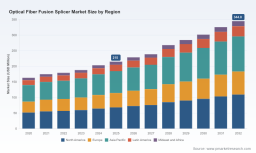
The optical fiber fusion splicer market has demonstrated consistent expansion over the past five years, reflecting the broader acceleration of fiber-optic infrastructure deployment worldwide. Revenue grew from approximately $163.15 million in 2020 to an estimated $215.0 million in 2025, representing a compound annual growth rate of roughly 6.0 percent over the historical period. This trajectory is expected to continue through the forecast horizon, with market revenue projected to reach $344.8 million by 2032. The steady upward path is underpinned by long-term capital expenditure commitments in telecommunications networks, data center interconnections, and industrial connectivity applications, all of which rely on precision fiber joining to maintain signal integrity and network reliability.
While the headline growth rate appears moderate, it masks important structural dynamics beneath the surface. The market is not expanding uniformly across all product categories or end-use segments. Single-fiber fusion splicers continue to dominate revenue contribution, reflecting their entrenched role in telecom backbone builds, premises networking, and field repair operations. Ribbon and other specialized splicer formats occupy a smaller but strategically important position, catering to high-density fiber routing scenarios where throughput and port density justify higher unit costs. This balance between volume-driven single-fiber demand and niche high-performance segments creates a dual-track revenue structure that rewards manufacturers capable of serving both mainstream and specialized deployment profiles.
Key Challenges and Inflection Points
Despite the favorable growth backdrop, the industry faces several structural challenges that are reshaping competitive priorities and investment decisions.
- Margin pressure from commoditization in mainstream segments: As single-fiber fusion splicers mature into standardized field tools, price transparency increases and differentiation narrows. Manufacturers that compete primarily on baseline functionality risk margin erosion unless they can bundle software, service, or operational efficiency gains that justify premium positioning.
- Technician skill gaps and deployment complexity: Fiber network densification, particularly in data center interlinks and rural broadband rollouts, places higher demands on installation speed and first-pass yield. Splicer platforms that require extensive manual calibration or steep operator training can become bottlenecks in labor-constrained markets, pushing buyers toward more automated or guided workflows.
- Regulatory and procurement fragmentation: Government and institutional purchasing processes introduce additional complexity. Classification decisions, standards recognition, and formal sourcing inquiries can accelerate or delay demand depending on how clearly equipment fits into approved procurement pathways. This fragmentation creates uneven demand signals across regions and customer segments, requiring suppliers to maintain flexible go-to-market strategies rather than relying on a single channel or geography.
These challenges are not purely defensive issues; they also define where value is shifting. Companies that reduce operator dependency, streamline field workflows, and align product positioning with procurement realities are better placed to convert market growth into durable share gains.
Key Drivers Shaping Market Dynamics
Technology Innovation and Workflow Automation
The most consequential driver in the optical fiber fusion splicer market is the shift from standalone hardware tools to integrated splicing platforms that reduce human intervention and improve repeatability. Recent product introductions illustrate this direction clearly. In May 2026, AFL Telecommunications LLC launched the Fujikura 100R Mass Fusion Splicer featuring Auto Placement Correction, a capability designed to detect fiber alignment automatically and reduce the need for manual operator adjustment. This type of functionality matters commercially because it shortens installation time, lowers the risk of costly rework, and makes high-volume splicing operations more predictable in field and central office environments.
The broader technology trend extends beyond alignment assistance. Splicer manufacturers are increasingly integrating cloud connectivity, diagnostic feedback, and maintenance-oriented features that support fleet management and remote troubleshooting. For telecom operators and enterprise network teams, these capabilities translate into better asset utilization and faster mean-time-to-repair. For manufacturers, they open recurring value streams through service contracts, software-enhanced features, and lifecycle support rather than relying solely on unit sales. In practical terms, innovation is moving from "can the splicer join fiber accurately?" to "can the splicer join fiber quickly, consistently, and with minimal skilled labor across a distributed fleet?"
Policy and Standards Environment
Policy and standardization activity is another important driver, though it often operates indirectly through procurement behavior and market credibility. Recognition of technical contributions at the international standards level can reinforce a company's positioning in quality-sensitive segments. For example, Sumitomo Electric Industries received the Industrial Standardization Activity Award from Japan's Ministry of Economy, Trade and Industry for contributions to IEC and ISO international standards in optical fiber fusion splicing technology. Such acknowledgment signals that splicing performance, interoperability, and testing methodologies are increasingly governed by formal benchmarks rather than ad hoc vendor specifications.
Regulatory classification also shapes market access. The U.S. Department of Commerce Bureau of Customs and Border Protection issued a tariff classification ruling placing the portable optical fiber fusion splicer under a Harmonized Tariff Schedule code associated with telecommunications equipment. While a single ruling does not transform the market on its own, it illustrates how equipment classification can influence import handling, procurement categorization, and compliance expectations. Companies that understand these classification and sourcing pathways are better equipped to navigate public-sector and institutional buying cycles without unexpected delays or administrative friction.
Demand-Side Shifts in Connectivity Buildout
Demand for fiber fusion splicing continues to be anchored by long-term connectivity requirements rather than short-term project spikes. Telecommunications deployment remains the dominant application context, driven by carrier network modernization, backhaul and fronthaul upgrades, and broadband reach extension. At the same time, data center and enterprise interconnect needs are contributing an increasingly meaningful share of activity as organizations seek higher bandwidth, lower latency, and more resilient fiber pathways between facilities and within campus environments.
What is changing is not the existence of demand, but its operational texture. Network builders are prioritizing deployment models that reduce labor dependency, improve splicing consistency across multiple crews, and support rapid restoration in the field. This favors equipment that can be deployed by smaller teams, integrated into repeatable process workflows, and maintained with minimal downtime. The practical implication is that demand growth is increasingly tied to total installation efficiency rather than splicer unit count alone. Buyers are more likely to reward platforms that help them meet project timelines and service-level expectations, especially when skilled technicians are scarce or deployment windows are compressed.
Supply Chain and Cost Structure Dynamics
Cost structures in the fusion splicer market are influenced by component availability, manufacturing scale, and the balance between hardware commoditization and value-added features. Splicers depend on precision optical, mechanical, and electronic subsystems, and any disruption in critical inputs can affect lead times and pricing. At the same time, the market's moderate concentration leaves room for multiple players to compete without a single dominant price setter, which sustains competitive tension across both global and regional suppliers.
For commercial strategy, this means that cost leadership alone is unlikely to be a durable differentiator unless paired with operational advantages that buyers can measure directly. Suppliers that can stabilize production, optimize logistics, and align pricing with total cost of ownership—such as reduced training time, fewer re-splits, and higher equipment utilization—tend to hold up better when input costs fluctuate or when end customers scrutinize project budgets more closely. The strategic opportunity lies in making cost part of a broader efficiency narrative rather than treating it as a standalone price competition.
Competitive Landscape and Leading Strategies
Company Positioning and Differentiation
The competitive field includes established Japanese manufacturers with deep telecom heritage, U.S. suppliers anchored in fiber and network infrastructure, and capable regional players with strong product focus in specific deployment contexts. Fujikura Ltd. remains closely associated with core alignment fusion splicer platforms used across telecom and enterprise applications, with models that emphasize low-loss splicing and connectivity features suited to both field and controlled-environment use. Sumitomo Electric Industries continues to position around high-speed core alignment splicers designed for field and long-haul installations, including tools with navigation and verification features that support challenging deployment conditions.
INNO Instrument Inc. has built a profile around rugged splicing platforms with ribbon fiber support and dual-camera guidance, targeting data center and high-density deployments where multiple fibers must be handled efficiently. OFS Fitel contributes to the market through fusion splicer products oriented to single-mode fiber splicing in telecom and enterprise networks, leveraging its broader optical fiber and component background. Furukawa Electric maintains a presence through core alignment splicers and related capabilities for carrier networks and emergency repair, with attention to both single-fiber and ribbon/mass splicing scenarios. AFL Telecommunications participates through splicer products linked to intelligent alignment controls and high-volume installation use cases, including mass fusion models designed to reduce operator intervention.
Worldwide Video Splicer Market
The differentiating thread across these players is not simply feature count, but how each company aligns product design with deployment reality. Some compete on precision and reliability for demanding long-haul or carrier-grade work. Others compete on ruggedness, high-density compatibility, or workflow automation for data center and enterprise environments. This segmentation matters because the same splicer is rarely optimal across all settings; buyer priorities shift depending on fiber count, environment, crew skill level, and service requirements.
Market Structure Evolution
The market remains relatively fragmented, with no single dominant concentration level among top participants. This fragmented structure supports ongoing competition and limits the risk of pricing power becoming overly centralized. At the same time, it encourages strategic divergence: some firms will push toward broader platform ecosystems with service, software, and lifecycle support, while others will concentrate on specialized product strengths or regional reach.
Several evolutionary patterns are worth watching. First, product launches are increasingly oriented toward reducing manual steps and improving repeatability, which raises the bar for what counts as a competitive field tool. Second, procurement activity from government or institutional buyers can shift short-term demand visibility and reward suppliers with clear compliance and sourcing readiness. Third, standards-related recognition and classification clarity can influence purchasing confidence, especially where buyers need to justify selections through formal specifications or procurement frameworks. Taken together, these dynamics suggest a market that will continue to support multiple credible players, but where share gains will increasingly depend on how well companies connect product capabilities to customer workflow outcomes.
Future Trend Outlook: 2026 to 2032
Trend 1: Automation as a Commercial Imperative
Over the next several years, automation features are likely to move from desirable enhancements to baseline expectations in many segments. Auto alignment detection, guided cleave verification, and reduced manual correction steps will become more central to product value propositions as deployment teams seek to standardize results across crews and locations. This trend carries a clear commercial opportunity: manufacturers that package automation with intuitive interfaces, maintenance diagnostics, and fleet-management compatibility can position themselves as partners in operational efficiency rather than as hardware vendors alone.
The associated risk is that automation expectations may outpace real-world usability. Features that look strong in specification sheets but are difficult to use under field conditions can undermine adoption. The winners are likely to be those who validate automation in practical deployment environments and tie it to measurable improvements in speed, consistency, and training burden.
Trend 2: Broader Demand Across Telecom and High-Density Interconnect
Demand growth will continue to be supported by telecommunications infrastructure, but the mix will broaden as high-density fiber environments gain importance. Data center interconnects, enterprise campuses, and dense urban fiber architectures create scenarios where splicing volume, repeatability, and fiber management complexity are all elevated. In these settings, ribbon-compatible and mass fusion capabilities can become more commercially relevant because they address throughput needs that single-fiber workflows struggle to meet efficiently.
The strategic opportunity here is to align product roadmaps and service offerings with the environments where splicing occurs most intensively. Suppliers that can demonstrate credible solutions for both mainstream telecom and high-density applications will be better positioned to capture demand across multiple project types rather than relying on a single pipeline.
Trend 3: Procurement Formalization and Standards-Linked Confidence
As public-sector and institutional buying becomes more structured, formal sourcing activity and classification clarity may increasingly influence purchase timing and supplier selection. Recent government sources sought notices and tariff classification rulings point to an environment where procurement readiness and standards alignment can affect market access. Companies that maintain documentation discipline, understand sourcing pathways, and can demonstrate consistency with recognized standards may find it easier to participate in structured buying processes.
Optical Fiber Patch Cord Market
The risk is that formalization can slow decision cycles or create barriers for suppliers less prepared for compliance-oriented purchasing. The opportunity is to treat procurement readiness as part of the product and go-to-market strategy, not as a back-office afterthought. In practice, this means clear product categorization, traceability, and specification support that make it easier for buyers to justify selections within formal acquisition frameworks.
PW Consulting Automotive & Machinery Research Center
Strategic Recommendations for Decision Makers
For Manufacturers and Product Strategy Teams
- Prioritize workflow outcomes over feature count. Design improvements around measurable field benefits such as reduced manual correction time, lower training requirements, and higher first-pass success, because these are the factors that buyers increasingly value in cost-conscious, labor-constrained environments.
- Build differentiation around total cost of ownership. Where hardware pricing is under pressure, emphasize service, lifecycle support, and operational efficiency gains that help customers justify purchase decisions beyond initial unit price.
- Prepare for procurement-aware selling. Maintain clear product classification understanding, specification support, and documentation practices that reduce friction in institutional and government-facing sales cycles.
For Investors
- Focus on companies with automation roadmaps tied to real deployment conditions. The most durable value creation is likely to come from suppliers that can translate features into repeatable field performance and fleet-level efficiency rather than from those competing mainly on incremental spec improvements.
- Watch demand mix, not just headline growth. Markets with a balanced base in telecom and expanding high-density interconnect needs may offer more resilient revenue streams than those dependent on a single deployment cycle.
- Assess competitive resilience through customer retention and service economics. In a fragmented market, the ability to maintain relationships through support quality, parts availability, and predictable uptime can be as important as product launches.
For Procurement and Network Operations Leaders
- Evaluate splicer platforms against total installation efficiency. Consider not only splice loss and accuracy, but also crew training burden, time to first splice, error recovery, and maintenance responsiveness, since these factors shape project throughput and service restoration.
- Align equipment selection with deployment context. High-density or mass-splicing environments may require different tooling priorities than routine single-fiber field repairs, so procurement criteria should reflect the actual mix of work the team will perform.
- Plan for lifecycle support and sourcing clarity. Equipment that fits cleanly into procurement pathways and comes with reliable support structures can reduce administrative and operational risk across multi-year deployment programs.
The optical fiber fusion splicer market is moving toward a phase where growth is increasingly defined by operational efficiency, procurement readiness, and the ability to serve both mainstream telecom and high-density interconnect environments. Companies and buyers that focus on these practical outcomes are better positioned to capture value as the market expands toward 2032. For decision makers seeking more detailed segmentation data, company-level assessments, and tailored commercial guidance, reviewing the complete research report can provide additional depth beyond the strategic trends outlined here.
For detailed analysis of this topic, please visit the official page: Optical Fiber Fusion Splicer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


