



Dicalcium Phosphate Market Insights: Decoding 5.0% CAGR Growth Drivers to 2032

Navigating the Dicalcium Phosphate Market: Strategic Imperatives for the Next Decade
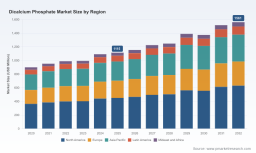
The global Dicalcium Phosphate market enters the late 2020s at a critical juncture. Between 2020 and 2025, the industry expanded from approximately $900 million to over $1.1 billion, reflecting sustained demand across feed, food, and pharmaceutical applications. Forward projections through 2032 indicate a trajectory toward $1.56 billion, underpinned by a compound annual growth rate of roughly 5.0 percent. These figures do not tell a simple growth story. They reveal a market undergoing structural realignment, where value creation increasingly depends on grade specialization, regulatory compliance, and supply chain resilience rather than volume alone.
Tricalcium Phosphate Market
Market Snapshot and Underlying Tensions
Historically, Dicalcium Phosphate benefited from predictable procurement cycles in animal nutrition and steady utilization in food fortification. The recent acceleration, however, has been uneven. Feed-grade volumes remain the largest share of total revenue, but food-grade and pharmaceutical-grade streams are gaining relative importance as downstream industries prioritize purity, traceability, and functional performance. The market remains moderately concentrated, with the top three players collectively controlling a substantial portion of output and the top five firms capturing the majority of traded supply. This concentration creates both stability for established buyers and friction for new entrants seeking scale.
Three structural tensions currently shape the operating environment. First, the industry must reconcile volume-driven economics with tightening quality thresholds. Feed applications demand cost efficiency, while food and pharmaceutical applications impose rigorous impurity limits, moisture control, and documentation standards. Second, geographic demand is shifting in ways that stress traditional logistics networks. Emerging agricultural intensification and expanding food processing capacity in Asia Pacific and Latin America are creating pull that legacy European and North American production hubs must route efficiently. Third, the sector faces margin pressure from raw material volatility, which interacts with regulatory compliance costs to reshape the profitability equation for mid-tier producers.
The practical implication is clear: competitive advantage no longer belongs to generic producers. It accrues to firms that can manage multiple grade specifications within the same facility, convert compliance into a commercial differentiator, and align production footprints with regional demand centers.
Key Drivers Reshaping the Market
Technology and Process Innovation
Advancements in precipitation control, drying, and particle engineering are redefining what Dicalcium Phosphate can deliver in end-use applications. Fine-tuning of crystal morphology and moisture content is improving flowability and compressibility for tablet formulations, while also supporting consistent phosphorus bioavailability in feed premixes. Producers that invest in process automation and inline quality monitoring are better positioned to reduce batch variability, minimize rework, and meet the increasingly strict documentation expectations of food and pharmaceutical buyers. Over time, these operational improvements translate into lower total cost of ownership for customers, which is becoming a decisive factor in vendor selection.
PW Consulting
Regulatory and Policy Environment
Regulatory frameworks are acting as both a barrier and a catalyst. In the European Union, stringent purity thresholds for feed additives have elevated quality expectations across the supply chain, effectively filtering out producers that cannot sustain consistent compliance. Meanwhile, food and pharmaceutical applications are governed by recognized monographs and food additive standards that define limits for heavy metals, microbial load, and related substances. These frameworks increase the cost of entry, but they also create a durable moat for capable manufacturers. In markets where regulatory harmonization is advancing, compliant producers can command premium positioning because buyers treat quality assurance as a non-negotiable input to their own brand risk management.
Demand-Side Behavior Shifts
The demand picture is changing on both the animal nutrition and human nutrition fronts. In feed, the growth of intensive livestock and aquaculture operations is driving consistent phosphate requirements, but buyers are also more selective, favoring suppliers that can guarantee specification stability across seasons and shipments. In food fortification and supplements, rising awareness of bone health, mineral supplementation, and clean-label sourcing is encouraging manufacturers to seek Dicalcium Phosphate grades with documented purity and predictable functionality. Pharmaceutical and related applications continue to value excipient performance and regulatory traceability. Across these segments, the common thread is a shift from price-first procurement toward value-first partnerships, where reliability, certificate-of-analysis consistency, and responsiveness matter as much as unit cost.
Worldwide Diethyl Chlorophosphate Market
Supply Chain and Cost Structure Dynamics
Phosphate rock remains the dominant cost input in Dicalcium Phosphate production, with estimates placing it at roughly 60 to 70 percent of operating expenses. The sensitivity of margins to raw material prices is therefore significant. Recent commodity data shows mine-level pricing hovering in the vicinity of $80 per metric ton on an f.o.b. basis, while domestic production volumes in major supplying countries remain substantial. This cost structure favors producers with secure rock access, efficient beneficiation, and the ability to hedge or contract feedstock intelligently. At the same time, logistics costs and regional energy dynamics can either amplify or dampen the impact of raw material prices. Companies that design supply chains around proximity to demand, flexible routing, and integrated quality systems are better able to protect margins during cycles of input volatility.
Competitive Landscape and Strategic Positioning
The competitive field is diversified by geography and by grade focus. Some manufacturers emphasize branded excipients and specialty formats for food, beverage, supplement, and tablet applications, building reputation around consistency and application support. Others concentrate on anhydrous and feed-grade volumes, leveraging multi-site production across Europe, North Africa, and South America to serve industrial and animal nutrition customers at scale. Additional players in China, India, and Japan maintain a strong presence in feed, food, and pharmaceutical grades, with several firms oriented toward active pharmaceutical ingredient and dihydrate formats. This mix creates a market where scale, specialization, and regional reach each provide distinct advantages.
Differentiation Levers Among Leading Players
Leading firms tend to differentiate along three axes. The first is grade breadth: the ability to serve feed, food, and pharmaceutical requirements from integrated operations reduces customer burden and increases stickiness. The second is compliance and documentation: robust quality systems, traceable sourcing, and alignment with recognized monographs and food/feed standards allow producers to enter more sensitive applications. The third is geographic fit: locating production closer to key demand clusters shortens lead times, reduces freight exposure, and improves service levels. When these levers are combined, suppliers transition from commodity vendors to application partners, which is where pricing power and long-term contracts become achievable.
Evolution of the Market Structure
The landscape is likely to trend toward selective consolidation among mid-tier producers who lack scale or compliance depth, while specialized players continue to carve out niches in food-grade and pharmaceutical-grade segments. Greenfield and expanded capacity announcements, such as recent initiatives tied to animal feed supplement production with regional government support, indicate that new entrants and existing players alike see room for targeted investment where demand is growing and logistics align. At the same time, the presence of multiple capable suppliers in Asia and India suggests that competitive intensity will remain strong on price and availability, pushing differentiated players to compete more explicitly on quality, service, and specification control. The net effect is a market that is not simply consolidating, but stratifying: commodity volumes remain contested, while higher-value grades increasingly reward precision and credibility.
Forward Outlook: Three Trends to Watch
Trend One: Grade Specialization as the New Growth Engine
Over the next three to five years, incremental growth is expected to come less from undifferentiated volume and more from higher-purity grades and application-tailored formats. Food fortification and pharmaceutical-related uses are likely to outpace pure feed growth rates in relative terms, driven by stricter quality expectations and demand for consistent functional performance. For producers, this means the most resilient revenue streams will be those supported by documented purity, controlled particle characteristics, and reliable certificate-of-analysis outcomes. The commercial opportunity lies in building grade-specific capacity and marketing supply as a quality-assured input rather than a bulk commodity.
Trend Two: Regional Rebalancing of Supply and Demand
Demand growth is expected to remain strongest where food processing, animal nutrition, and supplement manufacturing are expanding rapidly, while established markets will focus on replacement, reformulation, and premiumization. This rebalancing encourages investment in production and blending capabilities that are closer to emerging demand hubs. It also rewards logistics agility, because buyers increasingly value shorter, more predictable supply paths. Firms that align footprint decisions with regional demand trajectories can reduce transit risk, improve service levels, and capture share from distant suppliers that are more exposed to freight and timing variability.
Trend Three: Compliance as a Commercial Asset
Regulatory scrutiny and buyer diligence are unlikely to ease. The practical consequence is that compliance infrastructure, audit readiness, and documentation consistency will become explicit buying criteria rather than background requirements. Producers that institutionalize quality assurance and can demonstrate alignment with food and feed standards will find it easier to enter and retain sensitive applications. The risk is equally clear: any lapse in specification control or documentation can quickly erode customer trust in these grades. Organizations that treat compliance as a strategic capability rather than a cost center will be better positioned to defend margins and expand into higher-value channels.
Strategic Actions for Decision Makers
For manufacturers, the priority is to clarify grade strategy and invest where differentiation is defensible. Facilities that can flexibly serve feed, food, and pharmaceutical requirements with rigorous quality controls will capture more resilient demand than those locked into a single price-competitive segment. Process automation, inline monitoring, and clean documentation workflows should be treated as enablers of premium positioning, not merely operational improvements. Where raw material exposure is high, securing reliable rock supply and designing efficient production routes can help stabilize margins during price swings.
For investors, the opportunity is to evaluate exposure through the lens of grade mix and compliance depth rather than total capacity alone. Assets tied to higher-purity food and pharmaceutical applications, or to regionally balanced production footprints, tend to offer more durable growth profiles than undifferentiated volume plays. Due diligence should emphasize feedstock arrangements, quality system maturity, and customer concentration in sensitive applications, because these factors determine whether a business can convert market growth into sustainable returns.
For procurement and supply chain leaders, the mandate is to reweight supplier evaluation toward specification reliability, documentation quality, and service predictability. Multi-grade sourcing strategies can reduce single-supplier dependency while maintaining access to premium materials when needed. Establishing clear acceptance criteria, audit expectations, and contingency routing will help protect production continuity in food and pharmaceutical contexts where variability carries disproportionate risk. In feed applications, total cost of ownership should incorporate not only unit price but also consistency, lead-time reliability, and the cost of non-conformance.
The market’s next phase will reward participants who can read these shifts early and act on them with discipline. While the headline trajectory points to steady expansion, the real strategic value lies in understanding how grade demand, regulatory intensity, and regional supply dynamics interact at the segment level. For decision makers seeking a fuller picture of sub-segment sizes, regional pathways, and company-level positioning to inform investment and procurement choices, the detailed research report provides the granular data and customized analysis needed to move from broad direction to executable plan.
For detailed analysis of this topic, please visit the official page: Dicalcium Phosphate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


