



Hydrogen Fuel Cell Gas Diffusion Layer Market Hits $2B, 5 Shifts Reshaping Growth Through 2032

Hydrogen Fuel Cell Gas Diffusion Layer Market: Strategic Trends and Commercial Opportunities Through 2032
The hydrogen economy has graduated from pilot programs and regulatory mandates to a phase where material science and component reliability directly determine commercial viability. At the heart of every proton exchange membrane fuel cell lies the gas diffusion layer, a deceptively thin component that governs water management, reactant transport, electrical conductivity, and long-term durability. While often treated as a commodity within fuel cell stacks, the gas diffusion layer market has matured into a strategically distinct segment where performance trade-offs, supply chain resilience, and sustainability credentials increasingly separate winners from the rest. Market trajectory data from 2020 through 2032 point to a sustained expansion from approximately 700 million USD in 2020 to the 2 billion USD threshold in 2025, with continued growth projected at a compound annual growth rate of 13.18 percent through the 2026 to 2032 window, reaching the 4 billion USD mark by 2032. This trajectory reflects more than demand pull; it signals a structural shift in how hydrogen technologies are engineered, manufactured, and scaled across automotive, stationary, and emerging portable applications.
The current landscape is defined by accelerating adoption in heavy-duty mobility and distributed power, yet it is simultaneously pressured by material complexity, regulatory divergence, and concentrated manufacturing know-how. The industry is not simply searching for cheaper substrates; it is recalibrating the performance envelope to support higher current densities, colder start-up conditions, longer stack lifetimes, and tighter environmental standards. Understanding where the market is heading requires looking past headline sizing and into the operational realities that shape procurement, R&D prioritization, and competitive positioning.
Market Landscape and Core Challenges
Sizing the Opportunity Without Losing Sight of the Complexity
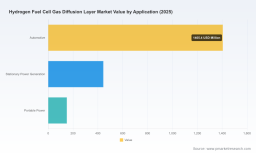
The hydrogen fuel cell gas diffusion layer market has expanded from roughly 700 million USD in 2020 to about 2 billion USD in 2025, with projections indicating further growth to 2.27 billion USD in 2026 and a steady climb toward 4 billion USD by 2032. This growth path is underpinned by a compound annual growth rate of 13.18 percent, reflecting cumulative demand from fuel cell electric vehicles, stationary power systems, and a broadening set of specialized applications. The expansion is not uniform across segments or geographies. Asia Pacific continues to anchor a substantial portion of volume, driven by manufacturing scale and policy-backed deployment, while North America and Europe contribute strongly through technology-intensive applications and stringent durability requirements. Carbon-based substrates remain the dominant material family, with carbon paper securing the largest share of the market, supported by carbon cloth and a smaller but strategically important pool of alternative formats. Automotive applications lead demand, followed by stationary power generation and portable power segments that, while smaller in absolute terms, provide valuable entry points for differentiated product strategies.
Beyond the numbers, the market is defined by a high degree of concentration. A relatively small group of established players commands a dominant share of total revenue, reflecting the technical barriers associated with fiber architecture, microporous layer formulation, and hydrophobic treatment consistency. This concentration gives incumbents an advantage in qualification cycles and volume supply, but it also exposes the market to fragility when disruption arrives in the form of material substitution, regulatory pressures, or regional trade dynamics.
Key Challenges and Inflection Points
The first challenge is performance versus durability trade-offs under real operating conditions. Gas diffusion layers must balance effective gas transport with water removal and electron conduction, all while enduring mechanical compression, thermal cycling, and chemical exposure over thousands of hours. As stack designs push higher power density and faster load acceptance, the tolerance for inconsistency narrows. Any mismatch in thickness uniformity, pore distribution, or hydrophobic treatment can manifest as localized flooding, mass transport losses, or accelerated degradation. The market is therefore shifting from acceptable baseline performance toward application-tuned solutions, which increases complexity in both manufacturing and qualification.
The second challenge is the material sustainability and regulatory environment. Traditional gas diffusion layers rely heavily on carbon fiber paper or cloth treated with perfluorinated hydrophobic agents such as PTFE to manage water repellency. While effective, these chemistries face increasing scrutiny in certain markets, and supply chains are being tested by environmental policy direction, potential trade barriers, and the broader push toward circular material strategies. This is not merely an environmental narrative; it is a sourcing risk and a design constraint. Manufacturers and system integrators must now consider whether existing material choices will remain viable under future regulatory frameworks, and whether alternative hydrophobic approaches can deliver equivalent performance without compromising cost or lifecycle expectations.
The third challenge is supply chain concentration and geopolitical exposure. Because a limited number of suppliers and specialized raw material streams support the sector, regional trade constraints and component-level bottlenecks can disrupt lead times and pricing. For program planners and procurement teams, the implication is clear: single-source dependency is increasingly risky, and qualification strategies need to account for geographic diversification and alternative material pathways without sacrificing stack performance.
Together, these challenges create a market inflection point. Demand is strong enough to justify investment, but the value is shifting toward suppliers and system integrators who can manage durability, regulatory compliance, and supply resilience simultaneously. The question is no longer whether the market will grow, but which players can turn material innovation and supply chain strategy into durable competitive advantage.
Key Drivers Shaping the Market
Technology Innovation as a Performance Multiplier
Material and process innovation remains the most powerful driver of market evolution. The gas diffusion layer is moving from a standardized component toward a performance-critical enabler of stack efficiency and system cost. Research and development activity is increasingly focused on tuning fiber architecture, optimizing microporous layer distribution, and refining hydrophobic treatments to reduce mass transport losses while preserving mechanical integrity. Equally notable is the emergence of fluorine-free hydrophobic approaches that explore interpenetrating networks of graphene, cellulose fiber, and modified polypropylene fiber. These alternatives are not simply substitutes; they represent a broader push to decouple water management performance from perfluorinated chemistry, potentially lowering long-term regulatory exposure while opening new performance windows.
In parallel, production innovation is gaining strategic relevance. Pilot lines using recycled carbon fibers have been introduced to reduce raw material waste, with some programs targeting reductions in waste by up to 40 percent. This matters because GDL manufacturing is sensitive to fiber quality, fiber alignment, and treatment consistency. The ability to preserve performance while expanding recycled content can improve cost structures and supply flexibility, while also responding to customer and regulatory expectations around circularity. In practical terms, material innovation is no longer confined to the lab; it is becoming a commercial lever that influences qualification success, total stack cost, and long-term supply viability.
Policy and Regulatory Direction as a Deployment Accelerator
Policy remains a foundational driver, but its influence is evolving from general hydrogen support to more specific requirements around durability, sourcing, and environmental compatibility. Public incentives, zero-emission vehicle mandates, and hydrogen infrastructure programs continue to stimulate demand across mobility and stationary power. At the same time, regional policy divergence is shaping procurement strategies. In Europe, the push for green energy policies and the possibility of trade barriers for certain GDL materials are encouraging supply chain localization and material differentiation. In the United States and China, trade constraints on critical components can affect availability and cost, making regional capability and supplier diversification more valuable than ever.
For commercial decision-makers, the policy environment is not just about volume; it is about compliance risk and time-to-market. Stack developers that design with regulatory trajectory in mind can reduce the probability of late-stage redesigns, whereas those dependent on materials or chemistries facing future restrictions may face higher qualification costs and shorter product lifecycles. Policy is therefore a demand driver, but also a design constraint that shapes the strategic value of material choice.
Demand-Side Shifts Toward Reliability and Total Cost
Demand behavior is maturing on both the consumer and enterprise sides. In automotive applications, the focus has moved beyond proving feasibility to optimizing total cost of ownership, stack longevity, and cold-start reliability. Fleets and OEMs increasingly evaluate fuel cell components not by unit price alone but by their impact on maintenance intervals, degradation rates, and system uptime. In stationary power generation, demand is influenced by grid resilience needs, backup power requirements, and the desire for low-emission distributed generation. Portable power applications, while smaller, contribute to a broader commercial ecosystem where reliability and specific performance characteristics can justify differentiated products.
This shift changes how gas diffusion layers are valued. A GDL that is marginally more expensive but improves water management under dynamic load or extends stack life can be commercially superior to a lower-cost alternative that introduces performance variability. As a result, demand-side behavior is rewarding suppliers that can provide application-specific optimization, consistent quality, and evidence of durability under real operating conditions.
Supply Chain and Cost Structure Realignment
Supply chain dynamics are being reshaped by the interaction of material specialization, regional production capability, and cost pressure. Carbon fiber-based substrates remain central, yet the cost structure of these materials is sensitive to precursor availability, processing efficiency, and the degree of customization required by fuel cell manufacturers. As volumes scale, there is increasing pressure to improve throughput, reduce waste, and standardize dimensions and treatment protocols without sacrificing performance. At the same time, demand for resilience is encouraging dual-sourcing, geographic diversification, and greater transparency into material provenance.
The cost conversation is therefore moving from unit price to total economic value. Suppliers that can offer stable lead times, reproducible quality, and material strategies aligned with future regulatory expectations gain leverage even if their nominal pricing is not the lowest. Conversely, initiatives that reduce waste, increase recycled content, or streamline treatment steps can create meaningful cost advantages while also strengthening sustainability positioning. In this environment, supply chain strategy is a competitive differentiator rather than a back-office concern.
Competitive Landscape and Leading Strategies
Incumbents and the Architecture of Advantage
The market features a mix of specialized material suppliers, broader industrial composites players, and application-oriented distributors, with a clear tilt toward a concentrated group of established leaders. Companies such as SGL Carbon, Toray Industries, Freudenberg Group, AvCarb LLC, Caplinq Corporation, Technical Fibre Products Ltd, Mitsubishi Chemical Corporation, Fuel Cells Etc, Mott Corporation, and GKD Gebr. Kufferath AG each occupy distinct positions in the value chain, balancing scale, specialization, and customer proximity.
SGL Carbon remains a notable leader in carbon paper and carbon cloth gas diffusion layers, with product families built around microporous layer and PTFE treatment for PEM hydrogen fuel cells. Its strategic advantage is rooted in material expertise, manufacturing discipline, and the ability to support qualification programs with consistent product performance. Recent capacity expansion activity has also signaled a forward-looking approach to sustainability, including pilot production using recycled carbon fibers to reduce raw material waste. This combination of performance credibility and supply-side innovation helps reinforce its position in a market where qualification cycles and reliability matter as much as unit economics.
Toray Industries brings a strong composites and advanced materials heritage, with carbon paper GDL products supporting both PEM fuel cells and water electrolyzers. Its presence across hydrogen-related applications gives it broader exposure to the hydrogen ecosystem and an ability to align material development with adjacent technology demand. Participation in industry exhibitions and technical exchanges has reinforced its focus on communicating product capability for PEM fuel cell and electrolyzer use, emphasizing the link between material performance and system-level outcomes.
Freudenberg Group contributes a broad fuel cell gas diffusion layer portfolio spanning carbon cloth and paper types. Its advantage often lies in systems-level thinking and application breadth, which can support differentiated offerings for specific operating environments. AvCarb LLC and Caplinq Corporation occupy more specialized positions in the North American market, with product lines that include carbon cloth and carbon paper-based GDLs and conductive plastic alternatives. These companies often compete on responsiveness, customization, and the ability to serve research, pilot, and production needs with flexible supply.
Technical Fibre Products Ltd, Mitsubishi Chemical Corporation, Fuel Cells Etc, Mott Corporation, and GKD Gebr. Kufferath AG round out a diverse competitive field. Some focus on carbon fiber cloth and felt-based diffusion layers, others on porous substrates or mesh-based configurations, and some on distribution and broader component availability. Their presence illustrates that the market is not monolithic; there is room for both generalized scale players and specialized suppliers, depending on application requirements, volume, and regional service expectations.
Differentiation and Strategic Positioning
The competitive edge in this market is increasingly multidimensional. Performance consistency and durability remain foundational, but differentiation now also depends on material sustainability, supply resilience, and application-specific engineering support. Leaders tend to combine several of the following capabilities:
Hydrogen and Fuel Cells Market
- Advanced control over fiber structure and microporous layer uniformity to support predictable electrochemical performance
- Hydrophobic treatment strategies that balance water management with regulatory and sustainability considerations
- Production flexibility that enables both standardized high-volume products and tailored solutions for demanding applications
- Supply chain transparency and geographic or sourcing diversification to reduce exposure to trade and material constraints
- Technical engagement with stack developers and system integrators to align material properties with real operating conditions
In practical terms, this means the most resilient players are not necessarily those with the simplest cost structure, but those that can translate material know-how into reliability, compliance readiness, and customer-specific value.
Evolution of the Competitive Structure
The market is likely to experience both consolidation and fragmentation pressure over the next several years. On one hand, scale advantages in material production, qualification support, and global supply can favor larger incumbents and encourage integration across the component value chain. On the other hand, niche applications, regional demand pockets, and material innovation pathways create opportunities for specialized entrants and for suppliers that can move faster on sustainability-driven redesigns. New entrants that bring fluorine-free hydrophobic concepts, improved recycled content strategies, or novel porous architectures may find traction in specific performance segments, especially where incumbents are constrained by legacy chemistry or older production lines.
Worldwide Bipolar Plate Fuel Cell Market
At the same time, distributors and multi-brand providers will continue to play a useful role in lowering entry barriers for research teams, pilot programs, and smaller-scale deployments. However, the strategic center of gravity remains with suppliers that can support volume production with consistent quality and a credible path through changing regulatory and sustainability expectations. The market is thus evolving from a relatively narrow competition around material type into a broader contest over reliability, compliance, and supply resilience.
Future Trends and Commercial Opportunities
Trend One: Performance-Tailored GDL Design Becomes the Norm
As stack requirements diverge by application, the market is moving toward more application-tuned gas diffusion layers rather than one-size-fits-all substrates. Automotive stacks with high dynamic load cycles, stationary systems with long-duration operating profiles, and specialized portable units each impose distinct water management, compression, and durability demands. Suppliers that can configure pore structure, thickness, and treatment characteristics to match these profiles will be better positioned to capture value. The commercial opportunity lies in moving from transactional component supply to engineered solution partnerships, where performance data, validation support, and lifecycle outcomes become part of the commercial proposition.
Trend Two: Sustainability-Driven Material Redesign Gains Commercial Weight
Regulatory direction and customer expectations are increasing the strategic importance of fluorine-free hydrophobic approaches and recycled or lower-waste production methods. Material redesign is not only an environmental initiative; it is a risk management and differentiation lever. Suppliers that can demonstrate equivalent or superior performance with alternative chemistries or improved material efficiency can open access to customers seeking to reduce future compliance exposure and improve sustainability narratives. The opportunity is to align R&D with market-facing requirements early, so that material alternatives are commercially viable when needed rather than arriving too late to influence program decisions.
Trend Three: Regionalization and Supply Diversification Become Structural Requirements
Given the concentration of expertise and material streams, regional demand growth will increasingly encourage localized supply capabilities, dual sourcing, and more resilient qualification pathways. Trade dynamics and component-level constraints can stretch lead times or complicate sourcing, making geographic diversification a pragmatic hedge. For suppliers, the commercial opportunity is to build regional service depth, maintain reproducible quality across sites, and offer credible alternatives when program planners seek to reduce single-source exposure. For buyers, the opportunity is to secure performance without locking into fragile supply arrangements.
Risks and Uncertainties to Factor Into Planning
Despite the positive trajectory, several uncertainties warrant attention. Material substitution may take longer than anticipated if alternative hydrophobic chemistries or new fiber architectures struggle to meet durability and cost thresholds at scale. Policy divergence could create uneven demand across regions, with some markets accelerating while others face compliance or trade complications that slow deployment. Supply chain disruptions affecting carbon fiber precursors, treatment chemicals, or specialized manufacturing equipment can create cost and timing volatility. In addition, if fuel cell adoption in certain segments underperforms relative to expectations, even a strong overall market can hide segment-level weakness that affects supplier revenue mix. Decision-makers should therefore treat momentum as real but conditional, and design strategies that can adapt to changes in regulation, material availability, and application demand.
PW Consulting
Strategic Recommendations for Decision-Makers
For Manufacturers and Material Suppliers
Prioritize performance consistency and durability evidence as the basis for commercial differentiation. As qualification cycles lengthen and application requirements diversify, the ability to demonstrate reproducible behavior under real operating conditions becomes a decisive advantage. At the same time, invest early in material innovation that addresses sustainability and regulatory trajectory, including fluorine-free hydrophobic options and waste-reducing production approaches. Building flexibility into product architecture and manufacturing processes will allow faster response to changing customer needs and reduce the risk of being locked into legacy chemistries.
For Investors and Strategic Partners
Focus on companies and technologies that combine material expertise with supply resilience and a credible path through regulatory change. The most attractive opportunities are likely to sit at the intersection of performance reliability, sustainability alignment, and regional supply capability. In diligence, look beyond near-term revenue and assess whether a supplier can sustain quality, support qualification, and adapt material strategies as policy and customer expectations evolve. Portfolio exposure to hydrogen applications should also account for segment variability, since automotive, stationary, and portable demand can follow different adoption rhythms.
For Procurement and System Integrators
Treat gas diffusion layer sourcing as a strategic decision rather than a commodity purchase. Evaluate suppliers on quality consistency, application fit, lead-time reliability, and alignment with future regulatory expectations. Where possible, diversify sourcing and establish qualification pathways that allow alternative materials or regions to be introduced without disrupting program timelines. The goal is to secure stack performance while reducing exposure to single-source dependency and material chemistry risk.
The strategic significance of the hydrogen fuel cell gas diffusion layer market is growing alongside its size. Demand momentum is clear, but long-term value will accrue to those who manage the intersection of performance, sustainability, and supply resilience with discipline. For decision-makers who need deeper segmentation, competitive benchmarking, regional demand detail, and scenario-based planning data, the full PW Consulting market research report provides the structured, granular intelligence needed to translate these trends into concrete business decisions.
For detailed analysis of this topic, please visit the official page: Hydrogen Fuel Cell Gas Diffusion Layer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


