



Yucca Mohave Extract Market: Why 5.75% CAGR and 78% CR5 Redefine 2032 Outlook

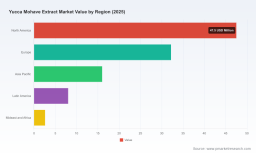
Strategic Trends and Commercial Opportunities in the Yucca Mohave Extract Market
The Yucca Mohave Extract market has entered a phase of structural expansion, characterized by steady revenue growth across a diverse set of downstream applications. Based on the 2025 baseline and forward projections through 2032, the sector is positioned to advance at a compound annual growth rate of 5.75%. Revenue climbed from 81.15 million in 2020 to 106.3 million in 2025, with the trajectory expected to reach 156.98 million by the end of the forecast window. This pace reflects more than cyclical demand recovery; it signals a maturing value chain where botanical extracts are increasingly integrated into mainstream wellness, nutrition, and specialty industrial formulations.
For executives and investors, the growth profile matters less as an isolated metric and more as a signal of where capital, production capacity, and product development are flowing. The market’s expansion is not uniform across all formats or end uses, and the underlying dynamics reveal clear entry points for companies that can align sourcing, compliance, and application expertise with shifting buyer expectations. At the same time, the sector faces a set of operational and strategic pressures that will separate resilient operators from those dependent on commodity-style positioning.
The following analysis maps the current market environment, identifies the forces shaping demand and supply, examines how leading companies are positioning themselves, and outlines the trends most likely to define the next three to five years. The objective is to provide decision-makers with a practical framework for evaluating where value is being created and where exposure should be managed.
Market Snapshot and Core Challenges
The market’s size and growth path indicate a sector that has moved beyond early adoption and is now scaling within established distribution channels. The upward arc from 2020 through 2025 was not linear, with a modest contraction in one recent year before the 2025 rebound. That pattern suggests a market responding to supply availability, pricing adjustments, and procurement cycles rather than one driven purely by end-market enthusiasm. Looking ahead, the forecast implies that growth will increasingly depend on product standardization, broader application penetration, and the ability of suppliers to maintain consistent quality at scale.
Worldwide Sugar Beet Juice Extract Market
Three challenges stand out as critical to navigating the next phase of expansion.
Supply Consistency and Botanical Variability
Yucca Mohave extract is rooted in a specific botanical source, and variability in raw material quality can cascade through extraction yields, active content consistency, and final product performance. Companies operating at higher volumes must manage harvest timing, regional sourcing differences, and post-harvest handling to avoid inconsistencies that undermine customer trust. In categories such as dietary supplements and food ingredients, buyers increasingly expect batch-to-batch reliability and documented potency, which places pressure on suppliers to invest in traceability and process control.
Regulatory and Quality Assurance Complexity
As yucca-derived ingredients move further into regulated and semi-regulated spaces, documentation and manufacturing standards are becoming competitive differentiators rather than compliance overhead. Buyers in pharmaceuticals, nutraceuticals, and food applications are paying closer attention to sourcing integrity, extraction methods, and certification status. Suppliers that can demonstrate robust quality systems and transparent ingredient provenance are better positioned to enter higher-value channels, while those relying on less formal assurance may face barriers to expansion.
Competitive Concentration and Margin Pressure
The market remains relatively concentrated among established participants, which creates both stability and tension. Concentrated supply can support consistent market intelligence and long-term buyer relationships, but it also raises the stakes for differentiation. As more manufacturers introduce powdered, liquid, and encapsulated formats, price competition can intensify in commodity-adjacent segments. Companies that compete primarily on volume without distinct technical or application advantages may find margins squeezed, especially when raw material or processing costs fluctuate.
Key Drivers Shaping Market Direction
The market’s trajectory is being shaped by a combination of technological, regulatory, demand-side, and supply chain forces. These drivers do not operate in isolation; they interact to determine which product formats gain traction, which applications expand fastest, and which suppliers are able to command premium positioning.
Technological Innovation in Extraction and Standardization
Extraction and processing methods continue to influence product performance and commercial flexibility. Different approaches can affect purity, solubility, color, taste profile, and active content consistency, all of which matter to downstream formulators. Suppliers that invest in refined extraction processes and standardized outputs are better equipped to serve customers who need predictable ingredient behavior in complex formulations. This is especially relevant in liquid and powder formats, where application performance can dictate repeat purchasing and product line expansion.
Recent operational developments underscore how quality-focused improvements are becoming part of the competitive narrative. For example, certification achievements that strengthen excipient-grade manufacturing and quality assurance contribute to greater buyer confidence in yucca-derived saponin ingredients. In parallel, capacity expansion by producers seeking to meet rising demand reflects the industry’s move toward scaling while attempting to preserve quality standards. These moves are not merely operational; they signal a market in which performance assurance and manufacturing credibility are becoming central to growth.
Policy and Regulatory Environment as an Enabler and Filter
Regulatory expectations are increasingly influencing market access. In sectors where ingredients are incorporated into health-oriented products or food and beverage formulations, documentation, safety substantiation, and manufacturing discipline can determine whether a supplier is eligible for certain buyer shortlists. Rather than acting as a single barrier, the regulatory environment is functioning as a filter that rewards transparency and consistent quality. This trend benefits suppliers that have invested early in compliant production practices and creates a steeper path for those attempting to enter higher-trust channels without comparable systems.
At the same time, regional differences in regulatory expectations and market norms can create uneven adoption curves. Suppliers with multi-market exposure often gain an advantage by aligning product documentation and format choices with the requirements of each destination market, enabling them to capture demand across a wider set of buyer types.
Maca Extract Market
Shifting Demand-side Behavior Across End Uses
Demand is being shaped by broader consumer and industrial preferences for plant-derived ingredients, functional benefits, and cleaner formulation profiles. In dietary supplements and food and beverage applications, buyers are looking for ingredients that can support label clarity, consumer familiarity, and formulation compatibility. In cosmetics and related personal care uses, there is growing interest in botanical inputs that fit emerging positioning around natural-origin ingredients and sensory or functional performance. Pharmaceutical-adjacent interest adds another layer, where standardization and documentation become especially important.
This diversified demand base is one reason the market can sustain growth even when one application category slows. The broader pattern suggests that yucca extract is transitioning from a narrower specialty input toward a more versatile ingredient portfolio. The commercial implication is that suppliers with application breadth can better balance volume and margin, while those overly dependent on a single end-use segment may be more exposed to category-specific volatility.
Supply Chain and Cost Structure Dynamics
Cost structures in botanical extract markets are influenced by raw material sourcing, harvesting logistics, processing intensity, and the scale of production. Because yucca Mohave extract depends on a geographically specific plant source, supply chains must manage both biological variability and transportation and processing costs. As demand increases, suppliers that can secure reliable sourcing commitments and optimize extraction efficiency are more likely to protect margins during periods of input cost pressure.
The cost equation also intersects with format strategy. Liquid and powder products can require different handling, packaging, and logistics considerations, which affects total delivered cost and customer adoption. Companies that can align format offerings with practical supply chain advantages often gain an edge in price-sensitive segments while still preserving room for premium offerings in more demanding applications.
Competitive Landscape and Leading Strategies
The market features a mix of regional specialists, vertically oriented processors, and ingredient suppliers with broader botanical portfolios. This mix creates a landscape where competitive advantage often comes from a combination of source access, extraction capability, application knowledge, and certification or quality positioning. The companies that stand out are not necessarily the largest in every dimension, but those that have constructed a defensible niche through one or more of these levers.
Strategic Positioning Among Core Participants
Several participants illustrate the different ways companies are competing in this space.
- Some manufacturers emphasize high-quality liquids and powders produced from yucca schidigera sourced for food, beverage, and animal feed use, with an emphasis on cold-pressed and application-specific formulations.
- Other U.S.-based suppliers focus on large-scale provision of pure extracts and dried powders, linking production to southwestern harvesting and processing for animal feed and nutraceutical markets.
- A further group operates as suppliers and manufacturers of food-grade plant extract raw materials for food, feed, and nutraceutical applications, often competing on standardization and supply reliability.
- Certain participants provide spray-dried, fiber-related, and extract-based products for food, feed, and industrial uses, broadening the scope of potential end markets.
- Manufacturers in Asia have entered with powder and liquid offerings targeted at healthcare products, food supplements, cosmetics, and animal nutrition, reflecting a growing international supply presence.
- Some producers highlight experience in alcohol and water extraction processes for pharmaceutical, dietary supplement, and food-grade applications, using process diversity as a point of differentiation.
- Leading processors with integrated extraction and distribution capabilities connect harvesting in the southwestern U.S. and Baja Mexico to downstream supply, reinforcing control over source-to-product flow.
- Larger specialty ingredient providers contribute standardized botanical extracts for food, beverage, and pharmaceutical uses, often leveraging broader formulation support and global distribution networks.
- Formulators focused on liquid yucca schidigera extract for aquaculture and premium animal feed illustrate how application specialization can open niche but valuable demand channels.
- Suppliers of dry plant extracts for biostimulant and plant growth applications show the market’s reach beyond human nutrition into agricultural and industrial uses.
This range of profiles indicates that the market is not defined by a single business model. Instead, success often depends on aligning sourcing access, processing capability, and application focus in a way that matches the expectations of a specific buyer group.
Differentiation and Evolving Market Structure
Differentiation is increasingly tied to credibility, consistency, and application readiness. Certification achievements and quality-system improvements are becoming meaningful signals in premium channels, especially where buyers need documented manufacturing discipline for excipient or ingredient-grade use. Capacity expansion also matters, but only when it is paired with quality control and demand alignment; otherwise, added volume can increase exposure to pricing pressure without strengthening long-term positioning.
Industry developments from recent periods reinforce this pattern. Certification milestones in excipient manufacturing highlight how quality assurance can enhance a supplier’s eligibility for more demanding applications. Capacity expansion initiatives reflect efforts to capture rising demand, but they also imply that competitive advantage will depend on whether the added capacity is absorbed by differentiated products or by commoditizing segments.
Looking at the broader structure, the market appears to be moving through a combination of consolidation and segmentation. Established suppliers with strong regional access and multi-format capabilities are likely to retain advantages in core channels, while new and expanding entrants may pursue differentiation through specific applications, geographic reach, or price-competitive formats. The result is a landscape where buyers have more options but also face a wider variance in quality, documentation, and application support.
PW Consulting Chemical & Energy Research Center
Future Trends and Commercial Opportunities
Based on current market dynamics and the trajectory of demand, three trends are likely to shape the next three to five years.
Trend One: Broader Application Integration With Higher Documentation Expectations
As yucca extract continues to appear across dietary supplements, food and beverage, cosmetics, and pharmaceutical-adjacent uses, buyers will likely demand more consistent documentation and product standardization. This trend creates commercial opportunity for suppliers that can offer not just volume, but formulation-ready ingredients with clear specifications and dependable quality. Companies that invest in technical support, application compatibility, and transparent sourcing will be better positioned to move into higher-value partnerships.
The risk here is that documentation and quality expectations may outpace the capabilities of some producers, especially those operating with less formalized systems. Suppliers that cannot meet rising assurance requirements may find themselves limited to lower-margin channels or more price-sensitive buyers.
Trend Two: Format Strategy as a Margin and Channel Differentiator
Liquid, powder, capsule, tablet, and other formats are not interchangeable from a commercial standpoint. Each format carries different processing, packaging, logistics, and customer adoption considerations. Over time, competitive advantage may increasingly come from selecting the right format mix for the intended end market rather than offering the broadest possible portfolio by default. Formulators and procurement teams will likely favor suppliers that can align format choice with performance needs and supply chain practicality.
This creates opportunities for companies that can tailor product forms to specific use cases, especially where solubility, handling, dosage form, or sensory characteristics influence repeat purchasing. The downside is that format diversification without clear application logic can increase operational complexity and dilute focus.
Trend Three: Regional Sourcing Themes and Multi-market Access
Because the raw material basis is geographically anchored, regional sourcing narratives and supply reliability will remain strategically important. Buyers in multiple markets may respond differently depending on local preferences, regulatory expectations, and price sensitivity. Suppliers with access to consistent harvests and the ability to serve multiple downstream geographies may gain flexibility in matching supply to demand cycles. At the same time, companies in emerging supply regions may expand their presence by offering competitive cost structures and targeted application support.
The opportunity lies in designing sourcing and distribution strategies that can accommodate both concentrated demand in established regions and faster growth in developing markets. The uncertainty is that botanical sourcing can be affected by harvest variability, environmental conditions, and logistics disruptions, which means multi-source planning and inventory discipline will remain important.
Actionable Recommendations for Decision-Makers
The strategic implications vary by role, but several priorities are broadly relevant.
For Manufacturers and Ingredient Suppliers
- Prioritize standardization and quality documentation as core commercial assets, especially if expansion into food, nutraceutical, or pharmaceutical-adjacent channels is a goal.
- Align format strategy with real application demand rather than pursuing indiscriminate product-line expansion, and use format choices to differentiate on handling, solubility, or performance where it matters most.
- Evaluate sourcing and processing investments with an eye toward batch consistency and cost resilience, since these factors increasingly determine margin durability under volume growth.
For Investors
- Assess companies based on their ability to combine source access, processing discipline, and application relevance, rather than on top-line growth alone.
- Watch for indicators of quality-tier migration, such as certification progress, capacity expansion paired with demand absorption, and movement into higher-trust application segments.
- Consider exposure to format concentration and end-use dependency, since these can influence both upside and downside under changing buyer preferences.
For Procurement and Supply Chain Leaders
- Use specification clarity, documentation, and supplier quality systems as selection criteria, not just price, to reduce variability risk in downstream production.
- Build sourcing options that account for regional supply realities and format-specific logistics, especially when demand spans multiple applications or markets.
- Track supplier developments in capacity, certification, and application support, as these can affect long-term reliability and negotiation leverage.
For decision-makers seeking a deeper, more customized view of segmentation, regional dynamics, format-level demand shifts, and company-specific positioning, the full research report offers a more granular breakdown of the market and tailored strategic implications. Detailed data and segment-level analysis can support more precise planning for capacity allocation, product development, sourcing strategy, and investment prioritization.
For detailed analysis of this topic, please visit the official page: Yucca Mohave Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


