



Resistant Dextrin Market: Why 6.98% CAGR Signals a Structural Shift Beneath the $317M Forecast

The Resistant Dextrin Market: Strategic Trends and Commercial Opportunities Through 2032
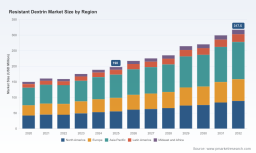
The resistant dextrin market has transitioned from a niche dietary fiber niche to a mainstream functional ingredient category with substantial commercial momentum. Valued at approximately USD 198 million in 2025, the market has demonstrated a compound annual growth rate of 6.98 percent over the historical period and is projected to expand steadily through 2032. This trajectory reflects the convergence of multiple structural shifts: rising consumer awareness of gut health, regulatory recognition of resistant dextrin as a legitimate dietary fiber, and manufacturing innovations that enable broader application across food, beverage, and nutraceutical formats. For executives and investors navigating this landscape, the market presents meaningful opportunities alongside distinct competitive and operational risks that require careful strategic positioning.
Understanding where this market is heading requires looking beyond aggregate revenue figures. The underlying dynamics involve evolving formulation requirements, shifting supply chain cost structures, and an increasingly polarized competitive field where differentiation hinges on clinical validation, regulatory approvals, and application-specific performance. This analysis examines the current market structure, the forces driving change, the competitive landscape, and the strategic implications for stakeholders across the value chain.
Market Landscape and Structural Challenges
The market's expansion over the past several years has been anything but linear. Historical data reveals periods of contraction followed by renewed growth, underscoring the influence of external shocks and demand elasticity. After a moderate decline in 2022, the market rebounded strongly through 2025 and is forecast to accelerate notably in the latter half of the projection period. This pattern suggests that the category is sensitive to macroeconomic conditions, raw material pricing, and the pace of regulatory developments, yet maintains a resilient long-term growth trajectory driven by fundamental demand shifts.
Several structural challenges define the current inflection point for resistant dextrin.
Supply Chain Volatility and Input Cost Pressure
The cost environment for key raw materials has introduced significant uncertainty into margin planning. Corn starch, a primary feedstock for most resistant dextrin production, experienced a sharp price escalation in mid-2025, reaching record levels that placed upward pressure on manufacturing costs across the value chain. For producers operating on thin margins or competing in price-sensitive segments, this volatility complicates inventory management, long-term contracting, and pricing strategies. Companies that fail to implement hedging mechanisms, diversify feedstock sources, or pass through costs effectively risk compressing profitability during periods of sustained input inflation.
Regulatory Fragmentation and Claim substantiation Requirements
While resistant dextrin enjoys growing regulatory acceptance, the path to commercialization remains uneven across jurisdictions and application categories. Regulatory recognition of specific fiber types, permissible health claims, and labeling requirements differ across regions and continue to evolve. In this environment, manufacturers must invest in clinical substantiation and regulatory navigation to secure approvals and defend market access. The increasing emphasis on evidence-backed positioning means that companies without robust clinical data or established regulatory relationships face a higher barrier to entry, particularly in healthcare and nutraceutical segments where claim substantiation is a prerequisite rather than an optional differentiator.
Application-Specific Formulation Constraints
Resistant dextrin is not a one-size-fits-all ingredient. Functional performance varies by source material, processing method, solubility profile, and compatibility with different formulation environments. Food and beverage developers face constraints related to taste modification, texture impact, stability under processing conditions, and interaction with other ingredients. These technical considerations limit the speed at which resistant dextrin can be adopted across new applications and create opportunities for suppliers who can provide application support, customized formats, and formulation guidance. The gap between generic availability and application-ready solutions represents both a challenge and a strategic lever for differentiation.
Key Drivers Shaping Market Dynamics
The growth trajectory of resistant dextrin is propelled by a combination of technological, regulatory, demand-side, and supply chain factors. Each driver carries distinct implications for market participants.
PW Consulting
Technological Innovation and Product Differentiation
Advances in enzymatic processing, starch modification, and purification techniques have expanded the range of resistant dextrin grades available to formulators. Manufacturers now offer variations in fiber content, solubility, particle size, and functional properties that enable tailored solutions for specific applications. These innovations support broader adoption by addressing formulation challenges that previously limited use in sensitive matrices such as low-pH beverages, baked goods, and clear-liquid formats.
Beyond physical properties, the emphasis on clinical validation has become a central dimension of product differentiation. Independent verification of prebiotic activity and gut health benefits through recognized certification programs has emerged as a credibility marker that resonates with both consumers and purchasing managers. Recent certification achievements by leading suppliers demonstrate how clinical evidence can be translated into marketable claims that support premium positioning and facilitate adoption in health-oriented formulations. These developments signal a shift from commodity-driven competition to evidence-based differentiation, where the strength of scientific backing increasingly determines market access and pricing power.
Regulatory Progress and Recognition Expansion
The regulatory environment has been a meaningful tailwind for resistant dextrin adoption. Recognition by major regulatory bodies as a valid dietary fiber, alongside expanded Generally Recognized as Safe status for additional food categories, has reduced ambiguity for formulators and accelerated inclusion in new products. Expanded approvals covering reduced-calorie beverages and other application areas illustrate how regulatory clarity can unlock growth by lowering development risk and enabling faster time-to-market.
Resistant Starch Market
At the same time, the regulatory landscape continues to reward companies that proactively engage with authorities and maintain comprehensive dossiers. Suppliers with established regulatory histories and documented safety profiles are better positioned to support customers through the approval process and navigate emerging requirements. As regulatory scrutiny around health claims and ingredient transparency intensifies, this capability becomes a strategic asset that compounds over time, creating a moat around well-prepared market participants.
Consumer and Enterprise Demand Shifts
Demand for functional ingredients with digestive health benefits has moved from a fringe concern to a mainstream purchasing driver. Consumers increasingly associate gut health with broader wellness outcomes, influencing food and beverage selection across categories. This shift has prompted manufacturers to incorporate fiber and prebiotic ingredients into everyday products, not just specialized health supplements. The result is a broader application footprint for resistant dextrin, spanning everyday beverages, bakery items, confectionery, dairy alternatives, and convenience foods.
On the enterprise side, brands face pressure to deliver products that align with clean-label expectations, sugar reduction goals, and functional benefits without compromising sensory quality. Resistant dextrin offers advantages in this context, including solubility, neutral flavor profiles in certain grades, and compatibility with nutritional goals such as fiber enrichment and calorie management. As product development cycles shorten and consumer expectations rise, ingredient suppliers that can provide technical support, co-development services, and rapid prototyping capabilities gain a competitive edge in securing inclusion in new formulations.
Supply Chain Structure and Cost Dynamics
The supply chain for resistant dextrin is shaped by the availability and pricing of starch feedstocks, the geographic distribution of manufacturing capacity, and logistics considerations. Production is concentrated among established players with integrated starch processing capabilities or long-standing supplier relationships, while emerging manufacturers seek to enter the market through cost-competitive positioning or regional focus. This structure creates both stability and vulnerability.
Record raw material prices illustrate how input cost fluctuations can ripple through the value chain, affecting producer margins, supplier pricing, and ultimately end-product economics. Companies that operate with flexible sourcing strategies, forward contracting, or diversified feedstock portfolios are better equipped to manage these dynamics. Conversely, reliance on single-source inputs or inflexible contract terms heightens exposure to price shocks. Over time, cost structure resilience will likely become a more prominent factor in supplier selection, particularly for large-volume buyers seeking supply security alongside competitive pricing.
Competitive Landscape and Strategic Positioning
The resistant dextrin market is characterized by a mix of established multinational ingredient suppliers and specialized manufacturers, with a notable degree of concentration among leading players. This concentration reflects the technical and regulatory barriers to entry, as well as the importance of scale, application expertise, and regulatory track records in securing market share.
Maltodextrin Market
Leading Players and Strategic Differentiation
Several companies occupy prominent positions by leveraging distinct strengths. Global ingredient manufacturers with broad portfolios and established relationships across food, beverage, and pharmaceutical channels benefit from scale, regulatory experience, and the ability to support customers across multiple markets. These players often differentiate through comprehensive technical service, co-development capabilities, and the credibility that comes with long-standing regulatory recognition.
Specialized producers have carved out positions by focusing on specific formats, source materials, or certification-backed claims. Companies offering resistant dextrin derived from corn or tapioca, with options spanning powder, liquid, and agglomerated formats, address varied formulation needs and enable customers to select grades suited to their application constraints. The availability of non-GMO, kosher, and other quality certifications further expands market access, particularly in segments where these attributes carry significant purchasing weight.
Increasingly, the competitive battleground is shifting toward evidence-based positioning. Suppliers that invest in clinical substantiation and secure independent verification of functional benefits are able to command stronger brand recognition and support customer claims with defensible data. This trend favors companies with the resources to conduct or commission clinical research and the regulatory expertise to translate findings into approved claims and certification status.
Market Consolidation and Emerging Entrants
The market structure suggests ongoing consolidation pressure, driven by the economies of scale associated with production, regulatory investment, and global distribution. Larger players are well positioned to absorb input cost volatility, fund application research, and expand capacity in response to demand growth. At the same time, regional manufacturers and distributors can find opportunities by serving localized demand, offering cost-advantaged products, or focusing on niche segments where broader players may not prioritize investment.
New entrants face meaningful hurdles. Establishing regulatory recognition, building clinical credibility, and securing consistent feedstock supply require capital and time. However, partnerships with established producers, contract manufacturing arrangements, and focused geographic strategies can provide pathways for incremental market participation. The presence of distributors and bulk suppliers that aggregate products from multiple producers also adds a layer of intermediation, which can benefit end-users seeking simplified sourcing while introducing additional considerations around quality control and supply traceability.
Forward Outlook: Trends and Opportunities (2026–2032)
Looking ahead, several trends are likely to shape the resistant dextrin market over the next several years, each carrying distinct commercial implications.
Accelerated Adoption in Everyday Food and Beverage Formats
As regulatory recognition expands and formulation capabilities improve, resistant dextrin is poised to move further into mainstream food and beverage applications. Categories that were once considered challenging for fiber enrichment, such as clear beverages, confectionery, and shelf-stable products, are becoming more accessible as ingredient grades and processing techniques evolve. This broadening application base supports volume growth and creates opportunities for suppliers who can demonstrate application-specific performance and provide formulation support that reduces development friction.
For brands, the opportunity lies in leveraging resistant dextrin to meet multiple objectives simultaneously: fiber enrichment, sugar reduction, texture management, and functional benefits. Success in this environment depends on selecting grades that align with product requirements and on communicating benefits in ways that resonate with target consumers without overstepping regulatory boundaries.
Evidence-Based Positioning as a Core Competitive Lever
The emphasis on clinical evidence and independent certification is expected to intensify. As consumers and purchasing managers become more sophisticated about ingredient claims, suppliers with verified functional benefits and documented safety profiles will hold an advantage in securing inclusion in premium and health-oriented products. Certification programs that evaluate prebiotic function and other claimed benefits provide third-party validation that can differentiate products in crowded markets and support premium pricing where justified.
This trend also introduces risk for companies that rely on generic positioning without substantive clinical backing. As the category matures, differentiation will increasingly depend on the credibility of functional claims and the quality of supporting data, making investment in research and regulatory documentation a strategic priority rather than an optional enhancement.
Supply Chain Resilience and Sourcing Strategy Recalibration
Input cost volatility and the concentration of feedstock supply are likely to drive recalibration of sourcing strategies across the value chain. Buyers and producers alike will place greater emphasis on supply security, long-term contracting, feedstock diversification, and regional capacity considerations. These dynamics may encourage investment in additional production capacity in key markets, as well as closer collaboration between ingredient suppliers and end-product manufacturers to manage risk and ensure consistent availability.
For market participants, the strategic implication is clear: resilience in supply chain design will increasingly influence competitiveness. Companies that build flexibility into sourcing, maintain transparent quality systems, and develop contingency plans for input disruptions will be better positioned to sustain operations and customer relationships through periods of volatility.
Potential Risks and Uncertainties
Despite the favorable long-term outlook, risks remain. Regulatory shifts, including changes to fiber recognition criteria or health claim requirements, could alter market access conditions. Raw material cost fluctuations may compress margins for players without effective risk management. Competitive intensity could increase as new entrants attempt to capture share through price competition, potentially pressuring returns in segments where differentiation is weaker. Additionally, consumer trends are subject to change, and categories that appear promising today may face headwinds if broader wellness preferences shift or if alternative ingredients gain traction.
Navigating these uncertainties requires continuous monitoring of regulatory developments, input market conditions, and competitive activity. Strategic agility, grounded in accurate intelligence, will be essential for capitalizing on opportunities while mitigating downside exposure.
Strategic Implications for Decision-Makers
The resistant dextrin market presents distinct considerations for manufacturers, investors, and procurement professionals. Each group faces different priorities and time horizons, but all stand to benefit from a clear understanding of market dynamics and a proactive approach to positioning.
For Ingredient Manufacturers and Formulators
- Invest in application-specific value propositions. Differentiate beyond basic fiber content by demonstrating performance in target matrices, offering multiple formats, and providing technical support that reduces customer development time.
- Strengthen regulatory and clinical credibility. Proactively pursue regulatory recognition for new applications, maintain comprehensive safety documentation, and consider independent verification of functional claims to support differentiation and customer confidence.
- Build supply chain resilience. Evaluate feedstock sourcing options, consider forward contracting or diversification strategies, and assess how input cost volatility may affect margins under different scenarios.
For Investors and Strategic Capital Allocators
- Assess differentiation quality, not just scale. Evaluate companies based on their regulatory track records, clinical substantiation, application expertise, and ability to command premium positioning rather than volume alone.
- Monitor consolidation dynamics and capacity investments. Track which players are expanding capacity, entering new geographies, or securing certifications, as these moves often signal strategic intent and can reshape competitive balance.
- Consider downstream integration and partnership models. Opportunities may exist in companies that offer integrated solutions, co-development services, or distribution models that simplify sourcing for end-users, particularly as demand broadens across applications.
For Procurement and Sourcing Professionals
- Prioritize supply security alongside cost. Evaluate suppliers on feedstock flexibility, production capacity, quality certifications, and contingency capabilities, recognizing that input volatility can affect availability and pricing over time.
- Leverage application support in supplier selection. Suppliers that provide formulation guidance, technical service, and co-development resources can reduce time-to-market and improve product outcomes, adding value beyond the ingredient itself.
- Stay informed on regulatory and claim developments. Understanding evolving recognition status and certification options enables more confident product positioning and helps avoid compliance risks associated with unsupported claims.
Conclusion
The resistant dextrin market is at a point where fundamental demand drivers, regulatory progress, and technological capability are aligning to support sustained growth. The projected expansion through 2032 reflects not only increasing volume but also the broadening of applications and the deepening of competitive differentiation around evidence, format flexibility, and supply reliability. For stakeholders across the value chain, the path to capturing value lies in understanding these dynamics in detail and acting with strategic precision.
Aggregate market figures provide a useful baseline, but the real strategic complexity resides in segment-level dynamics, regional regulatory variations, application-specific performance requirements, and the evolving cost structure of feedstock supply. Accessing granular data on subsegments, competitive benchmarks, and scenario-based forecasts can materially improve decision quality, whether the objective is product development, capacity planning, investment allocation, or sourcing strategy. Deeper intelligence enables more confident navigation of a market that is simultaneously expanding and becoming more competitive.
For detailed analysis of this topic, please visit the official page: Resistant Dextrin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


