



Slurry Pump Market: Why Asia Pacific's Steady Growth Reshapes Global Dynamics

Strategic Horizons in the Global Slurry Pump Market: Navigating Growth, Innovation, and Competitive Shifts
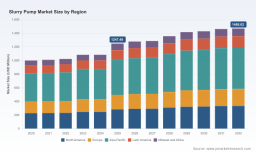
The slurry pump market stands at a pivotal intersection of industrial necessity and technological transformation. As heavy industries worldwide grapple with tougher materials, stricter efficiency mandates, and volatile supply chains, the demand for robust slurry handling solutions continues to evolve. Current projections indicate a moderate but steady expansion trajectory, with the market expected to grow from a base of approximately USD 1,247.48 million in 2025 to around USD 1,468.62 million by 2032, reflecting a compound annual growth rate of 2.5 percent. While this pace may appear subdued compared to high-growth technology sectors, it underscores a mature industry where value creation is increasingly driven by performance differentiation, lifecycle optimization, and regional demand shifts rather than volume alone.
Behind these headline figures lies a complex landscape shaped by contrasting regional dynamics, application-specific requirements, and a competitive field that blends established multinational players with specialized regional manufacturers. For executives, investors, and procurement leaders, understanding the forces reshaping this market is no longer optional—it is essential for capital allocation, product strategy, and operational resilience. This analysis examines the structural challenges defining the industry today, unpacks the core drivers of change, maps the competitive positioning of key players, and outlines the trends that will determine where value concentrates over the next five years.
Market Snapshot and Structural Challenges
The global slurry pump market has demonstrated resilience through a period of fluctuating industrial activity, with revenue figures climbing from roughly USD 1,000.0 million in 2020 to an estimated USD 1,247.48 million in 2025. This growth reflects sustained demand across mining, chemical processing, metallurgical operations, and construction applications, even as broader macroeconomic uncertainty and commodity price volatility tested capital expenditure cycles. The forecast period through 2032 suggests continued expansion, though at a pace that rewards operators who can navigate operational inefficiencies and supply chain constraints rather than simply chasing volume growth.
Several structural challenges are reshaping how companies approach slurry pump procurement and product development. First, the industry faces mounting pressure to balance durability with energy efficiency. Traditional heavy-duty designs have long prioritized wear resistance, but newer performance benchmarks now require hydraulic efficiencies in the 75 to 85 percent range, pushing manufacturers to rethink impeller geometries, casing designs, and material combinations. Achieving these targets without compromising reliability in abrasive or corrosive environments remains a persistent engineering hurdle.
Second, the supply chain for critical wear materials has emerged as a strategic vulnerability. High-chrome white iron alloys and specialized elastomers, which form the backbone of pump linings and internal components, are subject to intermittent shortages and price swings. For operators, this translates into unpredictable maintenance costs and longer lead times, while manufacturers must decide whether to vertically integrate material sourcing, diversify supplier networks, or redesign components to reduce dependency on scarce alloys. The cost dynamics are particularly pronounced for high-chrome variants, which can range from USD 0.50 to USD 1.50 per kilogram and directly influence the wear life expectancy of pump components deployed in mining circuits.
Third, regulatory and certification requirements are tightening across regions, compelling manufacturers to embed quality management and performance validation into their development processes. Compliance with standards such as ISO 9001:2015 and industry-specific hydraulic efficiency benchmarks is increasingly viewed as a baseline for market access, particularly in North America and Europe. Companies that treat certification as a 사후 consideration rather than a design parameter risk exclusion from tenders and long-term service contracts, especially in sectors where downtime costs far exceed equipment purchase prices.
Key Drivers Shaping Market Evolution
Technological Innovation and Material Science Breakthroughs
Innovation in slurry pump design is moving beyond incremental improvements to encompass material science, modular architecture, and application-specific customization. Manufacturers are investing in larger pump configurations tailored for high-flow decarbonization and carbon capture workflows, reflecting the broader industrial push toward emissions reduction. Simultaneously, advances in high-chrome iron alloys and wear-resistant elastomers are extending component lifespans in abrasive environments, reducing the frequency of rebuilds and lowering total cost of ownership for end users. Front pull-out shaft seal designs and gasite iron formulations are examples of engineering refinements that address leakage, maintenance accessibility, and metallurgical performance under extreme-duty conditions.
These technological shifts carry direct commercial implications. Manufacturers that can deliver pumps with demonstrably longer wear life and simpler maintenance procedures gain leverage in competitive bidding, particularly in mining and mineral processing where operational continuity is paramount. For buyers, the trend toward higher-efficiency and longer-life designs means a reevaluation of procurement criteria: upfront price is increasingly secondary to lifecycle cost, availability of replacement parts, and compatibility with existing plant infrastructure.
Policy and Regulatory Pressures
Regulatory frameworks are becoming a decisive factor in product adoption and regional market dynamics. Efficiency mandates and quality certification requirements are no longer optional benchmarks; they function as gatekeepers for participation in public tenders, large-scale infrastructure projects, and regulated industrial sectors. In the power generation and chemical industries, where slurry pumps handle hazardous or high-temperature fluids, compliance with stringent safety and performance standards directly influences vendor selection.
The policy environment also intersects with broader sustainability goals. As industries face increasing scrutiny over energy consumption and carbon footprints, pumps that contribute to lower power draw and reduced maintenance waste align with corporate environmental targets. This creates a dual incentive structure: manufacturers are compelled to design for efficiency and compliance, while end users are motivated to upgrade older, less efficient units to meet internal sustainability metrics and avoid regulatory penalties.
Demand-Side Shifts in Mining, Chemicals, and Industrial Processing
Demand patterns are being reshaped by the geographic redistribution of mining activity, the expansion of chemical processing capacity in emerging markets, and the modernization of aging industrial facilities in developed economies. Mining and mineral processing remain the largest application segment, driven by continuous extraction operations, tailings management requirements, and the need to handle increasingly abrasive ores. Chemical industry applications, meanwhile, demand pumps capable of managing corrosive slurries and precise flow control, pushing manufacturers to develop lined and specialized configurations that resist chemical degradation.
A notable demand-side shift is the growing preference for integrated service models. Operators are less interested in standalone equipment transactions and more focused on partnerships that include installation support, predictive maintenance tools, and rapid parts availability. This evolution reflects the reality that pump downtime in a mill circuit or chemical plant can cascade into significant production losses, making reliability and service responsiveness critical purchase criteria. Manufacturers that build service networks, digital monitoring capabilities, or modular replacement parts programs are positioning themselves to capture recurring revenue streams and deepen customer relationships.
Supply Chain Realignment and Cost Structure Dynamics
The cost structure of slurry pump manufacturing is undergoing recalibration as raw material volatility, regional production strategies, and logistics complexity intersect. Companies are responding by diversifying manufacturing footprints, expanding localized production capabilities, and investing in supply chain resilience. Recent capacity expansions in submersible pump manufacturing, supported by multi-million-dollar investments in North American facilities, illustrate how producers are aligning production capacity with regional demand centers to reduce lead times and mitigate freight cost fluctuations.
At the same time, the availability of specialty alloys and elastomers remains a wildcard. Price volatility in high-chrome materials forces manufacturers to make strategic trade-offs between component performance and cost predictability. Some are exploring alternative material formulations or hybrid lining designs that maintain wear resistance while reducing exposure to single-source suppliers. For the broader market, these supply chain adjustments influence not only product pricing but also the speed at which new models can be brought to market and the reliability of after-sales support.
PW Consulting
Competitive Landscape and Leadership Strategies
The slurry pump market exhibits moderate concentration, with the top three players accounting for approximately 28.5 percent of revenue and the top five collectively holding around 45.2 percent. This structure indicates a market where established leaders maintain strong positions through product breadth, technological pedigree, and global service networks, while regional specialists and niche manufacturers compete effectively in specific applications or geographies. The presence of both multinational firms and focused local players creates a dynamic environment where differentiation often hinges on application expertise, material science capabilities, and responsiveness to regional regulatory demands.
Leading manufacturers have carved distinct strategic identities. Sulzer has emphasized a comprehensive portfolio spanning heavy-duty horizontal and vertical configurations, with recent expansions targeting larger pump sizes for decarbonization and carbon capture workflows. Its investment in submersible manufacturing capacity in the United States reflects a deliberate push to align production with North American demand while reinforcing its value proposition around abrasion and corrosion resistance for mining and metals applications. KSB, through its GIW brand, has focused on extreme-duty mill circuits and tailings applications, leveraging high-chrome gasite iron and front pull-out shaft seal designs to address the most demanding operational environments. The phased North American rollout of its latest slurry pump series underscores a strategy of incremental market penetration supported by material and sealing innovations.
Slurry Tankers Market
In the Americas, Schurco Slurry and EDDY Pump have built reputations around heavy-duty horizontal and vertical centrifugal designs and high-solids handling capabilities, respectively. Schurco Slurry's focus on hard-rock mining and mineral processing, combined with a robust replacement parts offering, positions it as a practical choice for operators prioritizing uptime and component availability. EDDY Pump's emphasis on high-density, high-solids applications in mining, dredging, and wastewater highlights a niche-oriented approach that caters to specialized fluid handling requirements. Meanwhile, Kingda Pump Group has maintained a long-standing presence in engineered heavy-duty slurry and dredge pumps, with recent visibility at major industry exhibitions signaling continued engagement with mining and industrial end users in Latin America and beyond.
Chinese manufacturers such as Kingda Pump Group and Hebei Tobee Pump have expanded their footprint by offering warman-equivalent configurations across vertical, horizontal, and submersible categories, supported by full parts supply chains. This approach appeals to cost-conscious buyers and operators seeking compatibility with established pump standards while maintaining access to localized support. In parallel, companies like Goulds Pumps (ITT) and Metso continue to leverage their industrial scale and mineral processing expertise, offering extra-heavy-duty lined slurry pumps and specialized series tailored to mineral processing circuits.
The competitive landscape is also being shaped by targeted acquisitions and product-line expansions. The acquisition of a peristaltic slurry pump line by a European fluid handling specialist illustrates how firms are broadening their abrasive fluid handling portfolios to capture cross-industry demand, particularly in applications requiring gentle handling or precise dosing. Similarly, the launch of NSF/ANSI 61-certified surface pumps by a U.S.-based manufacturer reflects the growing importance of certification in water-related and regulated industrial applications, where compliance directly influences procurement eligibility.
Looking ahead, the market is likely to see continued consolidation among players seeking to expand geographic reach or application coverage, while specialized entrants may carve out niches in high-solids handling, hygienic processing, or region-specific service models. The differentiation frontier is shifting from pure equipment supply toward integrated solutions that combine material performance, efficiency certification, predictive maintenance tools, and rapid parts availability. Companies that can orchestrate these elements will be better positioned to defend margins and capture share in a market where volume growth alone does not guarantee profitability.
Future Trends and Commercial Opportunities (2026–2032)
Efficiency-Driven Product Refresh Cycles
As regulatory benchmarks and corporate sustainability targets tighten, a wave of equipment upgrades is expected across mining, chemical, and power generation facilities. Older slurry pumps with lower hydraulic efficiency and higher maintenance burdens will face replacement pressure, particularly in regions where energy costs are rising and downtime penalties are severe. This trend creates opportunities for manufacturers offering retrofits, high-efficiency replacements, and service programs that reduce the financial and operational barriers to upgrading. For investors, companies with strong aftermarket service networks and modular upgrade paths may benefit from recurring revenue tied to equipment refresh cycles rather than relying solely on new equipment sales.
Regional Demand Rebalancing and Localized Production
Demand is likely to continue shifting toward Asia Pacific and Latin America, driven by mining investment, infrastructure development, and industrial capacity expansion. In response, manufacturers will further localize production, service hubs, and parts distribution to reduce lead times and respond to regional procurement preferences. This geographic rebalancing presents commercial opportunities for firms that can establish credible local partnerships, navigate import and certification requirements, and offer culturally and operationally aligned support. However, it also introduces risk: companies that overinvest in regions with volatile commodity cycles or regulatory uncertainty may face underutilized capacity, while those that delay localization risk losing share to agile regional competitors.
Material Science and Wear Life as Competitive Differentiators
Advances in alloy formulations, elastomer technology, and lining designs will increasingly determine which manufacturers win in abrasive and corrosive applications. As high-chrome materials remain subject to price volatility and supply constraints, companies that develop alternative material strategies or secure stable supply relationships will gain a structural advantage. For end users, the commercial implication is clear: wear life longevity directly affects maintenance budgets and production continuity, making material performance a key evaluation criterion alongside initial price. Manufacturers that can provide verifiable wear life data, standardized testing results, and predictable replacement part availability will be able to command premium positioning in competitive tenders.
Strategic Recommendations for Decision Makers
For manufacturers and product developers, the priority is to embed efficiency, material resilience, and serviceability into the design phase rather than treating them as aftermarket enhancements. Investing in front pull-out seal architectures, high-chrome gasite iron options, and modular component designs can reduce maintenance friction and extend pump life in demanding circuits. At the same time, companies should evaluate supply chain exposure to critical alloys and elastomers, considering dual-sourcing strategies or alternative material formulations that preserve performance while reducing cost volatility. Building digital monitoring or predictive maintenance capabilities into pump offerings can further differentiate products in markets where operators value uptime and lifecycle cost transparency.
Worldwide Polishing Slurry Market
For investors, the slurry pump market rewards a selective approach that emphasizes companies with strong regional service networks, certification compliance, and application-specific expertise. Firms that combine equipment sales with aftermarket parts, rebuild services, and predictable lead times are better positioned to capture recurring revenue in a moderate-growth environment. Investment theses should also account for regional demand shifts: companies with credible footprints in Asia Pacific and Latin America, or those expanding localized production to serve these regions, may benefit from structural demand growth in mining and industrial processing. Conversely, exposure to single-region dependency or reliance on volatile raw material inputs without mitigation strategies warrants careful scrutiny.
For procurement leaders and plant operators, the buying decision should shift from lowest upfront price to total cost of ownership that accounts for wear life, energy consumption, parts availability, and service responsiveness. Evaluating manufacturers on their ability to provide certified efficiency performance, predictable rebuild schedules, and rapid parts fulfillment can reduce operational risk and avoid costly downtime. Where possible, procurement teams should seek standardized interfaces and compatibility with existing plant infrastructure to simplify future upgrades and minimize integration costs. Establishing long-term service agreements with manufacturers that demonstrate material science competence and regional support capacity can also stabilize maintenance budgets and improve equipment reliability over time.
The slurry pump market is entering a phase where competitive advantage will be defined less by scale alone and more by the ability to deliver technically differentiated, efficiently certified, and reliably supported solutions. As efficiency mandates tighten, material supply chains remain unpredictable, and demand continues to redistribute across regions and applications, organizations that act on these insights with disciplined product strategy, targeted regional investment, and lifecycle-focused procurement will be best positioned to capture value. For those seeking a deeper dive into segment-level dynamics, regional revenue distributions, and customized strategic scenarios, the full research report provides granular data and tailored recommendations to support precise decision-making.
For detailed analysis of this topic, please visit the official page: Slurry Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


