



Solar Cell Metal Paste Market: Why 6.5% CAGR and Asia Pacific Lead 2026-2032

Solar Cell Metal Paste Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
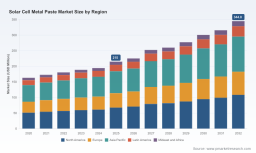
The solar cell metal paste market has demonstrated consistent growth over the past half-decade, evolving from a niche materials segment into a critical enabler of photovoltaic manufacturing efficiency. Revenue expanded from approximately 163.15 million USD in 2020 to 215.0 million USD in 2025, reflecting a compound annual growth rate of 6.5 percent. Projections indicate the market will continue its upward trajectory, reaching 344.8 million USD by 2032. This expansion is not merely a function of installed capacity growth; it is increasingly tied to technology transitions, material substitution debates, and the competitive dynamics of a fragmented supplier base.
At first glance, the growth narrative appears straightforward: more solar cells require more conductive pastes for front-side metallization and back-surface field formation. However, the structural reality is more nuanced. Manufacturing yield optimization, silver intensity reduction, and the shift toward next-generation cell architectures are reshaping how paste suppliers position themselves and how cell manufacturers evaluate material procurement. The market's resilience during periods of raw material volatility underscores both the strategic importance of metallization materials and the persistent tension between performance requirements and cost constraints.
Key Challenges and Inflection Points
Three structural challenges currently define the operating environment for solar cell metal paste participants and downstream manufacturers alike.
First, raw material cost exposure has intensified. Silver, the dominant conductive component in high-performance pastes, experienced unprecedented price appreciation, reaching approximately 121 USD per ounce in January 2026 before averaging around 81 USD per ounce through the year according to J.P. Morgan Global Research. Silver paste formulations can account for up to 30 percent of total solar cell production costs, making paste chemistry and silver-loading strategies a direct contributor to cell-level economics. This exposure forces manufacturers to balance efficiency gains against material input volatility.
Second, the technology transition from legacy crystalline silicon architectures toward TOPCon, heterojunction, and other advanced structures is disrupting paste specification requirements. Formulations optimized for PERC or standard multicrystalline platforms do not automatically translate to higher-efficiency architectures. Suppliers must invest in R&D to develop pastels that maintain adhesion, low contact resistance, and fire-through compatibility under altered thermal profiles and layer stack designs. This creates a divide between suppliers with formulation depth and those competing primarily on price.
Third, the competitive landscape remains structurally fragmented despite pockets of technological leadership. The market's concentration metrics reflect a diffuse supplier environment where differentiation is increasingly tied to application-specific engineering support, formulation customization, and supply reliability rather than commodity volume alone. This fragmentation presents both an opportunity for steady entrants and a risk for those unable to move beyond generic product positioning.
Key Drivers of Market Evolution
Technology Innovation and Formulation Breakthroughs
The most consequential driver of market growth is the simultaneous push toward higher cell efficiencies and lower silver consumption per watt. Advanced metallization pastes are being engineered to reduce sintering temperatures, improve line resistance uniformity, and enable thinner finger spacing without compromising collection efficiency. Formulations designed for PERC, TOPCon, and emerging n-type architectures are moving from qualification stages into volume production, and suppliers capable of delivering consistent performance across multiple technology platforms are capturing disproportionate share within high-value segments.
This technical trajectory intersects directly with silver-saving initiatives. Industry reporting from early 2026 highlighted accelerating efforts across the solar value chain to reduce silver intensity, with metallization paste optimization identified as one of the most actionable levers in cell cost structure. The implication for paste suppliers is clear: the next wave of market growth will not be awarded solely to those with the largest production footprint, but to those with the formulation agility to support lower-silver designs without eroding electrical performance.
Policy and Regulatory Momentum
Policy environments in major markets are reinforcing demand for high-performance photovoltaic materials. The European Union's target of a 40.5 percent renewable energy share by 2030 is driving sustained investment in solar deployment and, by extension, demand for high-performance silver-based pastes in advanced module manufacturing. In the United States, the Inflation Reduction Act has indirectly strengthened the economics of domestic and allied supply chains, encouraging producers to prioritize materials that meet quality, reliability, and traceability expectations for long-life assets.
China's policy stance further shapes the demand picture. Commitment to 20.5 percent non-fossil energy consumption by 2026 supports continued expansion in domestic solar cell production, creating a substantial internal market for both silver and aluminum-based metallization materials. These regulatory signals do not merely boost volume; they influence the premium attached to formulations that enable efficiency, yield, and long-term durability in increasingly competitive deployment economics.
PV Metallization Silver Paste Market
Demand-Side Shifts in Manufacturing Behavior
Cell and module manufacturers are increasingly treating paste selection as a systems-level optimization decision rather than a discrete consumable purchase. As production scales and fab economics tighten, buyers focus on total cost per watt, line yield, and compatibility with high-throughput screen printing or printing-and-fire processes. This behavioral shift advantages suppliers that offer not only material consistency but also process integration support, troubleshooting capability, and the ability to co-develop formulations tailored to specific line configurations.
At the same time, large-scale manufacturing is intensifying sensitivity to supply continuity. Volatility in precious metal markets and geopolitical supply considerations have elevated the importance of qualified secondary sources, regional availability, and inventory strategies. Manufacturers that once tolerated single-source dependency for specialized pastes are actively building supplier redundancy, changing how incumbents must compete against challengers.
Supply Chain and Cost Structure Dynamics
Cost structure pressures are reshaping how paste portfolios are built and priced. Silver price surges have accelerated interest in silver-aluminum hybrid designs, reduced-loading formulations, and aluminum paste alternatives where application constraints allow. At the same time, the cost of delivering advanced formulation performance is rising, as research, quality control, and application engineering become more essential to customer selection criteria.
This dynamic creates a dual pressure: manufacturers want lower input costs, while simultaneously demanding performance that enables next-generation cell economics. Suppliers that can articulate the trade-off between silver loading, fire-through behavior, and contact resistance in a way that maps to customer cost-per-watt calculations are gaining negotiating leverage, even in a price-sensitive environment.
Competitive Landscape and Leading Strategies
The supplier ecosystem spans established specialty material companies, electronics-paste incumbents extending into photovoltaics, and regional manufacturers competing on cost-performance balance. Ten companies illustrate the breadth of strategies currently shaping the market: Heraeus Photovoltaics, DuPont de Nemours, Inc., Giga Solar Materials Corporation, Targray Technology International Inc., Murata Manufacturing Co., Ltd., Hunan LEED Electronic Ink Co., Ltd., Shanghai Transcom Scientific Co., Ltd., Daejoo Electronic Materials Co., Ltd., Agfa-Gevaert N.V., and Noritake Co., Limited.
Strategic Positioning of Leading Players
Heraeus Photovoltaics has built a position around high-performance silver metallization pastes tailored for advanced cell architectures, including PERC, TOPCon, and n-type technologies. Its relevance in the current cycle stems from formulation depth and visibility into the industry's silver-saving agenda, where paste cost and silver intensity are recognized as material contributors to cell economics. The company's focus on architecture-specific formulations positions it well for customers transitioning away from legacy platforms.
DuPont de Nemours, Inc. brings brand recognition and an established Solamet product lineage optimized for high-efficiency solar cells, including PERC and advanced architectures. Its value proposition emphasizes performance consistency and integration with efficiency-focused manufacturing strategies, appealing to producers who prioritize reliability and wafer-level performance in premium segments.
Giga Solar Materials Corporation and Targray Technology International Inc. represent manufacturers emphasizing mass-production practicality. Giga Solar focuses on low-silver and high-efficiency formulations designed for volume fabrication, aligning product development with the industry's cost-reduction imperative while maintaining efficiency targets. Targray differentiates through customization of front- and rear-side conductive materials, aiming to improve yields and efficiency at the cell level rather than competing purely on raw material price.
Legacy electronics-paste expertise provides additional competitive angles. Murata Manufacturing Co., Ltd. and Noritake Co., Limited draw on long-standing electronic paste technology to develop silver pastes for solar cell electrodes, leveraging process know-how and material consistency from adjacent electronic markets. Agfa-Gevaert N.V. contributes specialized metallization paste capabilities for photovoltaic applications, reinforcing the view that metallization performance is increasingly a cross-industry competency.
Cost-Performance Challengers and Regional Dynamics
A parallel set of suppliers competes by narrowing the performance gap with international benchmarks while offering more attractive cost profiles. Hunan LEED Electronic Ink Co., Ltd. produces cost-effective high-temperature silver paste for solar cell electrodes and mass production applications, targeting volume-driven manufacturing environments where formulation reliability and price alignment are both critical. Shanghai Transcom Scientific Co., Ltd. offers competitive formulations with performance approaching international standards at lower cost points, reflecting the broader regional trend of maturing domestic material options.
Daejoo Electronic Materials Co., Ltd. occupies a differentiated position by supplying both silver and aluminum paste solutions for solar cell metallization, providing customers with alternative material paths where back-side or specific electrode requirements favor aluminum-based or hybrid approaches. This kind of portfolio breadth can be strategically valuable as manufacturers experiment with material combinations to manage silver exposure.
Evolution of the Competitive Structure
Market concentration remains relatively modest, with the top three players holding approximately 24.6 percent and the top five about 26.2 percent of revenue. This dispersion indicates that scale advantages exist, but they are not yet dominant enough to prevent specialized or regionally focused entrants from capturing meaningful share. The likely evolution is twofold.
On one side, consolidation pressure will persist among suppliers that lack formulation differentiation, application support, or cost discipline. In a segment where silver intensity, yield, and architecture compatibility directly affect customer economics, undifferentiated commodity positioning becomes increasingly vulnerable. On the other side, fragmentation will endure where regional demand growth, customization requirements, and multi-source procurement strategies create room for additional qualified participants. New entrants and expanding incumbents will need to demonstrate more than production capacity; they will need to show that their products improve total wafer-to-module economics under real factory conditions.
Forward-Looking Trends for 2026 to 2030
Trend One: Silver Intensity Reduction as a Core Design Constraint
Over the next several years, formulation strategies that reduce silver loading without sacrificing electrical performance are expected to become central competitive differentiators rather than optional enhancements. Silver price spikes have already drawn attention to paste cost as a share of total cell expense, and the structural incentive to lower material intensity will persist regardless of short-term price fluctuations. Suppliers able to deliver paste systems that support finer lines, lower contact resistance, and stable fire-through behavior at reduced silver content will align directly with manufacturer priorities.
The commercial opportunity lies in pairing material design with application engineering. Manufacturers will increasingly favor partners who can demonstrate how a formulation change affects not just paste price, but overall cell cost per watt, yield, and compatibility with future printing processes. This shifts competition from bulk pricing toward solution value.
Trend Two: Broader Adoption of Advanced Cell Architectures Driving Paste Specification Upgrades
As TOPCon, heterojunction-related variants, and other advanced architectures move further into mainstream production, metallization requirements will continue to diverge from legacy PERC-era norms. Paste suppliers that maintain a single product focus will face growing friction; those that invest in architecture-aware development and can validate performance across multiple platforms will secure stronger customer relationships. The trend increases the value of technical support, qualification speed, and repeatable scale-up of new formulations.
PW Consulting
For buyers, this trend means that paste selection will become more tightly coupled to fab technology roadmaps. For suppliers, it means that R&D cadence and customer co-development capability will increasingly determine growth potential, especially in regions scaling advanced-cell manufacturing capacity.
Trend Three: Regional Supply Resilience and Multi-Source Procurement as a Structural Shift
Policy support in Europe, the United States, and China is expanding regional manufacturing ambitions, and with that expansion comes greater attention to supply security. Even where global trade remains fluid, manufacturers are incentivized to qualify multiple paste sources, diversify regional availability, and reduce exposure to single-supplier risk for critical materials. This shift favors suppliers with reliable production footprints, transparent quality systems, and the ability to support localized qualification timelines.
The opportunity here is less about displacing incumbents and more about earning qualified status as a reliable secondary or primary source in specific regions or product lines. Suppliers that can combine competitive formulation performance with dependable delivery and regional responsiveness will find expanding procurement interest, particularly among manufacturers building or expanding capacity in policy-supported markets.
Risks and Uncertainties
The forward outlook is contingent on several variables. Silver price volatility remains a persistent risk; sustained high prices could accelerate aluminum-based substitution in applications where performance trade-offs are acceptable, altering demand patterns for silver-dominant paste portfolios. Conversely, if silver prices moderate sharply, cost pressure may ease in the short term but the structural incentive to reduce intensity is unlikely to disappear, given the broader focus on cell-level cost optimization.
Technology adoption rates also introduce uncertainty. The pace at which TOPCon and other advanced architectures scale relative to legacy lines will determine how quickly paste specifications must evolve and how rapidly formulation-dependent suppliers can capture premium demand. Slower-than-expected transitions would extend the relevance of mature formulations but could also delay the demand uplift associated with higher-efficiency architectures. Finally, policy trajectories could shift with political or economic changes, altering the timing and geography of demand expansion.
Actionable Guidance for Decision Makers
For Solar Cell and Module Manufacturers
Treat paste selection as a cost-per-watt optimization problem rather than a commodity procurement decision. Evaluate suppliers based on formulation performance under your specific process conditions, silver-loading flexibility, support for next-generation architectures, and ability to maintain lot-to-lot consistency at production scale. Building qualified multi-source relationships for critical formulations can reduce supply risk while preserving performance standards.
Solder Paste Market
At the same time, use material selection as a lever in your silver-intensity strategy. Where performance allows, collaborate with paste suppliers to test reduced-loading or silver-aluminum hybrid options, measuring impact not just on material cost but on firing yield, contact resistance, and overall cell efficiency. The most valuable partnerships will be those that tie material development directly to fab economics.
For Investors and Strategic Planners
Focus on suppliers whose competitive advantage rests on formulation depth, application support, and architecture adaptability rather than volume alone. In a 6.5 percent CAGR market extending through 2032, growth will increasingly accrue to participants that can align product development with silver-reduction strategies and advanced cell transitions. Companies with credible customization capability, credible qualification pipelines, and the ability to serve both cost-sensitive and efficiency-focused segments are better positioned than those competing purely on price.
Pay attention to the interplay between raw material cycles and product strategy. Sustained silver price pressure is likely to reinforce demand for lower-silver formulations, hybrid designs, and aluminum alternatives in certain applications, expanding the strategic relevance of suppliers that can address this spectrum. Monitoring regional capacity expansion, especially in policy-supported markets, offers early signals about where demand growth and supplier qualification activity will intensify.
For Procurement and Supply Chain Leaders
Prioritize qualification readiness and supply resilience. The cost of line downtime, yield variation, or delayed qualification can outweigh marginal material savings, particularly in high-throughput manufacturing environments. Maintain a structured qualification pipeline for alternative formulations, document performance trade-offs clearly, and align sourcing strategy with your technology roadmap so that paste decisions do not become constraints when architecture transitions accelerate.
Negotiate with an understanding of total value rather than unit price alone. Where suppliers can demonstrate measurable improvements in yield, process stability, or compatibility with lower-silver designs, those benefits may justify a premium that is more than offset by reduced cell-level cost. Structured evaluation frameworks that capture electrical, mechanical, and process metrics will support better sourcing outcomes over time.
Conclusion
The solar cell metal paste market is entering a phase where growth and differentiation are increasingly inseparable. Revenue expansion toward 344.8 million USD by 2032 reflects not only rising deployment but also the intensifying importance of metallization materials in enabling higher efficiency, lower silver intensity, and more resilient manufacturing economics. Suppliers that treat formulation performance, architecture compatibility, and application engineering as core strategic assets will be better positioned to capture value in a fragmented but increasingly demanding landscape.
For manufacturers, investors, and procurement leaders alike, the practical imperative is to look beyond unit prices and short-term price cycles. The most consequential decisions will involve how paste selection supports cost-per-watt objectives, how quickly suppliers can adapt to technology transitions, and how effectively sourcing strategies balance performance with supply resilience. For organizations seeking detailed segmentation data, company-specific assessments, and region-level commercial context to inform those decisions, a full research report can provide the structured depth needed to translate market trends into targeted execution plans.
For detailed analysis of this topic, please visit the official page: Solar Cell Metal Paste Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


