



Petroleum Resin Market: Why 5.88% CAGR and Asia Pacific Reshaping It

Navigating the Petroleum Resin Market: Strategic Trends and Commercial Opportunities Through 2032
The petroleum resin market is entering a phase of measured expansion, characterized by steady demand growth, evolving regulatory pressures, and a competitive landscape that rewards product differentiation over volume alone. Current market sizing places the sector at approximately 218.7 million USD in 2025, with a projected trajectory toward 322.6 million USD by 2032. This growth path reflects a compound annual growth rate of 5.88% across the 2026–2032 forecast window, building on a historical expansion pattern that saw the market move from 185.1 million USD in 2020 through a series of incremental annual gains. The trajectory is not uniform, however. Growth is being reshaped by feedstock volatility, tightening emissions standards, and shifting end-user requirements that are quietly redefining which resin grades will capture premium value in the next cycle.
Rosin Resin Market
For decision-makers, the immediate takeaway is that the market is large enough to support multiple business models but narrow enough that margin capture depends heavily on grade specialization, regional positioning, and compliance readiness. The industry remains moderately consolidated, with the top three players accounting for roughly 29.5% of revenue and the top five reaching approximately 36.8%. This concentration leaves substantial room for localized competitors, niche formulators, and integrated feedstock players to compete on service, technical support, and application-specific performance rather than scale alone.
Key Challenges and Inflection Points
Three structural challenges are currently re-shaping strategic planning across the petroleum resin value chain.
Feedstock exposure and margin sensitivity remain a persistent pressure point. Naphtha-derived C5 and C9 fractions form the backbone of most hydrocarbon resin synthesis routes, and pricing swings in crude oil and naphtha markets transmit quickly into producer cost structures. Because resin grades are often priced against performance benchmarks rather than raw input costs, suppliers with limited hedging flexibility or narrow product portfolios face disproportionate margin compression during volatile periods. The implication is that cost leadership alone is becoming less durable; resilience is increasingly tied to feedstock diversification, integration depth, and the ability to shift production toward higher-margin grades when input costs rise.
Regulatory tightening on emissions and aromatic content is altering the competitive balance between conventional and hydrogenated resins. In adhesive and coating applications, regulatory direction is favoring products with lower volatile organic compound profiles and reduced aromatic residuals. This shift is not merely a compliance issue; it influences formulation choices, customer qualification cycles, and the willingness of converters to standardize on specific resin families. Companies that have already invested in hydrogenation capacity or water-white grade portfolios are positioned to benefit from a transition that will otherwise raise reformulation costs for slower-moving competitors.
Demand fragmentation across end-use sectors is making blanket capacity plays riskier. Growth is not coming from a single application category but from a mix of adhesive systems, rubber compounding, road-marking and industrial coatings, and packaging-related ink and film applications. Each segment has distinct performance requirements, qualification timelines, and price sensitivity. As a result, the market is moving toward a model where revenue growth depends on aligning resin grades with specific technical needs rather than selling generalized intermediates into undifferentiated demand.
Key Drivers Shaping the Market Trajectory
The 5.88% CAGR projected through 2032 reflects a convergence of technical, regulatory, and demand-side forces. Understanding how these drivers interact is essential for identifying where value will accumulate.
- Technology innovation and grade specialization continue to be central to competitive differentiation. Hydrogenated and water-white resins represent a clear example of how processing sophistication translates into market access. By reducing color bodies and residual aromatics, these grades open doors to packaging, hygiene, and high-visibility coating applications that conventional fractions cannot easily serve. At the same time, modification strategies that blend C5, C9, and copolymer architectures are enabling formulators to balance tack, compatibility, and thermal stability more precisely. Innovation is therefore not only about new molecules; it is about creating grades that solve formulation constraints in high-value applications.
- Policy and regulatory environments are accelerating product migration toward cleaner profiles. Rules governing VOC limits, aromatic compound scrutiny, and food-contact extractables are progressively raising the bar for resin selection in adhesives and packaging-adjacent uses. This environment favors producers with ready access to fully hydrogenated options and those capable of documenting compliance across multiple jurisdictions. It also encourages downstream converters to consolidate their supplier base around partners who can provide consistent regulatory documentation and predictable grade performance.
- Demand-side shifts in adhesives and industrial applications are expanding the addressable market for specialized resins. Hot-melt and pressure-sensitive adhesive systems remain significant demand anchors, but the broader story is the continued push toward lighter-weight assemblies, faster processing speeds, and Bondline performance optimization in manufacturing. In parallel, road-marking and industrial coatings demand is supported by infrastructure maintenance cycles and the need for durable, visible markings. These end-use trends reward resin suppliers who can align grade characteristics—such as tack build, openness, and weatherability—with real processing conditions rather than generic specification sheets.
- Supply chain and cost structure changes are reshaping regional competitiveness. Feedstock sourcing, logistics, and local availability of C5/C9 streams influence both cost position and supply reliability. Regions with stronger integration between petrochemical feedstock production and resin manufacturing can respond more flexibly to demand changes and margin pressure. Meanwhile, transportation costs and qualification lead times are reinforcing the value of regional supply relationships, particularly where converters prioritize consistent batch performance and shorter response cycles over marginal price differences.
Recent company-level developments illustrate how these drivers are being addressed in practice. Capacity expansions are being pursued in response to rising global demand for adhesive and coating applications, signaling that at least some major players see sustained volume growth as worth the capital commitment. At the same time, certification and feedstock-innovation moves are becoming part of the differentiation conversation. Notably, ISCC PLUS certification has been achieved at a key production facility for sustainable resin production, and resin derived from used cooking oil has been supplied to an affiliate for synthetic rubber production. These moves point to a market in which sustainability credentials and alternative feedstock pathways are increasingly tied to commercial access, especially where downstream customers are under pressure to document lifecycle and sourcing improvements.
Competitive Landscape and Leading Strategies
The competitive field spans large multinational producers, regional specialists, and application-focused formulators. Strategic positioning varies by feedstock access, hydrogenation capability, geographic footprint, and the depth of technical support offered to converters.
Among the prominent players, a clear divide is emerging between companies competing primarily on broad product breadth and those building advantage around hydrogenated grades, sustainable supply claims, or application-specific modification expertise. Producers with established hydrocarbon resin brands spanning C5, C9, and copolymer lines are leveraging name recognition, global distribution, and long-standing customer qualification relationships. Their challenge is to maintain relevance as end-users increasingly prioritize emissions performance, food-contact compliance, and consistent color quality in sensitive applications.
Hydrogenated resin specialists and producers with water-white portfolios are positioned to capture premium demand where aromatic residuals or color limitations would otherwise restrict material choice. In adhesive and coating grades, the ability to deliver low-color, low-odor, and low-VOC profiles is becoming a commercial advantage rather than a niche feature. This is especially relevant as regulatory expectations tighten and as packaging and hygiene-adjacent applications expand their material requirements.
Regional and China-based producers continue to play an important role in supplying C5 aliphatic, C9 aromatic, and C5/C9 copolymer resins to cost-conscious and volume-driven segments. Their strategic advantage often lies in feedstock proximity, manufacturing scale in specific resin families, and the ability to serve regional adhesive, coating, and rubber compounding markets with shorter supply lines. The key question for these players is whether they can move up the value chain into higher-specification grades without losing cost competitiveness, and whether they can build the documentation and certification infrastructure that multinational converters increasingly require.
The landscape is evolving along several axes. Integration is deepening where feedstock security and conversion efficiency matter most, allowing producers to protect margins during naphtha price swings. Differentiation is intensifying around hydrogenation, modification, and certification, as customers use compliance and performance criteria to narrow their approved supplier lists. New entry and regional specialization remain viable where local demand growth, logistics advantages, or application knowledge create a defensible position, even if global scale is limited. Overall, the market is not trending toward a single dominant model; it is trending toward a segmented structure in which success depends on matching the right grade, the right compliance profile, and the right service model to a specific customer segment.
Future Trends and Commercial Implications
Looking across the 2026–2032 horizon, several trends are likely to define where growth and margin will concentrate.
- Hydrogenated and low-aromatic resins will capture a growing share of high-value demand. As VOC limits tighten and aromatic scrutiny increases, converters in adhesive and coating applications will continue shifting toward fully hydrogenated options that simplify compliance and reduce reformulation risk. This trend favors producers with existing hydrogenation capacity and those able to supply consistent water-white grades at scale. The commercial opportunity lies not just in selling a different resin, but in helping customers qualify faster, reduce audit burden, and standardize on grades that meet multiple regulatory regimes simultaneously.
- Sustainable feedstock and certification pathways will become more commercially meaningful. ISCC PLUS certification and the use of alternative feedstocks such as used cooking oil are moving from pilot-stage signals to operational reality in certain production lines. While these pathways are unlikely to replace conventional naphtha-based synthesis across the board, they will become increasingly important in customer segments where sustainability documentation influences sourcing decisions. The opportunity here is for producers to build credible, auditable supply chains that can support customer claims without overpromising on volume or cost.
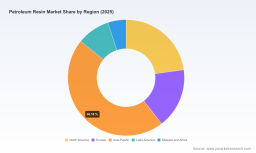
- Regional demand growth will reward localized grade portfolios and technical service. Asia Pacific remains a major demand center, but growth is also emerging from infrastructure-related coatings, packaging-adjacent inks and films, and adhesive-intensive manufacturing in multiple regions. In this environment, global product lists matter less than regional readiness: the ability to supply the right grade mix, maintain reliable batch consistency, and provide formulation support in local markets. Producers who can combine product breadth with regional responsiveness are more likely to secure long-term converter relationships than those competing on price alone.
These trends are not without risk. Feedstock volatility can still erode margins quickly, especially for producers with limited hedging or integration. Regulatory change may accelerate faster in some jurisdictions than others, creating uneven compliance costs and fragmented qualification requirements. In addition, overinvestment in generalized capacity could lead to oversupply in commoditized grades while leaving high-specification segments underserved if capital is not directed toward hydrogenation, modification, or certification capabilities. The most resilient strategies will be those that treat these risks as reasons to specialize rather than reasons to retreat.
Strategic Actions for Decision-Makers
The market outlook suggests a period in which disciplined positioning will matter more than aggressive volume chasing. The following actions are most relevant for different roles in the value chain.
PW Consulting
For Manufacturers and Producers
- Prioritize grade portfolios that align with regulatory direction and high-value applications, particularly hydrogenated, water-white, and low-aromatic options where qualification cycles are shortening and customer scrutiny is rising.
- Strengthen feedstock resilience through integration, diversification, or supply agreements that reduce exposure to naphtha price swings, and consider how alternative feedstock pathways can support both cost flexibility and sustainability positioning.
- Invest in technical service and application support as a competitive lever, since converter decisions are increasingly driven by formulation reliability, consistency, and documentation as much as by resin price.
For Investors and Capital Allocators
- Focus on companies with clear differentiation in hydrogenated or specialized grades, credible certification and compliance infrastructure, and the ability to serve high-margin adhesive, coating, and packaging-adjacent demand rather than solely competing in commoditized segments.
- Evaluate feedstock exposure and regional positioning as risk factors, since margin durability will depend on how well companies can manage naphtha-linked volatility and serve demand centers with reliable supply and short response times.
- Watch for consolidation and capability acquisition activity, particularly where smaller producers hold desirable grade expertise, regional relationships, or certification assets that larger players need to expand into premium segments.
For Procurement and Supply Chain Leaders
- Diversify approved supplier lists deliberately between broad-line suppliers and specialists, so that compliance requirements, color/aromatic constraints, and supply continuity can be managed without overrelying on a single source for critical grades.
- Include regulatory readiness, documentation quality, and feedstock sustainability credentials in sourcing evaluations, especially where future VOC limits, aromatic scrutiny, or food-contact requirements could affect qualification and reformulation risk.
- Engage early with suppliers on grade development and qualification timelines, since the market is shifting toward custom-fit solutions where early collaboration can reduce switching costs and protect production schedules.
The strategic picture is clear enough to act on, but the details matter. Market-wide sizing and growth rates provide the backdrop, while the real opportunities are embedded in grade-level demand shifts, regional feedstock dynamics, certification status, and the ability to meet tightening regulatory expectations without sacrificing performance. For organizations that need a sharper view of segment-level volume patterns, regional share dynamics, price/cost sensitivity, and company-level positioning, a more detailed research package can provide the granularity required to translate these trends into concrete sourcing, investment, and product decisions.
C9 Petroleum Resin Market
For detailed analysis of this topic, please visit the official page: Petroleum Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


