



Chicory Market: Why 7.9% CAGR and $496.7M by 2032 Redefine Growth

Navigating the Chicory Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global chicory market is entering a phase of structural acceleration, driven by converging forces in functional nutrition, regulatory clarity, and regionalsupply chain realignment. With a market valuation reaching approximately USD 300 million in 2025 and a projected compound annual growth rate of 7.9 percent through 2032, the sector is transitioning from a niche botanical commodity to a strategically important ingredient in food, beverage, and wellness formulations. For executives, investors, and procurement leaders, the window to shape positioning is narrowing as competitive dynamics tighten and consumer-facing applications multiply.
Understanding where value will concentrate requires looking beyond aggregate growth figures. The market is being reshaped by ingredient innovation, regulatory approvals that unlock new use cases, shifting demand from discretionary wellness to everyday functional consumption, and supply-side restructuring around raw material sourcing and extraction economics. This analysis maps the forces at play, profiles the competitive landscape, and outlines actionable implications for business leaders evaluating chicory-related investments or ingredient strategies.
Current Market Landscape and Core Challenges
The chicory market has sustained steady expansion over the past five years, with revenue trajectories reflecting consistent demand growth across food, beverage, and dietary supplement channels. The upward momentum is expected to continue through the forecast period, supported by broader consumer interest in plant-based fibers, prebiotic ingredients, and coffee-alternative formats. Growth is not uniform across value pools, however. Different segments are maturing at different speeds, and the pace of commercialization depends heavily on regulatory status, formulation compatibility, and end-market adoption cycles.
Several structural challenges are defining the market's next chapter.
Raw Material Geography and Climate Exposure
Chicory root production is geographically concentrated, with Northern Europe historically serving as a core sourcing region for inulin and related functional ingredients destined for global markets. This concentration creates vulnerability to weather variability, crop yield fluctuations, and logistics disruptions. Companies that depend on a narrow supplier base face quality consistency risk and cost volatility, particularly when demand spikes or input costs rise. Diversifying sourcing geographies, building contractual resilience, and investing in yield optimization are becoming pragmatic priorities rather than optional supply chain enhancements.
Regulatory Fragmentation Across Use Cases
The commercial pathway for chicory-derived ingredients varies significantly by application and jurisdiction. Certain forms of chicory root powder and extracts have cleared regulatory thresholds for use in bakery products, beverages, cereals, and grain-based items, with inclusion levels spanning a wide range. Chicory extract has also gained recognition as a color additive, flavor enhancer, and flavoring agent in specific contexts. Meanwhile, native chicory inulin has been evaluated and authorized in select markets as a functional ingredient and, in some regions, under novel food frameworks. These approvals create opportunity, but they also introduce complexity: formulation teams must navigate differing inclusion limits, claim language, and market-specific compliance requirements, which can slow product launches and add cost to regulatory navigation.
Functional Positioning Versus Commmodity Pressure
Chicory is increasingly positioned around functional benefits such as prebiotic fiber content and digestive wellness, yet it also competes in price-sensitive commodity channels where chicory root is used as a bulk ingredient or coffee extender. This dual identity creates strategic tension. Premiumization requires demonstrated efficacy, taste performance, and clean-label compatibility, while commodity-oriented channels pressure margins and incentivize scale. Companies must decide whether to compete on functional differentiation, cost efficiency, or a hybrid model that segments product lines by application and customer type.
Key Drivers Shaping Market Trajectory
Four interconnected drivers are accelerating market evolution and creating pockets of differentiated opportunity.
Ingredient Innovation and Extraction Technology
Technological progress in extraction, fractionation, and formulation is expanding the range of chicory-based inputs available to manufacturers. Advances in processing chicory root into soluble forms, standardized extracts, and functional inulin variants are enabling better taste masking, texture control, and label flexibility. These improvements matter because chicory is often used in categories where organoleptic performance is critical, such as coffee blends, flavored beverages, and baked goods. As ingredient formats become more versatile, the addressable market widens beyond traditional root-based applications and into newer functional food and supplement formats.
Regulatory Progress Opening New Use Cases
A series of regulatory determinations is reducing uncertainty and expanding the commercial menu for chicory ingredients. Recent determinations have supported chicory root powder in bakery products, beverages, cereals, and other grain products at defined inclusion levels. Separate determinations have positioned chicory extract as a color additive, flavor enhancer, and flavoring agent. In parallel, native chicory inulin has been evaluated and authorized in select frameworks, including recognition as a novel food in some regions and scientific assessment by European food safety panels. Collectively, these developments reduce formulation risk and give developers more confidence to build chicory into mainstream products rather than limiting it to niche or premium-only offerings.
Demand-Side Shift Toward Everyday Functional Consumption
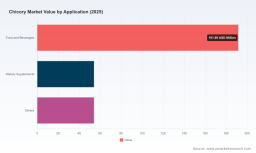
Consumer behavior is moving from occasional wellness purchases toward routine integration of functional ingredients into daily diets. Fiber and prebiotic content remain relevant purchase drivers, and chicory fits naturally into this narrative because it can be incorporated into familiar formats such as coffee alternatives, cereals, snacks, and beverages. Importantly, the demand story is not only about supplements. Food and beverage applications continue to represent the largest demand pool, reflecting the ingredient's flexibility and compatibility with everyday consumption occasions. This shift encourages manufacturers to pursue shelf-stable, mass-reachable products instead of relying solely on specialty channels.
Supply Chain Realignment and Cost Structure Pressures
The chicory value chain is undergoing reconfiguration as processors and ingredient companies respond to raw material availability, processing efficiency, and export dynamics. Several producers in India, for example, have built export-oriented operations spanning dried chicory roots, roasted chicory, liquid chicory, and extracts, targeting both coffee blends and nutraceutical markets. At the same time, large-scale ingredient suppliers in North America and Europe continue to emphasize chicory-derived inulin and functional ingredients for food, beverage, and nutraceutical uses. These parallel supply models create both competition and collaboration opportunities. Cost structures are influenced by root quality, drying and roasting methods, extraction yields, and logistics, meaning that margin management increasingly depends on process optimization and sourcing strategy as much as on end-market pricing power.
PW Consulting
Competitive Landscape and Leading Strategies
The chicory market remains moderately fragmented, but competitive positioning is sharpening as participants define clearer boundaries around geography, product format, and end-market focus. Market concentration is not extreme, and the presence of multiple regional processors alongside global ingredient suppliers creates a landscape where differentiation is achievable through specialization rather than scale alone.
Worldwide Fondant Market
Differentiated Positioning Among Established Players
Several companies illustrate how participants are carving out defensible positions.
-
Leroux has built its identity around roasted chicory products, including grains, ground chicory, liquid chicory, and soluble forms for beverages and culinary uses, anchored by a fully French supply chain. The emphasis on origin, roasted formats, and culinary compatibility positions the company in a premium, taste-driven segment where provenance and product consistency matter.
-
Cargill Incorporated leverages scale and ingredient science to produce chicory-derived inulin and functional ingredients for food, beverage, and nutraceutical applications. Its strategic advantage lies in formulation breadth, regulatory and technical support capabilities, and the ability to integrate chicory inputs into larger ingredient portfolios serving multinational customers.
-
Starwest Botanicals focuses on organic chicory root, powder, and extracts for herbal and food ingredient uses. Its positioning targets clean-label, organic, and botanical channels, appealing to buyers who prioritize certification, traceability, and ingredient transparency.
-
Indian processors such as Vashila Industries, Jamnagar Chicory Industries, Pioneer Chicory, Farmvilla Food Industries, and Nature's Gold Production illustrate a robust export- and domestic-oriented ecosystem spanning dried roots, roasted chicory, liquid chicory, cubes, and extracts. These companies compete on cost efficiency, volume supply, and versatility across coffee-blend, food, and nutraceutical channels, often serving as important nodes in global distribution networks.
-
European and UK-based distributors such as Organic Herb Trading Co support the market by supplying organic chicory and related botanicals, reinforcing the importance of distribution networks that connect processors with end users seeking specialty or certified materials.
Strategic Themes Across the Landscape
Across these profiles, several strategic themes emerge.
-
Format specialization is a common differentiator. Some players concentrate on roasted and culinary forms, others on extracts and inulin-type ingredients, and others on organic or herbal-grade materials. This segmentation reduces direct head-to-head competition and allows firms to build reputations around specific customer needs.
-
Supply chain origin is increasingly part of the value proposition. Fully domestic supply chains, regional sourcing clusters, and certification pathways are used to signal quality, consistency, and traceability. In a market where raw material geography matters, origin can support price premiums and customer loyalty.
-
Application breadth versus depth creates different risk-return profiles. Broad-line ingredient suppliers can cross-sell across categories and capture more of the value chain, while focused producers can deepen expertise and serve niche channels more effectively. Both approaches can succeed, but they require different capabilities in regulatory support, technical service, and operational scalability.
Market Evolution Outlook
The competitive landscape is likely to evolve through selective consolidation, entry by ingredient-focused players, and rising importance of technical service and regulatory navigation. As use cases expand, buyers will increasingly value partners that can support formulation, compliance, and scale simultaneously. At the same time, regional processors with strong export capabilities and cost advantages are well placed to capture share in price-sensitive and volume-driven segments. The result is a market where multiple business models can coexist, but where advantage will increasingly depend on execution quality, regulatory readiness, and the ability to match ingredient formats to end-market demand.
Forward-Looking Trends and Commercial Opportunities
Looking ahead three to five years, three trends are particularly consequential for strategic planning.
Expansion of Chicory in Everyday Food and Beverage Formats
Chicory is poised to move further into everyday consumption occasions as formulators leverage soluble forms, roasted formats, and functional extracts to improve taste and texture in mainstream products. Coffee alternatives, fortified cereals, snack applications, and flavored beverages represent channels where chicory can gain incremental share through familiar formats and added functional appeal. The commercial opportunity lies in building product architectures that combine functional messaging with sensory performance, enabling chicory to compete in categories with high purchase frequency rather than remaining confined to specialty wellness niches.
Inulin and Prebiotic Fiber as a Growth Anchor
Inulin-type ingredients derived from chicory continue to benefit from sustained interest in digestive health and fiber enrichment. Scientific evaluation and regulatory recognition in multiple markets support broader adoption, while manufacturing advances make it easier to incorporate these materials into diverse matrices. Growth is likely to be strongest where suppliers can provide consistent quality, clear application guidance, and compliance support. For ingredient companies, the strategic priority is to strengthen technical documentation, customer education, and formulation expertise so that chicory-based inulin becomes a default option in fiber-enrichment projects rather than one option among many.
Cobalt Market
Regional Supply Chain Diversification and Value-Added Processing
The market is likely to see continued diversification in sourcing and processing footprints as participants seek to reduce exposure to concentrated supply regions and capture more value locally. This includes expansion of drying, roasting, extraction, and blending capabilities in key production and export markets, as well as closer partnerships between processors and end-user manufacturers. The opportunity is twofold: buyers can improve resilience and cost predictability by broadening supplier relationships, while processors can differentiate through higher-margin value-added formats rather than competing solely on raw root volume.
Risks and Uncertainties to Monitor
Several factors warrant caution. Input cost volatility and crop variability can pressure margins and disrupt supply continuity. Regulatory complexity across jurisdictions may slow product development or limit claim language in certain markets. Taste and formulation challenges remain relevant in sensitive applications, where performance trade-offs can affect repeat purchase and shelf presence. In addition, competition from alternative fibers, botanical ingredients, and coffee extender substitutes could compress pricing in specific segments. Companies should scenario-plan around these variables and maintain flexibility in sourcing, formulation, and market prioritization.
Strategic Implications for Decision-Makers
The chicory market presents a clear value proposition for leaders willing to align ingredient strategy with application realities and regulatory pathways. The following recommendations are oriented by role.
For Manufacturers and Ingredient Developers
-
Prioritize format-to-application fit. Select roasted, soluble, extract, or inulin-type inputs based on the intended end use, taste requirements, and label goals rather than sourcing by commodity alone. Matching format to application reduces reformulation risk and improves speed to market.
-
Build regulatory and technical support into the commercialization plan. Because inclusion levels, claim opportunities, and compliance expectations differ across markets and product categories, early attention to regulatory status and application guidance can shorten launch timelines and reduce rework.
-
Strengthen supply resilience through diversity and process control. Multi-region sourcing, quality consistency protocols, and processing optimization help mitigate raw material volatility and support margin stability in volume-driven programs.
For Investors
-
Focus on differentiation that compounds over time. Businesses with clear positioning around organic certification, origin credibility, extraction capability, or application expertise are better placed to defend margins than undifferentiated bulk suppliers.
-
Evaluate end-market mix carefully. Exposure to everyday food and beverage channels can provide scale and repeatability, while specialty wellness channels may offer higher unit value but more volatile demand. Understanding the balance between these pools is essential for modeling growth and risk.
-
Watch for consolidation signals and partnership-driven expansion. As use cases broaden, value may migrate toward players that can combine supply reliability, technical service, and regulatory navigation, whether through organic build-out or strategic combinations.
For Procurement and Sourcing Leaders
-
Expand and qualify the supplier base beyond single-region dependence. Diversification across geographies and processing models improves continuity and gives procurement teams more negotiating leverage in volatile conditions.
-
Assess total cost beyond unit price. Processing method, certification requirements, consistency, lead times, and technical support all affect landed value and downstream performance. Evaluating these factors holistically supports better category decisions.
-
Align specifications with application needs early. Defining required formats, inclusion tolerances, and quality parameters before sourcing reduces the risk of mismatched materials and accelerates downstream formulation work.
The strategic picture is clear: chicory is no longer a narrow botanical input but a versatile ingredient set with expanding regulatory support, growing functional relevance, and a competitive landscape that rewards specialization and execution quality. Organizations that act early to define their positioning, secure resilient supply, and align formulation strategy with the strongest end-market opportunities will be best placed to capture value as the market moves toward 2032. For those seeking deeper segmentation data, company-level benchmarking, and tailored scenario analysis, a comprehensive research report can provide the detailed evidence base needed to convert these directional insights into precise commercial decisions.
For detailed analysis of this topic, please visit the official page: Chicory Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


