



Hyaluronic Acid Dermal Fillers: Beyond 8.1% CAGR, Who Wins in 2032?

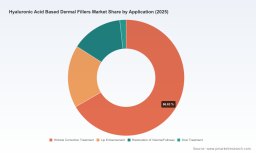
The Hyaluronic Acid Dermal Fillers Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for hyaluronic acid-based dermal fillers has transitioned from a period of rapid, broad-based expansion to a more nuanced phase defined by regulatory maturation, technological differentiation, and shifting consumption patterns. Valuation data indicates the market reached approximately USD 4,803.0 million in 2025, up from roughly USD 3,599.7 million in 2020, reflecting sustained demand across both established and emerging cosmetic and medical indications. Forward projections place the market at USD 5,163.21 million in 2026 and suggest a trajectory toward USD 8,210.0 million by 2032, corresponding to a compound annual growth rate of 8.1 percent over the forecast window. This growth profile is notable not merely for its magnitude, but for what it reveals about the underlying dynamics: the category is expanding at a pace that outstrips general healthcare markets, yet it is doing so within an increasingly structured regulatory and competitive environment that rewards precision, compliance, and portfolio depth.
Interpreting these figures requires moving beyond aggregate size and focusing on the forces that will determine which participants capture value. The market is large enough to accommodate multiple strategies, but fragmented enough that positioning matters. High concentration among top players, regional disparities in adoption and reimbursement, and rapid innovation cycles in formulation and manufacturing are reshaping the competitive rules. For executives and investors, the central question is no longer whether the category will grow, but where the growth will accrue and what capabilities will be required to participate profitably.
Market Context and Structural Challenges
The hyaluronic acid dermal filler category sits at the intersection of aesthetic medicine, minimally invasive therapeutics, and advanced biomaterials. Its growth has been fueled by a combination of consumer acceptance, procedural convenience, and the relative safety profile of hyaluronic acid compared with longer-lasting or more invasive alternatives. Yet several structural challenges and inflection points are now shaping the market's trajectory.
Hyaluronic Acid Dermal Filler Market
Regulatory scrutiny has intensified as authorities evaluate not only product safety but also manufacturing consistency, cross-linking reproducibility, and labeling accuracy. The approval of multiple hyaluronic acid fillers over a recent multi-year window reflects both a responsive regulatory framework and a market eager for differentiated options. This environment creates a double-edged dynamic: clearer pathways can accelerate entry for well-prepared candidates, but they also raise the bar for clinical documentation, quality systems, and post-market surveillance, particularly for companies expanding beyond core geographies.
Second, the market is navigating cost and raw material pressures that complicate margin management. Medical-grade hyaluronic acid pricing varies substantially according to molecular weight, purity specifications, and endotoxin limits, with raw-material costs spanning a wide range depending on grade and application. This variability rewards manufacturers that control upstream inputs or negotiate strategically with suppliers, while exposing those reliant on spot-market procurement to volatility. As a result, the cost structure is becoming a strategic variable rather than a background consideration.
Third, demand-side behavior is evolving from a predominantly cosmetic focus toward a broader set of therapeutic and corrective applications. Patients and providers increasingly value treatments that address volume restoration, scar management, and functional indications in addition to wrinkle correction and lip enhancement. This shift does not eliminate the importance of aesthetic use; rather, it broadens the total addressable market and introduces new reimbursement and clinical evidence requirements that differ by indication and jurisdiction. Companies that can align product characteristics with both cosmetic and non-cosmetic use cases position themselves to capture a wider range of procedures.
Finally, geographic heterogeneity remains a defining feature. Mature markets exhibit high penetration and competitive intensity, while developing regions offer volume growth potential but also require localization of product formats, pricing strategies, distribution models, and educational support. Success in these environments depends less on replicating a single market approach than on adapting to differing regulatory regimes, provider ecosystems, and consumer preferences.
Key Drivers Shaping Market Evolution
Several interconnected drivers explain why the market is expanding at its current pace and how that expansion is likely to be distributed.
Technological innovation in formulation and fabrication. Advances in cross-linking chemistry, particle engineering, and injection dynamics are expanding the clinical utility of hyaluronic acid fillers. Cold-processing and sterilization approaches, such as those associated with recent product approvals, aim to preserve biocompatibility while improving handling and longevity. At the same time, manufacturers are refining rheological profiles to better match specific anatomical sites and treatment goals, enabling products that are optimized for fine lines, deeper folds, lip shaping, or volume restoration. These innovations create meaningful differentiation in a category where performance characteristics are closely linked to provider preference and patient satisfaction. The broader implication is that formulation expertise and manufacturing know-how are increasingly sources of competitive advantage, not just baseline requirements.
A more defined regulatory and reimbursement environment. The regulatory landscape has become more transparent, with a growing number of approvals for hyaluronic acid-based products over a recent multi-year period. This trajectory signals a maturing class of devices and provides a clearer template for evidence generation, quality systems, and post-market commitments. Equally important is the gradual expansion of coverage considerations for selected non-cosmetic uses. Certain insurers and payers have begun to recognize specific injectable dermal fillers and bulking agents for particular indications with defined coding structures, creating early signals of reimbursement pathways outside purely aesthetic settings. While cosmetic procedures remain largely out-of-pocket, these developments illustrate how clinical indication, coding, and documentation can influence utilization and market access, particularly for products positioned for medical or reconstructive use.
Demand-side shifts in consumer and provider behavior. On the demand side, several trends are reinforcing growth. Patients are seeking minimally invasive options with predictable outcomes and manageable downtime, and they are increasingly receptive to combination treatment plans that blend fillers with other modalities. Providers are responding with more tailored product selection by anatomical site and indication, which favors portfolios that offer a range of viscosities, particle sizes, and injection characteristics. There is also growing interest in treatments that address age-related volume loss and structural changes rather than only surface wrinkles, broadening the clinical narrative around fillers. These behavioral shifts reward manufacturers that can educate providers, support clinical adoption, and demonstrate differentiated outcomes for specific use cases.
Supply chain and cost structure dynamics. The upstream supply of pharmaceutical-grade hyaluronic acid remains a critical determinant of competitiveness. Price dispersion across grades, combined with the technical demands of sterile production, means that vertical integration, long-term supplier relationships, and controlled manufacturing environments can materially affect cost and consistency. Recent expansions in dedicated sterile production capacity reflect a strategic response to these pressures, improving throughput and reducing exposure to contamination risks and supply interruptions. For downstream manufacturers and brand owners, securing reliable access to high-quality raw material and maintaining robust quality controls are increasingly central to operational resilience and margin protection.
Competitive Landscape and Leading Strategies
The competitive field combines global multinationals with strong regulatory and commercial infrastructures and regional specialists with deep local presence and manufacturing capabilities. Several companies are recognized for broad hyaluronic acid portfolios and established brand recognition in key aesthetics markets, often supported by long-standing clinical data and provider education programs. Others have built positions around specific formulations, injection characteristics, or regional manufacturing advantages. The list of notable participants spans Europe, North America, Asia, and other regions, reflecting both the global nature of demand and the importance of localized production and distribution.
Leading strategies differ by starting position and ambition. Incumbent brands with mature clinical datasets and widespread provider familiarity tend to emphasize portfolio breadth, indication coverage, and continued investment in evidence generation and education. Their differentiation often rests on brand equity, clinical heritage, and the ability to supply multiple product formats for varied procedures. Emerging or expanding players, by contrast, frequently pursue specific clinical niches, advanced manufacturing claims, or targeted geographic entry. Recent regulatory milestones, such as approvals and submissions for products targeting distinct facial zones and volume restoration, illustrate a strategy of incremental indication expansion that can broaden usage while building toward larger portfolios.
Market structure is evolving along multiple axes. Consolidation pressure exists where scale benefits in manufacturing, regulatory management, and global distribution are highly valuable, and where brand portfolios can be combined to serve a wider set of indications. At the same time, fragmentation persists in regional markets where local manufacturing, pricing, and provider relationships confer advantages that are not easily replicated from outside. New entrants with differentiated technology or a clear clinical angle can gain traction, particularly when they address unmet needs in handling, longevity, or specific anatomical applications. The overall effect is a market in which both consolidation and specialized differentiation can succeed, depending on execution and the ability to align product attributes with provider demand.
A noteworthy structural feature is the influence of raw material access and manufacturing quality on competitive positioning. Companies that control or closely partner on high-grade hyaluronic acid supply, and that invest in sterile production and consistent cross-linking, are better positioned to manage cost, quality, and supply continuity. This is especially relevant as demand scales and as regulatory expectations for consistency and traceability become more entrenched. In practical terms, the competitive advantage increasingly derives from the ability to deliver predictable product performance at scale, supported by strong quality systems and reliable inputs.
Hyaluronic Acid Market
Future Trends and Commercial Implications
Looking ahead across the next three to five years, several trends are likely to shape how value is created and captured.
Indication expansion beyond purely cosmetic use. As clinical evidence accumulates and reimbursement pathways for selected non-cosmetic applications become more defined, fillers are likely to be used more broadly for volume restoration, scar management, and specific reconstructive or functional indications. This trend expands the addressable market and introduces new requirements for clinical documentation, coding, and provider training. Commercially, it favors companies that can support both aesthetic and medical use cases, and that can adapt messaging and evidence strategies to the expectations of different stakeholders, from cosmetic practices to clinical settings with coverage considerations.
Technology-led differentiation and narrowing performance gaps. As more products gain approval and enter the market, the performance envelope across the category is likely to tighten, making incremental improvements in handling, integration, longevity, and patient experience more important for discrimination. This will reward R&D intensity, rigorous clinical evaluation, and manufacturing precision. It also raises the stakes for brand building and provider education, since clinical nuance may matter more than headline claims. Companies that can convert technical advantages into clear, credible value propositions for providers and patients will be better placed to defend pricing and share.
Supply chain resilience and regional production strategies. Continued investment in sterile production capacity and controlled raw material supply is expected as companies seek to reduce risk and improve consistency. Regional manufacturing footprints may become more important where local content expectations, logistics, or speed-to-market considerations influence purchasing decisions. The commercial implication is that operational maturity, not just product design, will increasingly differentiate winners, particularly in markets where supply reliability and quality assurance are closely scrutinized.
These trends carry both opportunity and uncertainty. Growth potential is clear, but it is sensitive to regulatory decisions, reimbursement evolution, and the pace at which new indications gain acceptance. Competitive intensity may compress margins in segments where differentiation is limited, while rewarding those with strong clinical data, robust quality systems, and differentiated product profiles. There is also uncertainty around consumer spending patterns, provider adoption curves, and the extent to which non-cosmetic coverage expands in practice. Scenario planning that accounts for these variables will be more useful than single-point forecasts when evaluating investment and entry decisions.
PW Consulting Chemical & Energy Research Center
Strategic Considerations for Decision-Makers
Different stakeholders face distinct priorities, but several actions are broadly relevant.
For manufacturers and brand owners, the priority is to align product architecture with realistic clinical demand and to invest where differentiation is durable. That means focusing on formulation and manufacturing attributes that providers can perceive and trust, supporting those attributes with credible evidence, and building educational programs that help integrate products into varied treatment plans. Companies should also evaluate whether to deepen control over raw material supply and sterile manufacturing to improve consistency and reduce cost exposure, and whether to pursue incremental indication or geography expansion in a disciplined manner that matches regulatory readiness and commercial infrastructure.
For investors, the key is to assess not only market growth but also the durability of competitive advantage within that growth. Favor structures where quality systems, regulatory competence, clinical data, and supply resilience create barriers that are difficult to replicate quickly. Evaluate whether a company's pipeline and recent milestones indicate genuine differentiation or incremental overlap with existing products, and consider the sensitivity of outcomes to reimbursement shifts and regional adoption rates. Diversification across geographies and indications can reduce concentration risk, but only when supported by execution capabilities that match local requirements.
For procurement and supply chain leaders, the focus should be on qualifying suppliers and products against clear criteria for consistency, purity, and sterile production, and on building flexibility into sourcing strategies to manage price variability across grades. Long-term partnerships with suppliers that can demonstrate reliable quality, transparent documentation, and stable capacity are likely to reduce operational risk and support cost predictability. Where pipeline needs span multiple product types or indications, coordinating procurement with clinical and regulatory planning can help ensure that supply choices align with intended use and approval pathways.
Across these roles, the value of granular, up-to-date intelligence is high. Aggregate market figures provide context, but decisions about entry, expansion, pricing, portfolio design, and supply strategy depend on segment-level demand patterns, regional regulatory status, approval pipelines, reimbursement developments, and competitive moves that are often not visible in summary data. Timely, detailed information allows organizations to refine assumptions, identify where to commit resources, and avoid overgeneralizing from broad trends.
For those seeking a fuller picture, a comprehensive research report can provide deeper segmentation detail, regional and application-level demand analysis, and customized scenarios tailored to specific strategic questions. Access to that level of granularity supports more precise planning and more confident execution in a market that is growing steadily, but only for participants who can combine innovation with operational discipline and market-specific insight.
For detailed analysis of this topic, please visit the official page: Hyaluronic Acid Based Dermal Fillers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


