



Calcium Formate Market: The Real Drivers Behind 7.2% CAGR Growth Through 2032

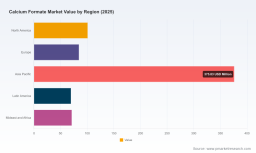
The Calcium Formate Market: Strategic Shifts and Commercial Opportunities Through 2032
The global calcium formate market has entered a period of steady expansion, characterized by consistent value growth and shifting demand patterns across construction, animal nutrition, and industrial applications. Valued at 495.16 million USD in 2020, the market climbed to 701.0 million USD by 2025, reflecting a compound annual growth rate of approximately 7.2 percent through the forecast horizon extending to 2032. By the close of the projection period, market value is positioned to surpass 1.14 billion USD, driven by structural demand in fast-setting construction chemistries, feed preservation formulations, and specialty industrial processes. The trajectory signals a transition from steady commodity positioning toward a more differentiated landscape where grade purity, regional supply reliability, and regulatory compliance increasingly dictate commercial outcomes.
A Market at an Inflection Point
While the headline growth figures suggest uninterrupted expansion, the underlying dynamics reveal a sector navigating several concurrent pressures. First, raw material cost volatility is reshaping margin structures across the value chain. Formic acid serves as the primary feedstock for calcium formate production, and recent pricing actions in European markets have directly altered production economics. A March 2026 price increase of 250 Euro per metric ton on formic acid immediately elevated input costs for downstream calcium formate manufacturers, compressing margins for producers operating without index-linked contracts or hedging mechanisms. This shift forces a reassessment of regional sourcing strategies and accelerates interest in vertically integrated or regionally balanced supply models.
Potassium Formate Market
Second, regulatory frameworks are redefining permissible use levels and creating new pathways for market entry. The formal approval of calcium formate as a feed acidifying agent for swine and poultry at up to 1.2 percent of complete feed marked a significant clarification for formulators and premix suppliers. Simultaneously, a 2026 consultation process in Canada regarding pre-market amendment of the Feeds Regulations, 2024 signals ongoing scrutiny and evolving approval timelines for new feed ingredient categories. For market participants, regulatory clarity expands addressable demand in animal nutrition, but inconsistent regional approval pathways introduce compliance complexity and extended time-to-market for cross-border product rollouts.
Third, demand-side shifts are altering grade prioritization and application mix. Construction chemical formulators continue to prioritize calcium formate for its performance in cold-weather concrete acceleration, tile adhesives, and dry-mix mortar systems, particularly in markets experiencing infrastructure renewal or seasonal construction constraints. At the same time, feed preservative demand is expanding where producers seek alternative acidifiers with favorable handling characteristics and compatibility with existing premix architectures. These parallel demand streams are pulling the market in different technical directions, requiring suppliers to maintain distinct product specifications rather than relying on a single commodity-grade offering.
PW Consulting
The competitive structure remains relatively fragmented, with the top three suppliers accounting for approximately one-quarter of total market value and the top five capturing just over one-quarter. This concentration pattern indicates meaningful room for regional differentiation and specialized positioning, but it also underscores the importance of scale efficiency, technical service capabilities, and supply continuity as competitive differentiators.
Core Drivers Reshaping the Market
Several interconnected forces are redefining how value is created and captured across the calcium formate landscape. Understanding these drivers provides the foundation for investment, sourcing, and product strategy decisions.
Feedstock dynamics and cost architecture. The relationship between formic acid pricing and calcium formate production economics is central to profitability. Recent European formic acid pricing adjustments have illustrated how quickly input costs can shift, particularly when supply is concentrated in specific regional hubs or affected by broader chemical market cycles. Producers with access to captive or long-term feedstock supply, or those positioned in regions with lower feedstock volatility, gain a structural cost advantage. Conversely, manufacturers relying on spot procurement face greater exposure to margin compression. This dynamic is encouraging a reevaluation of sourcing footprints, including regional substitution, dual-supplier strategies, and contractual structures that link cost pass-through to finished-grade pricing.
Regulatory evolution as a demand catalyst and barrier. Regulatory developments are simultaneously unlocking demand and adding compliance complexity. The formal recognition of safe use levels for calcium formate in swine and poultry feed creates a clearer formulation pathway for feed acidifiers, supporting demand in animal nutrition where gut health, preservation, and feed efficiency remain priorities. At the same time, ongoing consultation processes in markets such as Canada demonstrate that ingredient approval is not a one-time event but a continuous regulatory management requirement. Companies that treat regulatory alignment as a core commercial capability—rather than a backend compliance function—can accelerate market access and reduce the risk of reformulation delays.
Construction chemical performance requirements. Demand from construction applications continues to be shaped by performance needs that go beyond simple set acceleration. Formulators increasingly look for calcium formate grades that deliver reliable performance across varying temperature conditions, compatibility with diverse binder systems, and consistency in dry-mix and pre-blended mortar applications. Cold-weather concreting, tile adhesive performance, and corrosion-inhibition considerations in certain applications add technical nuance to procurement decisions. As infrastructure investment cycles and housing activity patterns shift regionally, suppliers that can provide application-specific grade optimization and technical support are better positioned to retain share even when price competition intensifies.
Animal nutrition and feed preservation trends. In the feed segment, demand is influenced by broader livestock production practices, biosecurity concerns, and the search for preservative solutions that integrate cleanly into existing feed formulations. Calcium formate's role as an acidifying and preserving agent aligns with formulator interest in ingredients that support feed stability and handling while meeting defined safety thresholds. The expansion of permitted inclusion levels in certain species has broadened the formulation envelope, allowing feed manufacturers to optimize dosage strategies without compromising compliance. This development is particularly relevant where producers aim to replace or supplement more traditional acidifiers with alternatives offering favorable handling, dust, or storage characteristics.
Competitive Positioning and the Evolution of the Landscape
The supplier landscape spans established multinational producers, specialized chemical manufacturers, and regional players concentrated in Asia Pacific, Europe, and North America. Rather than competing solely on price, leading participants are differentiating through grade specialization, application support, regional supply reliability, and selective expansion into higher-value industrial or feed-grade niches.
Multinational producers with broad chemical portfolios tend to emphasize high-purity calcium formate for construction, adhesives, and industrial uses, leveraging existing distribution networks and technical service capabilities. Their positioning often centers on specification consistency, regulatory documentation, and the ability to support large-formulation customers with product reliability across multiple markets. For these players, scale and portfolio breadth can translate into stronger relationships with specification-driven buyers who prioritize supply continuity and quality assurance.
Formic Acid Market
Specialized producers focused on green or application-specific calcium formate are carving out distinct positions in feed additives and construction chemicals. By aligning product development with sustainability narratives or regional performance requirements, these companies seek to reduce direct price comparison with commodity-grade alternatives. For feed-focused participants, the strategic emphasis is often on formulation compatibility, safe-use documentation, and regional regulatory readiness. For construction-focused participants, differentiation frequently comes through performance consistency in dry-mix mortars, tile adhesives, and cold-weather accelerators, alongside service responsiveness to formulator testing and customization needs.
Regional manufacturers, particularly in Asia Pacific, play an important role in meeting volume demand across feed and construction applications. Their growth trajectory is supported by proximity to feedstock supply, expanding domestic construction activity, and increasing integration into export-oriented supply chains. At the same time, these players face pressure to demonstrate grade consistency, regulatory compliance for destination markets, and reliable logistics performance as customers diversify their sourcing bases. The result is a landscape where regional scale and technical credibility increasingly coexist as prerequisites for broader market access.
Market structure appears to be evolving along several lines. Consolidation is plausible in segments where scale in feedstock procurement, production efficiency, and regional distribution provides durable advantages, particularly among suppliers targeting large construction-chemical or feed premix customers. At the same time, fragmentation is likely to persist where regional demand patterns, regulatory nuances, and application-specific requirements reward localized production and customized grade offerings. New entrants may find opportunities in niche industrial-grade supply, laboratory and research channels, or specialized feed-additive formulations, especially where incumbents are less focused on small-volume, high-specification segments. Recent feedstock pricing dynamics also suggest that competitive advantage will increasingly depend on cost management agility rather than volume alone, favoring companies that can adapt pricing, sourcing, and product mix quickly.
Forward Outlook: Three Trends to Watch Through 2032
Looking ahead, several trends are likely to shape commercial outcomes over the next three to five years. Each trend carries implications for strategy, risk management, and opportunity capture.
Trend 1: Feedstock-linked margin management becomes a core competitive capability. With formic acid pricing subject to regional volatility and periodic sharp adjustments, producers that institutionalize feedstock cost management—through long-term contracts, regional sourcing diversification, index-linked pricing mechanisms, or selective vertical integration—will be better positioned to protect margins. The commercial implication is clear: cost resilience will increasingly differentiate winners from laggards, especially in periods when raw material spikes cannot be immediately passed through to customers. Companies that fail to build flexible cost architectures risk margin erosion and reduced ability to invest in product development or regional expansion.
Trend 2: Regulatory alignment accelerates feed-grade demand in select markets while creating uneven global access. The formalization of safe use levels for calcium formate in swine and poultry feed expands the formulation toolkit for animal nutrition customers and supports demand growth where adoption is already underway. However, the staggered nature of regulatory consultations and approvals across jurisdictions means that market access will remain uneven. Feed-focused suppliers that invest early in regulatory documentation, regional approvals, and customer education are likely to capture first-mover advantages in markets where inclusion levels are clarified or expanded. Conversely, delays in approval pathways can constrain near-term commercialization even when underlying demand is strong.
Trend 3: Application-specific grade differentiation intensifies as construction and feed demand pull in different directions. Construction chemical requirements and feed preservation needs are not converging into a single commodity specification. Instead, they are reinforcing the need for distinct industrial-grade and feed-grade offerings, each with its own quality, handling, and compliance expectations. Suppliers that maintain clear grade separation, robust quality control, and transparent documentation will be better equipped to serve specification-sensitive buyers. This trend also creates opportunities for companies that can bridge multiple end-use segments, provided they avoid dilution of grade integrity or compliance positioning. At the same time, the growing emphasis on performance-specific grades may invite competitive pressure from alternative additives, requiring continuous demonstration of functional value rather than reliance on commodity positioning alone.
These trends are interconnected. Feedstock cost dynamics influence grade pricing and margin capacity for product development. Regulatory developments shape demand readiness in feed applications and affect the pace at which new formulations can be commercialized. Application-specific differentiation determines whether suppliers can sustain premium positioning or are forced into commodity price competition. Taken together, they point to a market where strategic agility, technical credibility, and regional execution matter more than simple volume scale.
Strategic Actions for Decision-Makers
The evolving calcium formate landscape presents distinct priorities depending on a decision-maker's position in the value chain.
For manufacturers and producers: Prioritize feedstock cost resilience and grade discipline. Evaluate sourcing contracts, regional supply options, and pricing mechanisms that reduce exposure to sharp feedstock swings. Maintain clear separation between feed-grade and industrial-grade offerings, supported by consistent quality control and documentation that meets destination-market requirements. Where feasible, build application-specific technical support capabilities to strengthen relationships with construction-chemical formulators and feed premix suppliers. Consider selective expansion into regions or segments where regulatory clarity is improving and where existing supply gaps create room for reliable, specification-driven participation.
For investors and corporate development teams: Assess exposure to feedstock volatility and regional regulatory pathways when evaluating opportunities. Companies with strong cost-management structures, clear grade positioning, and credible regulatory readiness are better placed to capture demand growth without sacrificing margin stability. Pay attention to market fragmentation as both a risk and an opportunity: fragmented markets can reward specialized, well-executed regional players, but they can also pressure undifferentiated suppliers into margin compression. Monitor consolidation signals in segments where feedstock procurement, production scale, or distribution density creates durable advantages, and evaluate whether potential targets have the technical and compliance capabilities to support broader commercial ambitions.
For procurement and supply chain leaders: Diversify sourcing strategies to reduce vulnerability to single-region feedstock disruptions and to improve responsiveness to grade-specific requirements. Establish specification frameworks that distinguish feed-grade and industrial-grade needs clearly, and align supplier selection with documentation, consistency, and delivery reliability rather than price alone. Where long-term supply relationships are in place, consider contractual structures that accommodate feedstock-driven cost movements while preserving budget predictability. Technical collaboration with suppliers can also help optimize dosage, handling, and formulation performance, turning procurement decisions into value-creating partnerships rather than transactional purchases.
Strategic decisions in this market benefit from detailed visibility into regional demand patterns, grade-level pricing dynamics, regulatory calendars, and competitive positioning. A comprehensive view of these variables supports more precise sourcing, investment, and product strategies, particularly as feedstock conditions and regulatory frameworks continue to evolve. For organizations seeking deeper segmentation data, region-level volume and value context, and customized scenario planning, PW Consulting's full market research report provides a structured foundation for next-step decision-making. The complete study extends beyond the trends summarized here, offering granular segmentation detail and tailored recommendations designed to support executive planning, investment evaluation, and supply strategy development.
For detailed analysis of this topic, please visit the official page: Calcium Formate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


