



Traffic Signs Market Forecast 2026-2032: The 7.75% CAGR Reshaping Industry Growth

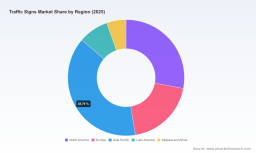
The Traffic Signs Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global traffic signs market is navigating a structural transition. Over the tracking period from 2020 through 2025, the sector expanded from approximately USD 44.59 million to a projected USD 64.76 million, and forward estimates point to continued growth toward nearly USD 110 million by 2032, supported by a compound annual growth rate of 7.75%. The trajectory signals more than routine infrastructure renewal. It reflects a convergence of regulatory tightening, material cost volatility, and the early stages of digital-physical integration in road safety infrastructure. For executives, planners, and investors, the question is no longer whether the market will grow, but which segments of the value chain will capture disproportionate value as standards evolve and procurement models reorganize.
Worldwide Traffic Signal Recognition Market
The numbers outline a market that has recovered from pandemic-era procurement pauses and is now anchored by sustained public investment in road safety, urbanization-driven signage demand, and incremental modernization of legacy traffic control systems. Historical data shows consistent year-over-year expansion, with the jump from 2023 to 2024 indicating a stabilization phase before the 2025 baseline accelerates. The forecast period through 2032 suggests that growth will not be linear; rather, it will be shaped by policy adoption cycles, regional infrastructure pacing, and manufacturers’ ability to navigate input cost pressure while maintaining compliance with evolving visibility and performance standards.
Market Reality and Core Challenges
The market’s expansion is real, but it is unfolding against a backdrop of operational friction. Three challenges stand out as particularly consequential for strategic planning.
Material Cost Volatility and Margin Compression
Aluminum remains the primary substrate for most traffic sign blanks, and its pricing dynamics have introduced a new layer of risk into production planning and bid economics. Through late 2025, Midwest Premium aluminum prices climbed approximately 190% year-over-year, a spike that compresses margins for manufacturers working under fixed-price municipal contracts or competing in price-sensitive procurement environments. This is not merely a cost issue; it reshapes sourcing strategies, inventory timing, and the economics of sign blank production versus finished sign assembly. Companies that rely heavily on coil stock and blank production are exposed to raw material volatility in ways that differentiate their cost structures from firms focused on value-added assemblies, illuminated solutions, or traffic calming systems.
PW Consulting
Regulatory Visibility Standards and Compliance Complexity
Visibility and retroreflectivity requirements are becoming more prescriptive, raising the bar for what qualifies as a compliant permanent traffic control sign. In Ohio, for example, guidance from the Department of Transportation has moved toward recommending Type III retroreflective sheeting for all permanent new traffic control signs on maintained highways, while also requiring Type IV, IX, or XI sheeting in specific contexts. These requirements are part of a broader standardization trend that ties sign performance to measurable visibility outcomes rather than legacy material norms. Compliance complexity is increasing because regulators are not only specifying sheeting grades but also linking them to placement, maintenance cycles, and nighttime performance expectations. For manufacturers and contractors, the operational implication is clear: product specifications that fall behind evolving standards risk disqualification in public tenders, while faster adoption can become a competitive differentiator.
At the same time, the broader framework governing traffic control devices continues to evolve. Recent updates to MUTCD standards are reinforcing visibility, placement, and performance requirements across a range of sign and traffic calming products. That means compliance is no longer a one-time certification exercise; it is an ongoing design constraint that affects product development cycles, testing protocols, and field deployments.
Procurement Fragmentation and the Pressure to Standardize
Traffic sign procurement remains fragmented across municipalities, state agencies, contractors, and cooperative purchasing vehicles. This fragmentation creates both opportunity and inefficiency. On one hand, it allows specialized providers to serve niche applications and regional preferences. On the other hand, it slows the adoption of higher-performance materials and limits scale economies for standardized solutions. The tension is visible in the market’s concentration profile, where a meaningful share of revenue is held by a relatively small group of firms, yet substantial demand still flows through dispersed buyers with varied specifications and purchasing timelines. As cooperative purchasing contracts and multi-agency frameworks expand, the market may tilt toward more standardized product families, but the transition will be uneven across regions and agency types.
Core Drivers Reshaping the Market
Technology Innovation: From Passive Signage to Active Visibility
One of the most significant shifts in the market is the move beyond static signage toward solutions that enhance driver awareness through illumination, flashing elements, and sensor-linked warnings. Solar-powered flashing warning signs, radar speed displays, and pedestrian crossing enhancements are expanding the definition of what a traffic sign can do. This is not a wholesale replacement of traditional signs, but an incremental layering of active visibility features where risk is higher or compliance requires stronger behavioral cues. The commercial relevance is that these products command different margin structures, different installation requirements, and different procurement justifications than passive blanks or reflective signs. Manufacturers that can combine compliance-grade base products with active visibility add-ons are positioned to capture value in applications where safety outcomes are measured and funded more explicitly.
The traffic calming segment illustrates this dynamic well. Products that integrate static signs with radar-based feedback, flashing warnings, and pedestrian-crossing enhancements are increasingly tied to public agency goals around speed management and intersection safety. As these solutions become more standardized and more visibly effective, they create a bridge between traditional sign manufacturing and the broader traffic safety equipment market.
Policy and Regulatory Momentum around Safety Outcomes
Policy is becoming a more direct driver of demand because road safety is increasingly framed around measurable outcomes rather than routine maintenance. Regulatory bodies and transportation departments are sharpening requirements for retroreflectivity, sheeting performance, and device visibility. This policy momentum benefits suppliers that can demonstrate compliance, provide documentation, and align product roadmaps with emerging standards. It also raises the importance of regulatory intelligence as a commercial capability. Companies that anticipate updates to visibility standards, understand regional interpretations, and design products with forward compliance in mind reduce the risk of specification obsolescence and improve their positioning in agency procurement.
A related policy driver is the increasing use of cooperative purchasing frameworks, which can broaden access to compliant products for public agencies while also creating more transparent price discovery. Recent contract awards that expand public agency access to MUTCD-compliant safety solutions show how procurement channels themselves are becoming a strategic lever. For manufacturers, inclusion in such frameworks can shorten sales cycles and increase volume predictability, but it also intensifies competition on specification, availability, and total cost of ownership.
Traffic Signal Controller Market
Demand-Side Shifts in Municipal and Regional Procurement
Demand is being shaped by a shift in how public agencies think about signage and safety infrastructure. Instead of treating signs purely as replacement items, agencies increasingly evaluate them within broader safety programs, work zone management plans, and traffic calming initiatives. That shift changes the sales narrative from unit price to functional outcome. It also expands the relevant buying center, bringing engineering, safety, and maintenance teams into the decision process alongside procurement. As a result, suppliers that can articulate performance benefits, maintenance implications, and compliance documentation are gaining an advantage over those competing primarily on material cost.
In addition, the demand mix is diversifying by application type. Guide and direction signs, warning signs, regulatory signs, and other specialized signage each serve different operational contexts, and the relative importance of each category varies by region and project type. The broader point is that demand is not monolithic. Growth is being distributed across categories with different replacement cycles, specification sensitivity, and installation complexity. Understanding which application categories are tied to higher-frequency renewal cycles versus longer-life installations is essential for revenue forecasting and capacity planning.
Supply Chain and Cost Structure Reconfiguration
The supply chain for traffic signs is being tested by material input volatility, logistics complexity, and the need to maintain consistent quality across reflective sheeting, metal substrates, and ancillary hardware. Cost structure is becoming a strategic differentiator rather than a back-office concern. Manufacturers that can manage blank production efficiently, secure stable sheeting supply, and reduce lead-time variability gain latitude in pricing and bidding. At the same time, regional manufacturing footprints matter more as agencies and contractors look for predictable delivery, localized support, and lower total installed cost. In this environment, the competitive edge often lies in combining material sourcing discipline with application-specific product configuration, rather than pursuing scale alone.
The rise of export-oriented manufacturers also adds a global dimension to supply dynamics. Some producers have built positions serving a wide range of countries with certifications that support cross-border distribution. That creates price and availability competition in certain segments while also giving buyers more options for specification-matched products. The strategic response for established players is not simply to compete on price, but to reinforce compliance assurance, service responsiveness, and product consistency that are harder to replicate through transactional importing.
Competitive Landscape and Leading Strategies
The competitive field includes a mix of specialized U.S. manufacturers, export-oriented producers, and broader traffic systems providers. Several patterns define the current landscape.
A group of North American companies has built its positioning around MUTCD and DOT compliance for static signs, custom reflective aluminum signs, work zone products, and related control signage. These firms compete heavily on specification alignment, availability, and familiarity with public agency procurement requirements. Their differentiation often comes from product breadth within compliant signage categories, responsiveness to municipal and contractor demand, and the ability to supply both standardized and custom configurations. In a market where compliance documentation and material consistency matter, that positioning can be durable, especially when paired with cooperative purchasing access or strong regional distribution.
A second grouping emphasizes traffic calming and active visibility solutions. These providers extend beyond traditional sign blanks into radar speed displays, flashing warning signs, pedestrian crossing enhancements, and related systems. The strategic advantage here is category expansion: by offering products that address speed management and driver awareness directly, these companies can participate in projects where safety outcomes are prioritized and where funding is tied to measurable behavior change or risk reduction. This approach also diversifies revenue beyond replacement-driven signage demand, though it requires investment in product development, testing, and sometimes field support.
A third dimension is represented by broader traffic systems providers with portfolios spanning standard signs, variable message signs, dynamic signage, and illuminated solutions for highways and urban environments. These companies compete by offering integrated capability across static and dynamic categories, which can be attractive for larger projects or regions pursuing modernization programs. Their scale and portfolio breadth allow them to address multiple signage functions within a single engagement, but they must still navigate the same regulatory and material pressures as more specialized players.
Recent market activity shows how these strategies are playing out. One U.S. traffic calming provider expanded access to public agencies through a cooperative purchasing contract, strengthening the procurement channel for MUTCD-compliant safety solutions. Around the same time, the same provider introduced new solar flashing warning signs designed to improve visibility and driver awareness on critical roadways. These moves illustrate a combined strategy of channel expansion and product refresh aimed at active visibility applications. In parallel, an Austrian traffic systems provider previewed next-generation sign solutions at a major industry event, signaling continued investment in advanced signage portfolios for highways and urban deployments. Together, these developments suggest that competition is intensifying not only in price, but in channel access, product modernization, and the ability to meet evolving visibility expectations.
The market is also likely to see continued differentiation between firms that compete primarily as commodity-adjacent sign suppliers and those that position around performance, compliance assurance, and application-specific solutions. Consolidation may occur where scale, sourcing, and distribution advantages can be combined, while fragmentation may persist in specialized or region-specific segments where local service and specification knowledge matter. New entrants are most likely to appear in active visibility and traffic calming niches, where the link between product capability and safety outcome is more direct and where procurement narratives increasingly favor demonstrated performance.
Forward Trends and Commercial Opportunities
Active Visibility and Solar-Enabled Signage Will Move from Niche to Mainstream in Targeted Applications
Over the next three to five years, active visibility features are likely to become more common in high-risk corridors, school zones, pedestrian crossings, and work zone environments. Solar flashing warning signs and radar-linked displays will continue to gain traction where agencies need stronger behavioral cues and where wiring or grid access is impractical. The commercial opportunity lies in bundling these solutions with compliant base signage and installation support, creating offerings that are easier for agencies to adopt as part of broader safety programs. The risk is that active visibility products may face their own specification, maintenance, and durability scrutiny, so suppliers will need to invest in field reliability and documentation as well as initial performance claims.
Regulatory-Driven Material Upgrades Will Reset Product Standards and Replace Legacy Inventory
As visibility and sheeting requirements become more prescriptive, there will be a multi-year cycle of material upgrades and replacement demand. This creates a commercial window for manufacturers and distributors that can supply compliant retroreflective materials, upgrade existing product lines, and help agencies manage transition timelines. It also raises a strategic risk for suppliers whose product portfolios lag behind emerging standards. The opportunity is not just in selling new signs, but in helping buyers navigate the shift from older materials to higher-performance sheeting, including guidance on applicability, installation, and maintenance expectations. Firms that treat regulatory change as a product strategy input rather than a compliance afterthought will be better placed to capture this cycle.
Regional Demand Divergence Will Reward Segment-Specific Positioning
Demand growth will not unfold uniformly. Regions with faster urbanization, more active road safety programs, and stronger cooperative procurement frameworks are likely to show stronger momentum, while other markets may remain dependent on replacement cycles and budget pacing. For manufacturers and investors, this means that broad market averages can obscure where the most attractive opportunities actually sit. The more productive approach is to align product portfolios, distribution capacity, and pricing strategy with regional demand characteristics and procurement behavior. Companies that can tailor offerings to specific application mixes, agency types, and compliance expectations will be better positioned than those relying on a single standardized playbook.
For the materials and cost side, the forward risk is that aluminum and sheeting volatility may persist in cycles, making hedging, sourcing flexibility, and product mix optimization increasingly important. Suppliers that can shift emphasis toward higher-value assemblies, active visibility products, or service-linked offerings may be better insulated than those dependent on low-margin blank production alone.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
- Align product roadmaps explicitly with evolving visibility and sheeting standards so that compliance becomes a design input rather than a retrofit exercise.
- Expand into active visibility and traffic calming adjacencies where safety outcomes support stronger value propositions and differentiate pricing from commodity sign supply.
- Build sourcing and inventory strategies that reduce exposure to metal input volatility, including flexible blank procurement, regional supply options, and product mixes that balance material-intensive and value-added items.
For Investors and Strategic Capital
- Evaluate exposure to regulatory-driven replacement cycles and active visibility adoption, since these dynamics can shape both revenue durability and margin profiles across different business models.
- Distinguish between players that compete primarily on price and commodity-like supply and those that have defensible positions in compliance, product reliability, channel access, or application specialization.
- Watch for consolidation opportunities where regional distribution, cooperative purchasing access, and product breadth can be combined to improve scale and customer retention.
For Procurement Agencies and Contracting Entities
- Standardize specifications around current visibility and performance expectations to reduce specification lag and improve comparability across bids.
- Evaluate total cost and safety outcomes rather than unit price alone, especially when considering active visibility or higher-performance sheeting that may reduce long-term maintenance or improve driver response.
- Use cooperative purchasing and multi-agency frameworks strategically to expand access to compliant products while maintaining specification rigor and vendor accountability.
The traffic signs market is entering a phase where growth is increasingly tied to how well participants navigate regulatory change, material cost pressure, and the shift toward active visibility. The companies that will capture the most value are those that can combine compliance confidence with product modernization and efficient cost structures, while also understanding how demand differs by region, application, and procurement channel. For executives and investors looking to move from market awareness to detailed segmentation, competitive mapping, and tailored commercial strategy, a full research report can provide the deeper breakdown needed to support decisions with precision.
For detailed analysis of this topic, please visit the official page: Traffic Signs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


