



Why Waste-to-Energy Market Growth at 3.62% CAGR Shows Reshaping Forces in 2032

Navigating the Waste-to-Energy Market: Strategic Trends and Commercial Opportunities Through 2032
The waste-to-energy (WTE) sector stands at a critical inflection point. As municipal waste volumes continue to rise alongside growing pressure to decarbonize power generation, the industry is evolving from a niche waste management solution into a structured component of regional energy infrastructure. Market trajectories indicate steady expansion, with a compound annual growth rate of 3.62 percent projected through 2032. Revenue scales from an estimated 311.0 million USD in 2025 to approximately 399.58 million USD by 2032, reflecting a compound annual expansion of 3.62 percent. This growth trajectory is neither linear nor uniformly distributed. While baseline figures suggest consistent upward movement, the underlying dynamics reveal a market shaped by technological differentiation, regulatory recalibration, and shifting operational economics. For executives and investors, the challenge lies in distinguishing structural tailwinds from transitional noise and positioning accordingly.
Market Snapshot and Structural Challenges
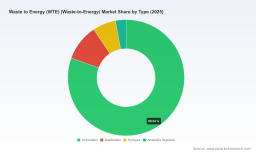
The current market environment reflects a mature but unevenly developed landscape. Thermal conversion routes continue to anchor the majority of installed capacity, with incineration accounting for the largest share of revenue. Complementary pathways such as gasification, pyrolysis, and anaerobic digestion represent a collective but growing portion of the market, signaling gradual diversification beyond conventional combustion. Application-wise, electricity generation dominates end-use deployment, while heat production captures a meaningful secondary segment. Regional distribution shows pronounced concentration, with Asia Pacific and Europe collectively representing the bulk of market value, North America maintaining a substantial position, and Latin America and the Middle East/Africa reflecting early-stage development potential.
This macro structure, however, masks several operational and strategic friction points that define the current cycle.
1. Conversion Efficiency and Emissions Compliance Under Scrutiny
Traditional grate-based incineration remains the operational backbone, yet it faces mounting pressure to improve net energy recovery while meeting tighter air emissions thresholds. Facilities that operate with older boiler configurations or suboptimal heat recovery systems struggle to maintain favorable levelized costs, particularly as grid parity expectations rise and carbon accounting becomes embedded in procurement and financing decisions. The industry is being pushed toward higher steam parameters, advanced flue gas treatment, and integrated heat utilization, which raises capital intensity but improves long-term contract economics.
2. Policy Fragmentation and Regulatory Transition Risk
WTE does not operate in a uniform regulatory vacuum. Jurisdictions are simultaneously incentivizing waste-to-energy as a clean generation pathway and imposing stricter monitoring, reporting, and offset obligations on incineration-based systems. This creates a dual dynamic: projects may qualify for clean electricity provisions in one market while encountering emissions compliance costs in another. Organizations with cross-border portfolios or multi-jurisdictional supply chains must navigate divergent definitions of eligibility, differing measurement methodologies, and staggered compliance timelines that can compress margins or delay commissioning.
3. Feedstock Reliability and Contract Structuring Complexity
The economics of WTE projects remain tightly linked to consistent waste supply, calorific value stability, and long-term offtake security. Diversion of recyclables, changes in municipal collection practices, and competition from alternative recovery pathways can alter feedstock composition mid-cycle. In markets where tariff structures, cost recovery mechanisms, or interconnection rules are still being formalized, developers face elevated negotiation risk. Securing bankable feedstock agreements and aligning them with energy revenue routes is increasingly a core strategic task rather than a secondary operational concern.
Key Drivers Reshaping the Sector
The market trajectory is being shaped by a set of mutually reinforcing forces that extend beyond simple waste volume growth or energy demand. Understanding the interaction between technology, policy, customer behavior, and cost dynamics is essential for identifying durable profit pools rather than short-term cycles.
Technology Innovation and System-Level Efficiency Gains
Innovation is moving beyond incremental boiler upgrades toward integrated plant design and alternative conversion routes. Gasification and pyrolysis continue to attract attention for their potential to produce secondary fuels and chemical precursors, while anaerobic digestion is carving out a distinct niche where organic-rich waste streams and heat-on-site applications align. On the thermal side, advanced combustion controls, improved refractory and boiler materials, and better heat recovery integration are helping facilities extract more usable energy per tonne of input. Equipment suppliers and EPC players are increasingly positioned as partners in lifecycle optimization, not just plant builders. The strategic implication is clear: technology choice now influences not only emissions performance but also revenue flexibility, grid qualification, and long-term contract structure.
Policy and Regulatory Reorientation
Recent regulatory developments illustrate how policy is both enabling and disciplining the market. Clean electricity tax credit guidance in the United States has clarified that WTE facilities can qualify when assessed through lifecycle analysis, giving eligible projects a clearer financing pathway and improving project economics for compliant operations. At the same time, emissions-related obligations are becoming more granular. In the United Kingdom, the extended carbon pricing and monitoring scope now captures energy-from-waste and incineration, with reporting obligations beginning and full surrender requirements phased in later in the decade. This creates a compliance dimension that must be modeled into cash flow forecasts rather than treated as a peripheral environmental cost.
In emerging and fast-scaling markets, regulatory clarity is directly shaping project pipelines. Indonesia's presidential regulation setting a fixed electricity purchase price for WTE under a state-backed program, with long-term contract structures and compensation mechanisms for grid connection costs, reduces revenue uncertainty for developers and equipment providers alike. Meanwhile, the Philippines has moved to incorporate WTE into national grid and distribution codes, with provisions for long-term cost recovery and subsidies to support interconnection. These frameworks do not guarantee uniform returns, but they do reduce a major class of financing friction and help convert conceptual pipelines into executable projects.
Demand-Side Shifts and Corporate Behavior
The demand environment is changing on two fronts. First, municipalities and industrial operators are increasingly treating WTE not merely as disposal but as part of integrated resource recovery strategies. Heat utilization, for example, is gaining relevance in contexts where district heating, industrial process heat, or adjacent thermal loads can absorb otherwise wasted energy. Second, corporate procurement of renewable and low-carbon energy is expanding the relevance of generation assets that can offer measurable lifecycle attributes. Facilities that can demonstrate credible emissions performance and stable energy output are better positioned to align with offtake relationships, public-private partnerships, and sustainability-linked financing structures. The commercial opportunity lies in packaging energy recovery with verifiable environmental performance rather than in volume alone.
Cost Structures and Supply Chain Realignment
Capital intensity remains a defining characteristic of the sector, but the composition of cost risk is shifting. Equipment supply, engineering procurement, and construction execution are increasingly influenced by regional project pipelines, localization requirements, and lead-time volatility for critical components. Recent project activity underscores this trend. In Taiwan, a major incinerator unit and equipment supply contract was awarded for a WTE plant under a build-operate-transfer model, highlighting the continuing relevance of proven thermal equipment in structured project delivery. At the same time, full EPC and operational partnerships are favored where developers seek integrated risk transfer rather than fragmented procurement. Cost competitiveness now depends on more than hardware pricing; it depends on execution certainty, emissions compliance readiness, and the ability to align plant design with local grid and feedstock conditions.
Waste-to-Energy Technologies Market
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of integrated waste and energy service providers, specialized plant equipment manufacturers, and regional project developers with strong deployment track records. Market concentration, with the top three firms holding approximately 42.5 percent of market value and the top five around 55.2 percent, indicates a sector where scale, operational expertise, and relationship depth matter, but where meaningful participation remains feasible for focused players.
Strategic Archetypes Among Leading Players
Several competitive patterns emerge from current positioning and recent activity:
- Integrated service and operations players combine waste management, plant operation, and energy production into end-to-end offerings. This model reduces coordination risk across collection, processing, and generation, and is particularly valuable where long-term municipal contracts and operational continuity are central to revenue stability.
- Equipment and technology specialists concentrate on core conversion hardware, boiler systems, or full plant delivery. Their differentiation often rests on moving grate and combustion technologies, high-efficiency boiler configurations, and the ability to supply standardized yet customizable solutions for BOT and EPC contexts. Strong delivery records and technology familiarity with grid-connected thermal plants remain central advantages.
- Regional developers and EPC-oriented operators focus on large-scale projects in geographies with active municipal build-outs, particularly in Asia and parts of the Middle East. Their value lies in local execution, permitting and stakeholder management, and the ability to structure projects that align with national energy and waste policy directions.
- Advanced conversion and fuel-oriented entrants emphasize alternative outputs such as renewable natural gas or engineered fuels. These players typically target niches where feedstock composition, product flexibility, and premium offtake structures can support differentiated economics.
How the Landscape Is Evolving
The market is not simply consolidating; it is stratifying. Traditional scale players continue to defend positions through operational breadth and integrated service models, but technology differentiation and policy-linked eligibility are creating new competitive axes. Companies that can combine reliable thermal performance with credible emissions management, grid compliance readiness, and flexible energy product offerings are gaining leverage in both tender processes and private financing discussions. At the same time, new entrants and specialized technology providers are carving out segments through alternative conversion routes or modular plant approaches, particularly where conventional capacity is constrained by regulation or community acceptance. The trend suggests a market in which the battleground is shifting from pure capacity addition toward lifecycle value, compliance resilience, and project structuring capability.
Forward Look: Three Trends to Watch
Looking across the current data and recent policy and project signals, three directional trends are likely to shape the next few years.
1. Policy-Linked Project Economics Will Become a Core Differentiator
As jurisdictions clarify eligibility for clean electricity incentives, define emissions monitoring obligations, and establish cost recovery or interconnection provisions, projects with stronger policy alignment will command better financing terms and more predictable revenue paths. The practical implication is that commercial success will increasingly depend on anticipating regulatory definitions, model lifecycle eligibility early, and structuring contracts to withstand compliance evolution rather than assuming static frameworks.
PW Consulting
2. Heat Integration and Multi-Output Designs Will Expand Value Capture
Electricity remains dominant, but the margin between successful and marginal projects may increasingly hinge on the ability to monetize thermal output. District heating linkages, industrial steam supply, and process heat utilization can improve overall plant economics and reduce sensitivity to electricity price volatility. Facilities and partners that design for heat export from the outset, rather than as an afterthought, can unlock incremental returns and strengthen long-term offtake narratives.
Waste Incinerators Market
3. Supply Chain Localization and Execution Discipline Will Matter More as Pipelines Scale
With several large-scale projects advancing in Europe, Asia, and emerging markets, the sector will test its ability to deliver on schedule, within budget, and with compliant emissions performance. Equipment suppliers and EPC organizations that can localize content where required, manage long-lead items effectively, and deliver standardized yet site-adaptive solutions will capture stronger positioning. Developers, meanwhile, will favor partners who can reduce integration risk across permitting, construction, commissioning, and operation.
These trends carry inherent uncertainty. Policy frameworks can shift as political priorities change, feedstock availability can be disrupted by diversion programs or municipal restructuring, and emissions compliance costs may rise if monitoring obligations tighten faster than anticipated. Additionally, community acceptance and landfill diversion trade-offs continue to influence siting decisions in multiple regions, adding a layer of execution risk that cannot be discounted.
Strategic Playbooks for Decision-Makers
For executives and investors evaluating near- to mid-term moves, the following considerations can help translate market signals into actionable positioning.
For Equipment Manufacturers and Technology Providers
- Prioritize designs that balance proven thermal reliability with flexibility for heat recovery and emissions control upgrades, since these features increasingly influence bid selection and lifecycle economics.
- Strengthen delivery and localization capabilities in regions with active WTE pipelines, where execution certainty and regulatory familiarity are becoming as important as hardware performance.
- Develop clear lifecycle and compliance narratives that align with evolving clean electricity and emissions frameworks, enabling customers to justify investment under changing policy conditions.
For Investors and Project Developers
- Focus underwriting on projects with credible feedstock security, aligned policy incentives, and offtake structures that account for both electricity and potential heat value streams.
- Stress-test returns against emissions compliance costs and monitoring obligations, particularly in markets where carbon pricing or MRV requirements are being phased in.
- Evaluate partners not only for capital and technology but also for permitting track record, grid interconnection experience, and ability to manage multi-year commissioning risk.
For Procurement and Municipal Decision-Makers
- Treat WTE as one element of an integrated waste and energy strategy, weighing siting, feedstock continuity, emissions performance, and heat utilization alongside disposal cost reduction.
- Structure contracts to balance long-term cost recovery with performance accountability, ensuring that operational and compliance responsibilities are clearly allocated.
- Request transparent lifecycle and emissions documentation to support public accountability and to future-proof assets against evolving regulatory definitions.
For deeper segmentation data, regional modeling, and tailored scenario analysis, the full PW Consulting research report provides expanded detail across technology pathways, application mixes, and policy-sensitive revenue drivers, along with customized recommendations aligned to specific operational and investment profiles.
For detailed analysis of this topic, please visit the official page: Waste to Energy (WTE) (Waste-to-Energy) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


