



Wind Lidar Market 2026: Beyond the 9.3% CAGR Story

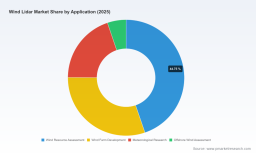
Wind Lidar Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Landscape and Structural Shifts
The wind lidar market has evolved from a niche instrumentation segment into a critical enabler of modern wind energy development. Between 2020 and 2025, the market expanded steadily, reaching approximately $623 million in revenue. The trajectory accelerates into the forecast period, with projected growth to over $1.1 billion by 2032 and a compound annual growth rate of 9.3 percent. This expansion reflects a structural shift rather than a cyclical upswing. Wind lidar is no longer treated as an optional measurement tool; it is increasingly embedded in resource assessment, power performance validation, and operational optimization across onshore and offshore projects.
Three dynamics define the current market inflection point. First, standardization is maturing. The publication of IEC TS 61400-50-4:2025 for floating lidar systems, alongside continued validation of nacelle-mounted and ground-based systems under IEC 61400-50-2, is shifting lidar from demonstration-grade instrumentation to bankable measurement infrastructure. Second, deployment models are diversifying. Ground-based profiling, nacelle-mounted sensing, and scanning architectures are converging in project workflows, creating overlapping use cases that blur traditional product boundaries. Third, the value proposition is expanding beyond data acquisition. Lidar-derived wind profiles are increasingly integrated into analytics services, risk modeling, and turbine control optimization, turning hardware sales into recurring data and service relationships.
At the same time, fragmentation remains visible. The top three competitors account for roughly 28 percent of market revenue, and the top five reach about 36 percent. This concentration indicates a market where incumbents hold meaningful credibility and certification advantages, yet there is still ample room for specialized players, regional expanders, and service-led hybrids. The absence of a single dominant platform strategy means competitive advantage is increasingly determined by certification coverage, deployment reliability in harsh environments, integration with project development workflows, and the ability to translate measurements into financial confidence.
For decision makers, the implication is straightforward: wind lidar is transitioning from a procurement line item to a strategic data layer. Companies that treat it as a commodity risk underinvesting in validation, integration, and service continuity. Companies that treat it as a platform for bankable uncertainty reduction and operational insight are better positioned to capture the margin and loyalty that come with trusted measurement outcomes.
PW Consulting Information & Electronics Research Center
Core Growth Drivers
Technical Innovation and Measurement Confidence
Measurement confidence is the central technical driver. Continuous-wave and pulsed Doppler architectures are both advancing, but the commercial prize now sits in demonstrated classification, range, and uncertainty performance under independent testing. Recent product launches have emphasized wider effective range and reduced uncertainty at certified test sites, which directly addresses the financing and yield-risk questions that have historically constrained lidar adoption. Compact, low-maintenance designs are also widening applicability in boundary-layer meteorology, aviation safety, and harsh-environment offshore settings.
Equally important is the shift from single-point measurement to integrated profiling and scanning. Scanning lidar systems are enabling more detailed spatial characterization, while nacelle-mounted sensors are moving toward real-time performance monitoring and turbine control support. This dual expansion—higher accuracy for bankable assessment and faster feedback for operational optimization—creates a broader addressable market than either use case alone.
Policy, Regulation, and Certification as Adoption Accelerators
Standards and certification frameworks are becoming practical adoption triggers rather than abstract compliance requirements. The release of floating lidar guidance supports offshore measurement plans that were previously difficult to standardize, while ongoing alignment efforts across IEC and IEA Wind working groups are reducing ambiguity in scanning lidar methodologies. In parallel, recognized validation pathways from DNV and WindGuard continue to shape procurement decisions, particularly where lenders and developers require defensible uncertainty budgets for resource assessment and power curve measurements.
This regulatory maturation matters commercially because it lowers transaction risk. When measurement systems carry clear classification and independent validation, developers can use lidar earlier in project design, financiers can accept tighter uncertainty assumptions, and manufacturers can compete on demonstrated performance rather than narrative. In offshore wind especially, standardization is unlocking measurement approaches that were previously too uncertain to justify at scale.
Demand-Side Reorientation Toward Risk Reduction and Operations
On the demand side, the strongest pull comes from project developers and turbine operators seeking to reduce uncertainty at multiple stages. For new developments, lidar supports faster site characterization and more credible wind resource narratives, which can compress development timelines and improve financing conditions. For operating assets, nacelle-mounted lidar is increasingly used for performance monitoring, wake-aware optimization, and maintenance planning. The commercial logic is simple: better measurement data can reduce overdesign, improve availability, and support data-driven operational decisions.
A related shift is the growing use of lidar data as an input to analytics services. Rather than selling hardware as an isolated product, some players are bundling measurement with wind profile analytics, resource modeling support, and interpretive services. This reflects a demand-side preference for outcomes over instruments. Developers want defensible data packages and actionable insight, not just raw measurements. That preference is reshaping product roadmaps and go-to-market models across the segment.
Supply-Side and Cost-Structure Evolution
On the supply side, scale and manufacturing maturity are improving unit economics for certain product categories. High-volume production capability, combined with established certification portfolios, is helping some manufacturers serve global turbine OEM demand more efficiently. At the same time, the market is seeing differentiated cost structures: incumbents with strong certification and service networks command credibility premiums, while newer or region-focused players compete on specialization, lead time, and application fit.
This divergence matters because cost leadership alone is rarely decisive in bankable measurement applications. Buyers weigh total cost of assurance, not just instrument price. That includes calibration support, deployment robustness, data quality documentation, and the ability to meet lender or insurer expectations. Suppliers that optimize only for hardware cost may win tactical deals but lose strategic positions where measurement credibility determines procurement choice.
Competitive Positioning and Strategic Divergence
The competitive field is defined less by sheer vendor count than by differentiated positioning around measurement type, deployment context, and customer outcome. A clear split is emerging between specialist lidar manufacturers and broader instruments or analytics players, with the specialists generally competing on class-leading classification, application-specific hardware, and certification depth, while the broader players compete on integration, service reach, and multi-sector applicability.
Several strategic profiles stand out. Specialist continuous-wave and pulsed lidar providers with strong onshore, offshore, and nacelle-mounted portfolios compete on certified measurement range and deployment flexibility. Their advantage typically rests on recognizable classification performance, global deployment experience, and product lines that map directly to resource assessment and power performance testing. In this profile, credibility is built through demonstrable compliance and repeatable field results rather than brand breadth.
Worldwide 3D Scanning Wind Lidar Market
Another profile centers on Doppler lidar families used across wind energy, aviation, and meteorology, with nacelle-mounted and ground-based variants validated for bankable offshore data. This positioning leverages cross-sector engineering heritage and the ability to serve multiple institutional buyers, which can support scale and long-term service relationships. The commercial logic is to use broad validation and application coverage to become the default measurement option in projects where lenders and operators want familiar, defensible technology.
A third profile emphasizes compact, low-maintenance pulsed Doppler systems for boundary-layer meteorology, aviation safety, and wind energy, with an emphasis on harsh-environment operation. Here differentiation comes from robustness, ease of deployment, and suitability for demanding field conditions. That positioning can be especially valuable where maintenance access is costly or where measurement continuity is critical.
There is also a growing role for nacelle-focused sensing specialists that tie lidar directly to turbine performance monitoring and optimization. One notable pattern is deep integration with major turbine install bases, where nacelle-mounted sensors are used not only for measurement but also for ongoing performance management. In such cases, market position is reinforced by installed-base relationships and the ability to convert operational data into product and service stickiness.
Beyond hardware specialists, some players are moving toward lidar-enabled data services that combine measurement with resource analytics. This service-oriented approach reflects a broader industry preference for solution-level value, particularly where buyers want interpretable wind profiles and modeling support rather than a standalone instrument. The trend suggests that competitive advantage will increasingly depend on how well a vendor can connect hardware, validation, and analytics into a coherent customer outcome.
Looking at market evolution, three patterns are likely to shape the next phase. First, consolidation pressure will remain moderate rather than aggressive. The market is still fragmented enough that specialized leaders can grow through certification, geographic expansion, and application depth without immediate pressure to merge. Second, differentiation will tilt toward integration and validation. Vendors that can align hardware, certification, and service delivery with project finance and operations workflows will capture more value than those competing primarily on feature lists. Third, new entrants and regional players will continue to find niches, especially where local deployment support, specific environmental conditions, or OEM relationships create addressable pockets that global incumbents do not fully cover.
Forward Outlook: Three Strategic Trends for 2026–2032
Trend 1: Offshore Measurement Standardization as a Growth Catalyst
Offshore wind assessment is poised to become one of the strongest growth vectors for wind lidar, and standardization is the key enabler. Floating lidar guidance and improved nacelle and ground-based validation reduce the uncertainty that has historically made offshore measurement expensive and slow. As developers pursue larger offshore programs, the ability to deploy repeatable, certified measurement systems will support both early-stage resource assessment and later-stage performance validation. The commercial opportunity lies in turnkey offshore measurement packages that combine instrument selection, deployment logistics, validation documentation, and data interpretation into a single buyer-facing workflow. The principal risk is execution complexity: offshore deployments remain sensitive to logistics, weather windows, and integration with met mast or other complementary measurement strategies, so reliability and service readiness will separate winning offerings from marginal ones.
Trend 2: From Bankable Assessment to Operational Intelligence
The market is likely to shift further toward lidar as an operational data source, not just a project development tool. Nacelle-mounted sensors and scanning systems can feed performance monitoring, wake analysis, and turbine control support, creating value after construction as well as before it. This extends the revenue relationship beyond the measurement campaign and aligns lidar more closely with asset life-cycle economics. The opportunity for manufacturers and service providers is to design products and service contracts that support recurring use, data continuity, and integration with turbine control or asset management systems. The risk is that operational integration raises expectations for reliability, cybersecurity, and data governance, which can increase the cost of customer acceptance if not managed early.
Trend 3: Service-Adjacent Competition and Outcome-Based Buying
A third trend is the growing importance of analytics-enabled services and outcome-based buying. Customers increasingly evaluate lidar on the confidence it provides for financing, design, and operations, and they are more receptive to offerings that include data interpretation, uncertainty support, and workflow integration. This creates room for hybrid business models that combine hardware sales with service subscriptions, analytics partnerships, or interpretive support. The strategic challenge is that outcome-based competition rewards vendors with strong documentation, validation track records, and customer-facing expertise. Companies that compete only on instrument specifications may find themselves squeezed by suppliers who can better translate measurements into financial and operational assurance.
Strategic Actions for Decision Makers
For Manufacturers and Technology Providers
Invest in certification breadth and independent validation as core commercial assets, not just engineering milestones. In bankable measurement markets, demonstrable classification, documented uncertainty, and recognized validation pathways often matter more than incremental feature additions. Product roadmaps should prioritize the deployment contexts that financiers and developers most trust, including offshore measurement, nacelle-mounted performance use, and harsh-environment profiling. Equally important is designing for service continuity: calibration support, field robustness, and data-quality documentation can be as decisive as hardware performance in repeated procurement decisions.
Manufacturers should also evaluate business model expansion carefully. Where customers want outcomes rather than instruments, analytics partnerships, interpretive services, or structured data offerings can strengthen positioning and reduce direct hardware commoditization. The goal is to increase the measure of trust and usefulness in each deployment, which supports both pricing power and repeat business.
For Investors and Strategic Backers
Focus on vendors that can convert technical credibility into repeatable procurement. The most attractive opportunities are likely in companies with clear certification alignment, defensible deployment records, and strong fit with offshore and operational use cases. When evaluating candidates, look beyond top-line growth and assess whether the business can sustain validation leadership, service quality, and customer integration at scale. Supply-side scale can improve competitiveness, but in this market it is usually most valuable when paired with certification depth and customer-facing reliability.
Investors should also monitor the shift toward service-adjacent models. Companies that can package measurement with analytics or workflow integration may capture more durable value than those that remain purely hardware-focused, but the execution burden is higher. Due diligence should therefore weigh data handling, customer support, and the ability to satisfy lender or insurer expectations, not just product catalogs.
For Buyers, Developers, and Procurement Teams
Treat lidar selection as a risk-management and workflow decision, not just a procurement exercise. Specify measurement requirements around certification status, validated uncertainty, deployment environment, and data deliverables, and align those requirements with the stage of the project. For resource assessment, prioritize instruments and service packages that support bankable documentation and lender acceptance. For operational use, prioritize integration, reliability, and ongoing support over one-time instrument cost.
Procurement teams should also consider total assurance cost. That includes training, deployment logistics, maintenance, calibration, and the quality of interpretive support. A lower hardware price can be misleading if it increases uncertainty, delays project milestones, or weakens data defensibility. In practice, the strongest procurement outcomes usually come from vendors who can demonstrate consistent measurement quality and support the buyer's downstream decision process.
Conclusion
The wind lidar market is entering a phase where growth is increasingly tied to credibility, standardization, and integration rather than instrument novelty alone. Revenue expansion from the mid-six-hundred-million-dollar range toward more than a billion dollars by the early 2030s reflects a broader transformation in how wind projects are measured, financed, and operated. The companies and buyers that win in this environment will be those that understand lidar as part of a bankable data and service ecosystem, not as an isolated sensor.
For a detailed view of segment-level sizing, regional dynamics, application splits, and company-level positioning, the full market report provides deeper breakdown and tailored implications. The opportunity now is to align product strategy, investment thesis, or procurement planning with the standardized, outcome-focused direction the market is already taking.
Light Detection and Ranging (LIDAR) Market
For detailed analysis of this topic, please visit the official page: Wind Lidar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


