



Vitamin A Market Insights: Beyond the 5.5% CAGR Story

Vitamin A Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global Vitamin A market has demonstrated consistent growth over the past five years, expanding from approximately 520 million USD in 2020 to an estimated 665 million USD in 2025. This trajectory reflects a compound annual growth rate of roughly 5.5 percent through the 2026 to 2032 forecast period, positioning the market to approach nearly 970 million USD by the end of the decade. The steady expansion is underpinned by broad demand across nutrition, feed, and fortification applications, yet the industry is navigating a period of structural transition that demands strategic attention from market participants.
One of the most pressing challenges lies in the evolving regulatory and trade landscape. Recent policy shifts in major economies have introduced both protections and constraints for vitamin supply chains. The exemption of Vitamin A from new U.S. tariffs and reciprocal duties under Annex II of recent executive orders has insulated producers from cost volatility that has affected other commodity categories. At the same time, extended regulatory shutdowns at key production facilities, particularly the vitamin A precursor plant in Ludwigshafen, Germany, have constrained EU-origin supply and elevated prices among established suppliers. These dynamics create a fragmented operating environment where regional availability and pricing stability are no longer guaranteed.
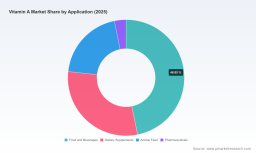
A second challenge centers on the tension between natural and synthetic product segments. The market is split between natural Vitamin A sources and synthetic variants, with synthetic products accounting for a larger share of overall revenue. This division is not merely a matter of preference; it reflects deeper questions about sourcing sustainability, consumer perception, and formulation performance. Natural carotenoid-derived Vitamin A has gained traction in food, beverage, and dietary supplement applications, while synthetic forms continue to dominate in animal nutrition and industrial fortification. Companies must navigate the strategic implications of this bifurcation as downstream customers increasingly seek transparency and differentiation in their ingredient portfolios.
The third significant challenge is market concentration. A relatively small group of manufacturers commands a disproportionate share of the market, creating both stability and vulnerability. While concentrated supply ensures quality consistency and technical expertise, it also amplifies the impact of production disruptions, capacity constraints, or strategic decisions by a handful of firms. Buyers and investors alike must account for this concentration when evaluating supply resilience and long-term pricing dynamics.
PW Consulting
Key Growth Drivers
Several interconnected forces are shaping the direction of the Vitamin A market and creating distinct pathways for value creation.
Technological Innovation and Product Formulation
Advancements in microencapsulation and combined formulation technologies are redefining how Vitamin A is delivered across applications. Recent product launches illustrate this shift. A next-generation microencapsulated combined Vitamin A and D3 formulation has been introduced with an extended shelf life under standard storage conditions, addressing long-standing stability challenges in animal nutrition. Such innovations reduce waste, improve handling efficiency, and enable more precise dosing, which in turn supports adoption in cost-sensitive feed markets while also opening doors in human nutrition where stability and bioavailability are critical.
Beyond microencapsulation, the broader trend toward tailored vitamin formulations is gaining momentum. Manufacturers are increasingly moving from commoditized bulk vitamin supply toward value-added solutions that address specific application requirements, whether that means enhanced heat stability, improved mixing characteristics, or compatibility with complex feed matrices. This shift encourages differentiation and supports margin preservation in a market where basic vitamin ingredients face periodic pricing pressure.
Regulatory and Policy Environment
The regulatory backdrop is a decisive factor in market dynamics. The exemption of Vitamin A from recent U.S. tariff actions, including 20 percent duties under specific statutory provisions, has preserved cost stability for producers and downstream users. Most key vitamins, including Vitamin A and a broad range of B-complex and other essential nutrients, are fully exempt from these duties under relevant sections of recent trade policy directives. This exemption reduces the risk of supply chain disruption and supports uninterrupted production scheduling for feed, food, and pharmaceutical applications.
Vitamin D Market
However, regulatory divergence across regions introduces complexity. The extended regulatory shutdown at a major German production site has constrained EU-origin supply, pushing buyers to reconsider sourcing strategies and inventory planning. Such disruptions underscore the importance of regulatory monitoring and the need for flexible procurement models that can adapt to shifting compliance timelines and regional availability.
Demand-Side Shifts in Consumer and Corporate Behavior
Demand patterns are evolving as consumer awareness of nutrition and wellness continues to rise, particularly in food and beverage and dietary supplement categories. Fortification trends are expanding beyond traditional staples into functional foods, beverages, and specialized supplement formats, where Vitamin A plays a supporting role in product positioning and nutritional labeling. In animal feed, the drive for efficient livestock production and balanced nutrition sustains steady demand, while also pushing formulators toward combined vitamin solutions that streamline inclusion rates and improve overall feed performance.
Corporate behavior is also shifting toward greater supply chain resilience. Buyers are increasingly prioritizing suppliers who can offer consistent quality, transparent sourcing, and contingency options. This preference favors established manufacturers with diversified production footprints and technical service capabilities, while also creating openings for newer entrants that can address niche requirements or regional demand gaps.
Supply Chain and Cost Structure Dynamics
Cost structures in the Vitamin A market are influenced by raw material availability, energy inputs, and the geographic concentration of manufacturing capacity. The exemption of Vitamin A from recent tariff pressures has provided a degree of protection, but other cost factors remain in play. Energy costs, logistics constraints, and the operational status of key precursor plants all contribute to pricing variability. The continued shutdown at the Ludwigshafen facility, for example, has elevated prices among established suppliers and reinforced the strategic importance of alternative sourcing routes.
Supply chain resilience is increasingly tied to the ability to manage multi-regional production and distribution. Companies that can balance capacity across regions, maintain buffer inventory where appropriate, and align formulation strategies with regional regulatory realities are better positioned to navigate cost volatility and supply interruptions.
Competitive Landscape and Leading Strategies
The competitive environment is defined by a mix of large-scale synthetic vitamin producers, specialized natural ingredient suppliers, and regional manufacturers with growing international reach. The market is moderately concentrated, with a small group of firms accounting for a significant portion of total revenue. This structure rewards scale, technical capability, and the ability to serve multiple application segments.
Strategic Positioning of Key Players
BASF SE, headquartered in Ludwigshafen, Germany, maintains a leading position in synthetic Vitamin A production for animal nutrition and human fortification. Its recent focus on combined microencapsulated formulations, including a next-generation Vitamin A and D3 product with extended shelf life, reflects a strategy oriented toward formulation differentiation and application-specific performance. By investing in dedicated formulation capabilities within its Verbund site, BASF is reinforcing its role as a solutions provider rather than a commodity supplier.
DSM-Firmenich AG, based in Delft, Netherlands, operates as a major supplier of Vitamin A and derivatives across nutrition and feed applications. The company maintains active portfolio management and market updates, signaling a strategy that emphasizes responsiveness to market conditions and regulatory developments. Its presence across multiple downstream categories supports diversification and provides visibility into shifting demand patterns.
Vitamin Market
Bluestar Adisseo Company, headquartered in Shanghai, China, is a key manufacturer of synthetic Vitamin A products for global feed and food markets. Its strategic value lies in its ability to serve large-volume demand while navigating regional production dynamics. As Asian demand continues to grow, manufacturers with strong regional footprints and export capabilities play an increasingly important role in balancing global supply.
Fenchem Biotek Ltd., also based in China, is an active producer of Vitamin A and related ingredients for industrial and nutritional applications. Its positioning reflects the broader trend of regional manufacturers expanding their ingredient portfolios and seeking integration into global supply chains.
Lycored Ltd., headquartered in Israel, supplies natural carotenoid-derived Vitamin A for food, beverage, and dietary supplement markets. Its focus on natural sourcing aligns with growing consumer and brand preferences for clean-label and traceable ingredients, differentiating it from synthetic-focused competitors and creating niche opportunities in premium fortification and supplement applications.
Market Evolution and Emerging Dynamics
The competitive landscape is evolving along several axes. Integration among large-scale producers continues to reinforce scale advantages in synthetic vitamin production, while differentiation is increasingly driven by formulation technology, application expertise, and regional supply reliability. At the same time, natural ingredient suppliers are carving out distinct positions by addressing demand for transparency and plant-based or carotenoid-derived alternatives.
New entrants and regional manufacturers are gaining relevance where they can offer cost-competitive supply, localized service, or specialized product attributes. However, the concentrated nature of the market means that new entrants must navigate barriers related to production scale, regulatory compliance, and customer qualification processes. The result is a market that rewards both scale and specificity, with successful players often combining broad application coverage with targeted technical differentiation.
Future Trends and Commercial Opportunities
Looking ahead to the 2026 to 2032 period, several trends are likely to shape the Vitamin A market and its commercial opportunities.
Trend One: Formulation-Led Differentiation Will Intensify
As basic vitamin ingredients face periodic pricing pressure and supply variability, the value shift toward tailored formulations is expected to deepen. Microencapsulation, combined vitamin products, and application-specific stabilizers will become more central to competitive positioning. Manufacturers that can offer formulations with extended shelf life, improved stability under processing conditions, and easier integration into feed or food matrices will capture incremental value and strengthen customer loyalty. This trend creates opportunities for suppliers to move up the value chain and for buyers to reduce total cost of ownership through improved performance and reduced waste.
Trend Two: Regional Supply Rebalancing and Sourcing Flexibility
Regulatory disruptions and production constraints in key regions are likely to accelerate efforts to rebalance supply across geographies. Buyers will increasingly seek multi-source strategies, regional inventory buffers, and supplier partnerships that provide continuity during compliance or operational interruptions. This rebalancing favors manufacturers with diversified production footprints and transparent supply chain practices. It also creates opportunities for regional producers to strengthen their role in global supply networks, particularly where they can offer reliable quality and responsive service.
Trend Three: Natural and Synthetic Segments Will Continue to Coevolve
The coexistence of natural and synthetic Vitamin A segments will remain a defining feature of the market. Natural carotenoid-derived options will continue to find traction in consumer-facing applications where clean-label positioning and traceability matter. Synthetic forms will retain strength in high-volume feed and industrial fortification markets where cost efficiency and performance consistency are paramount. The commercial opportunity lies in understanding where each segment adds the most value and in building portfolios or sourcing strategies that align with downstream customer priorities.
Risks and Uncertainties
Several uncertainties warrant attention. Extended regulatory shutdowns or new compliance requirements at major production sites could further constrain supply and elevate pricing. Trade policy changes, while currently favorable for Vitamin A through tariff exemptions, remain subject to revision and could introduce new cost dynamics if exemptions are altered. Demand shifts in animal feed, driven by livestock market conditions or alternative nutrition strategies, could affect volume growth in key segments. Finally, the concentrated supplier base means that strategic decisions by a small number of firms can have outsized effects on availability and pricing, requiring buyers and investors to maintain contingency planning and diversified sourcing approaches.
Actionable Insights for Decision-Makers
For manufacturers and suppliers, the priority is to strengthen differentiation through formulation capability and application expertise. Investing in microencapsulation, combined vitamin products, and stability-enhancing technologies can support margin resilience and customer retention. Equally important is the development of flexible supply strategies that account for regional regulatory dynamics and production variability, ensuring continuity for downstream customers even when specific sites face constraints.
For investors, the market offers steady growth supported by broad demand across nutrition, feed, and fortification, but success will depend on selecting players with scalable production, regulatory agility, and the ability to serve multiple application segments. Concentration in the supplier base creates both reliability and vulnerability, making it essential to evaluate each company's production footprint, formulation pipeline, and exposure to regional disruptions. Long-term value creation is likely to accrue to firms that combine scale with differentiated product capabilities and resilient sourcing models.
For procurement and formulary decision-makers, the key is to balance cost efficiency with supply resilience. Diversifying across suppliers and regions, aligning specification requirements with realistic supply conditions, and engaging suppliers early on formulation and stability needs can reduce exposure to price spikes and availability gaps. Understanding the regulatory status of Vitamin A in key markets, including its exemption from recent tariff actions, helps inform sourcing decisions and inventory planning. Maintaining visibility into production status at major sites and monitoring regulatory developments will support more proactive procurement strategies.
For organizations seeking a deeper understanding of regional demand patterns, application-level dynamics, and customized sourcing or investment scenarios, detailed market intelligence can provide the granularity needed to translate these trends into executable plans. Comprehensive research encompassing segmentation data, competitive assessments, and scenario-based forecasting offers a practical foundation for strategic planning and risk management in a market defined by both steady growth and evolving structural complexity.
For detailed analysis of this topic, please visit the official page: Vitamin A Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


