



Digital Panel Meter Market: How 5.9% CAGR and $2.87B Growth Reshape Competition

Digital Panel Meter Market: Strategic Trends and Commercial Opportunities in an Era of Intelligent Instrumentation
The digital panel meter market has entered a phase of steady, value-driven expansion, transitioning from a commoditized component category into a strategic node within broader industrial automation and energy management ecosystems. Valued at approximately USD 1,550.0 million in 2020, the market grew to roughly USD 1,925.0 million by 2025, reflecting a compound annual growth rate of 5.9 percent across the 2020 to 2025 period. Forward projections indicate that revenue will reach USD 2,040.7 million in 2026, USD 2,189.85 million in 2027, and continue climbing to USD 2,865.0 million by 2032. This trajectory underscores a market that is no longer defined solely by incremental replacement cycles but by structural shifts in how industrial operators visualize, interpret, and act upon real-time process data.
Beneath these macro figures lies a competitive landscape characterized by moderate concentration. The top three players command roughly 31.5 percent of global revenue, while the top five account for approximately 42.6 percent. This distribution signals a fragmented middle tier where regional specialists, OEM-focused manufacturers, and emerging connectivity-driven entrants continue to compete on precision, integration ease, and total cost of ownership. The market is simultaneously consolidating around platform-oriented players while fragmenting in application-specific niches, creating a dynamic environment where strategic positioning matters as much as scale.
Several structural challenges and inflection points are reshaping how companies approach product roadmaps, pricing strategies, and channel partnerships. First, the convergence of panel metering with broader industrial control and cloud analytics is compressing the window for standalone hardware differentiation. Devices that once competed purely on accuracy or display clarity now must demonstrate seamless interoperability with supervisory systems, edge gateways, and data historians. Second, supply chain volatility and component cost fluctuations are forcing manufacturers to balance domestic production resilience with offshore cost efficiency, particularly as demand for calibrated, certified meters remains sensitive to lead times and quality consistency. Third, procurement cycles in process industries are increasingly tied to capital planning horizons that favor integrated solutions over discrete instrument purchases, shifting commercial competition from unit pricing to lifecycle value and deployment speed.
PW Consulting
Key Demand Drivers and Structural Shifts
The expansion of the digital panel meter market is being propelled by a combination of technological maturation, regulatory tightening, evolving operational expectations, and supply chain realignment. Each factor reinforces the others, creating compounding demand rather than isolated spikes.
Technology Innovation and the Connectivity Inflection
Instrumentation is shifting from localized readout devices to networked data endpoints. Recent product announcements illustrate this transition clearly. In August 2025, Fluke Corporation introduced a new series of digital panel meters emphasizing advanced connectivity features designed to improve user experience and data accessibility. Shortly afterward, in September 2025, Yokogawa Electric Corporation unveiled a cloud-based platform for real-time monitoring and data analysis of industrial applications, signaling a move toward continuous visibility rather than point-in-time measurement. By January 2026, Ditel expanded its portfolio with a Junior-D model featuring a six-digit display alongside an updated Micra M MAX line incorporating web server, Bluetooth, and MQTT capabilities. These developments are not isolated product refreshes; they reflect a broader industry pivot toward meters that can communicate natively with modern control architectures, support remote diagnostics, and reduce the friction of manual data collection.
For manufacturers, the implication is clear: accuracy and durability remain table stakes, but differentiation now hinges on protocol support, configuration flexibility, and integration with existing automation stacks. For end users, connected meters reduce downtime, simplify troubleshooting, and enable condition-based maintenance routines that were previously impractical with isolated displays.
Digital Pressure Gauges Market
Policy, Regulatory Pressure, and Energy Visibility
Regulatory and sustainability mandates are accelerating demand for precise, auditable measurement at the panel level. Energy efficiency reporting, emissions tracking, and operational compliance increasingly require granular visibility into voltage, current, temperature, and process variables. Digital panel meters that support standardized data output and reliable calibration are becoming essential components in facilities that must demonstrate continuous compliance rather than periodic snapshots.
At the same time, the push toward decarbonization and smart energy management is reshaping procurement priorities. Schneider Electric’s July 2025 strategic partnership with a leading renewable energy firm to develop smart energy management solutions incorporating digital panel meters illustrates how instrumentation is being embedded into broader energy optimization strategies. In this context, panel meters are no longer just monitoring devices; they are contributing elements in systems designed to balance load, improve efficiency, and support renewable integration.
Demand-Side Evolution in Industrial Operations
Operational expectations across manufacturing, process industries, and infrastructure are shifting toward real-time decision-making and reduced manual intervention. Plant operators increasingly expect instrumentation that can feed directly into control loops, alarm management, and analytics dashboards without extensive engineering overhead. This demand-side change favors meters that are easy to configure, support multiple input types, and can be maintained with minimal service disruption.
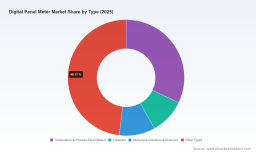
The application landscape reflects this broadening mandate. Voltage display remains the largest application segment, driven by electrical monitoring and power quality requirements. Current display continues to hold significant share, particularly in energy monitoring and motor control contexts. Temperature display maintains a dedicated role in process environments where thermal management directly affects quality and safety. A remaining portion of demand spans specialized monitoring scenarios that require multi-input handling, totalization, or custom indicator configurations. The overall pattern suggests that customers are not simply replacing legacy meters; they are upgrading measurement points to support data-driven operations and tighter process control.
Supply Chain and Cost Structure Realignment
Cost dynamics in the digital panel meter market are being reshaped by component availability, calibration requirements, and the economics of integrating communication modules. Manufacturers that rely on highly standardized internal architectures are better positioned to absorb fluctuations in sensor components, display elements, and connectivity chips. Conversely, designs that require extensive customization or proprietary interconnects face greater exposure to lead-time variability and cost escalation.
This environment is encouraging a dual strategy. Larger players are investing in modular platforms that can scale across multiple input types and communication options without redesigning core hardware. Smaller and regional manufacturers are focusing on compact, cost-effective OEM models that serve high-volume embedding scenarios where panel builders prioritize price consistency, form factor compatibility, and reliable delivery. The result is a market where scale advantages matter, but targeted application expertise and dependable supply can still secure strong positioning.
Competitive Landscape and Strategic Positioning
The competitive field spans established automation multinationals, specialized instrumentation suppliers, and regional manufacturers with strong OEM relationships. Several companies stand out for how they frame their value propositions and where they commit resources.
Established Automation and Process Players
Siemens continues to position digital panel meters within broader industrial automation and smart manufacturing platforms, emphasizing integration into control environments rather than standalone performance alone. ABB similarly focuses on high-precision meters for process and energy automation, aligning its instrumentation with industrial settings where reliability and compliance matter. Phoenix Contact reinforces a modular control systems narrative, supporting process automation through meters that fit naturally into flexible control architectures. Yokogawa ties its panel meter offerings to process instrumentation and cloud-based monitoring, extending the value proposition from measurement to analysis.
These players benefit from existing relationships with engineering teams, system integrators, and large industrial customers. Their strategic advantage lies in ecosystem compatibility, global service reach, and the ability to bundle meters into broader automation or energy management engagements. The trade-off is that their broader portfolios can sometimes prioritize platform coherence over niche cost optimization.
Specialized Instrumentation and Connectivity Leaders
Schneider Electric’s Harmony series and smart energy management orientation reflect a strategy centered on harmonizing instrumentation with energy efficiency goals and process control. Red Lion Controls emphasizes high-precision industrial panel meters for display and process instrumentation in automation and control applications, targeting users who need dependable measurement with straightforward integration. Precision Digital serves industrial and laboratory measurement contexts where accuracy and stable performance are paramount. Murata Power Solutions has focused on versatile digital panel meters for over forty years, offering DC and AC line-voltage monitoring models built around quartz crystal accuracy and self-powered operation, an approach that appeals to designers seeking reliability and simplified power requirements.
This group often competes by sharpening application specificity, reducing integration friction, and demonstrating measurable performance advantages in targeted environments. Their momentum depends on staying ahead of connectivity expectations while maintaining the precision and durability that industrial buyers require.
Digital Multimeter (DMM) Market
Regional, OEM, and Emerging Players
Autonics concentrates on compact, cost-effective OEM digital panel meters designed for industrial monitoring and measurement, an approach that aligns well with panel builders and equipment manufacturers seeking predictable pricing and standardized footprints. Guangzhou EcoNewlink Technology Co., Ltd. focuses on high-precision digital panel meters with global certification and automated OEM/ODM production for electrical panel builders, positioning itself as a scalable partner for customized volume supply. Omron Corporation maintains a steady presence in digital panel meters for industrial control and measurement applications, leveraging its broader automation and sensing ecosystem. Carlo Gavazzi targets energy and power monitoring digital panel meters with advanced connectivity, appealing to users who view measurement as part of energy management rather than isolated instrumentation.
These companies illustrate how regional strengths, certification capabilities, and OEM service models can create durable positions even in a moderately concentrated market. Their growth often depends on responsiveness, consistent quality, and the ability to support customers who need reliable meter supply without the complexity of large-platform procurement.
Recent Moves That Signal Strategic Direction
Recent activity underscores how companies are trying to shape the next phase of competition. Fluke’s August 2025 product launch emphasized connectivity and data accessibility, reinforcing a user-centric approach to measurement. Yokogawa’s September 2025 cloud platform release pointed toward continuous monitoring and remote analysis as a commercial differentiator. Schneider Electric’s July 2025 partnership with a renewable energy firm highlighted the growing link between panel instrumentation and smart energy strategies. Ditel’s January 2026 catalog expansion introduced both a compact six-digit model and an updated line with web server, Bluetooth, and MQTT support, showing how even focused manufacturers are adding communication and configuration flexibility to remain relevant.
Together, these moves suggest a market where product leadership is increasingly defined by data usability, integration readiness, and the ability to support both local display and remote insight.
Future Outlook: Three Trends Shaping the Next Three to Five Years
Looking ahead, the digital panel meter market is likely to be shaped by a small number of reinforcing trends. These trends will not only influence product development but also reshape commercial models, channel strategies, and purchasing criteria.
Trend One: From Display Devices to Data-Ready Measurement Nodes
Panel meters will increasingly be evaluated on how effectively they feed data into control, monitoring, and analytics workflows. Devices that support standard communication pathways, remote configuration, and consistent data formatting will gain preference in environments where engineering teams want to minimize integration effort. This trend creates opportunities for manufacturers that can offer modular connectivity, clear documentation, and predictable behavior across multiple input types. It also raises the stakes for suppliers whose devices require custom bridging or extensive manual setup to fit into modern automation environments.
The commercial opportunity lies in enabling faster deployment and lower total cost of ownership. Customers will reward solutions that reduce commissioning time, simplify troubleshooting, and support continuous visibility without demanding a full system overhaul. Companies that can package meters with practical integration guidance, compatible protocol support, and reliable firmware management will be better positioned to capture repeat business and expansion within existing accounts.
Trend Two: Energy Management and Compliance as Growth Multipliers
Energy visibility, efficiency reporting, and operational compliance will continue to expand the role of panel meters beyond traditional process display. As facilities invest in smarter energy management and more rigorous reporting, measurement points that support accurate voltage, current, and temperature monitoring become foundational. Partnerships and product strategies that link panel instrumentation to broader energy optimization initiatives are likely to gain traction, particularly in sectors where energy cost and sustainability performance directly affect operating margins.
This trend favors players that can articulate how panel meters contribute to energy outcomes, not just measurement accuracy. It also opens doors for integrated offerings that combine instrumentation with management software, analytics, or service models. The risk is that buyers may begin to expect these capabilities as standard, compressing margins for suppliers that treat connectivity and energy alignment as optional add-ons.
Trend Three: Modular Platforms and Targeted Nichches Co-Evolve
The market will likely continue along two parallel paths. Large platform players will extend modular architectures that can serve multiple applications with shared core designs, reducing time to market and improving consistency. At the same time, regional and OEM-focused manufacturers will deepen their positions in high-volume embedding scenarios and niche applications where cost predictability, form factor consistency, and certification support are decisive. This co-evolution creates a market where scale and specialization both matter, and where competitive advantage can come from either broad platform relevance or deep application fit.
For entrants and incumbents alike, the implication is that product strategy should be deliberately aligned with a chosen lane. Attempting to compete broadly without clear differentiation in integration, cost, or application expertise will become harder as buyers grow more sophisticated and comparison easier. The more sustainable path is to define a specific customer problem, deliver measurable advantage against that problem, and build repeatable channels around it.
Strategic Implications and Decision-Maker Priorities
The next phase of growth in the digital panel meter market will be captured by organizations that treat instrumentation as part of a broader data and operational strategy rather than as a discrete hardware purchase. The following priorities are especially relevant across different roles.
For Manufacturers and Product Leaders
- Prioritize connectivity and configuration flexibility as core design objectives, not afterthoughts. Protocols, remote diagnostics, and user-friendly setup are increasingly part of the purchase decision.
- Reduce integration friction by aligning product behavior with common control and data environments. Clear documentation, stable firmware practices, and predictable input handling can be as important as headline accuracy.
- Clarify the target lane. Decide whether the strategy emphasizes platform breadth, OEM volume supply, application-specific precision, or energy-focused monitoring, and shape pricing, certification, and channel support accordingly.
For Investors and Corporate Development Teams
- Evaluate exposure to data-ready instrumentation and energy management alignment as indicators of durable demand. Companies that can link panel meters to broader monitoring, analytics, or service models may command stronger retention and expansion potential.
- Assess supply chain resilience and certification readiness as part of due diligence. Stable quality, predictable lead times, and global certification capability increasingly influence large-scale selection decisions.
- Watch for consolidation in the middle tier, where regional and OEM-focused players may become attractive acquisition targets for firms seeking faster access to specific applications, geographies, or cost-efficient production.
For Procurement and Engineering Decision-Makers
- Evaluate total cost of ownership rather than unit price alone. Consider commissioning effort, maintenance burden, integration compatibility, and the ability to support future monitoring or analytics needs.
- Verify that chosen meters can fit into existing automation and data workflows without excessive custom bridging. Compatibility with current control architectures and standard data pathways reduces long-term operational risk.
- Require consistent calibration, certification, and documentation support. Reliable measurement integrity matters not only for operations but also for compliance and reporting obligations that are becoming more stringent.
Getting Ahead with Detailed Market Intelligence
The strategic picture is clear enough to guide near-term decisions, but execution depends on segment-level detail that sits beyond the scope of a market overview. Revenue splits by region and application, type-level growth dynamics, competitive benchmarking, pricing patterns, channel behavior, and segmentation-specific forecasts all shape the practical choices manufacturers, investors, and procurement teams face. Several additional layers of intelligence can materially improve positioning and timing.
- Segment-level sizing and growth rates that clarify where demand is accelerating, plateauing, or shifting toward higher-specification requirements.
- Regional procurement patterns and certification expectations that influence market entry timing, partner selection, and compliance investment.
- Competitive profiling that goes beyond public positioning to examine product architectures, integration strengths, channel reach, and likely response to connectivity and energy-management trends.
- Scenario-based outlooks that link supply chain conditions, regulatory developments, and automation adoption rates to demand trajectories across key segments.
For organizations that need to move from strategic direction to implementation, a detailed research baseline can shorten evaluation cycles and reduce uncertainty around segment choice, product roadmap priorities, and partnership opportunities. The most actionable insights typically emerge when high-level trends are combined with granular segmentations, company-level comparisons, and application-specific demand drivers. Readers seeking that depth can access the complete PW Consulting research report for full segmentation data, competitive assessments, and tailored guidance aligned to specific operating contexts and investment horizons.
For detailed analysis of this topic, please visit the official page: Digital Panel Meter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


