



Tracheostomy Market 2026: CAGR Insights Behind Regional and Product Shifts

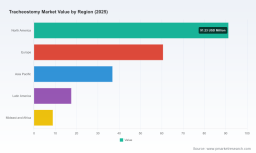
Strategic Trends and Commercial Opportunities in the Tracheostomy Market
Redefining Airway Care Through Innovation, Regulation, and Care Setting Shifts
The global tracheostomy market has reached an inflection point where steady growth meets structural transformation. Over the 2020–2025 period, revenue expanded from approximately 163 million USD to 215 million USD, with a projected compound annual growth rate of 5.67 percent through 2032, reaching an estimated 344.8 million USD by the end of the forecast horizon. This trajectory reflects more than incremental demand. It signals a market being reshaped by clinical preference shifts, evolving reimbursement dynamics, material science breakthroughs, and a competitive landscape that is both fragmented and increasingly innovative. For decision makers, understanding where growth concentrates and why requires looking past headline figures and into the underlying drivers that will determine winners over the next several years.
Market Landscape and Core Challenges
The current market is defined by a moderate but resilient expansion, anchored in critical care pathways, long-term ventilation support, and home-based airway management. Historical momentum was interrupted briefly during periods of systemic disruption, when procedural volumes dipped and supply chains strained. Since then, the trajectory has normalized and accelerated, supported by rising chronic respiratory conditions, longer survival among patients with complex airway needs, and growing adoption of tracheostomy as a pragmatic option when prolonged intubation is no longer optimal. The market’s moderate concentration—a combined share of roughly 24.6 percent among the top three players and 26.2 percent among the top five—indicates that scale advantages exist but do not dominate the entire landscape, leaving meaningful room for differentiated entrants and regional specialists.
Ostomy Products Market
Beneath this growth narrative lie several structural challenges that will shape strategy and capital allocation:
- Regulatory scrutiny and post-market accountability are intensifying. Device safety, material compliance, and adverse event reporting are drawing closer attention from regulators and hospital risk management teams. Manufacturers are increasingly evaluated not only on performance claims but also on traceability, sterility assurance, and real-world durability.
- Reimbursement design creates uneven incentives across product types and procedures. Variable payment levels for cuffed versus non-cuffed tubes, combined with procedure-level reimbursement that does not always differentiate complexity or patient risk profiles, influence product selection in ways that can favor cost efficiency over advanced features in certain settings. This complicates value-based positioning for manufacturers.
- Supply chain resilience and material quality standards remain friction points. The shift toward medical-grade materials with updated plasticizer formulations, paired with sterilization requirements and cleanroom-level manufacturing control, introduces cost and operational complexity. Volatile input costs and geographic concentration in certain materials or components can create short-term exposures for producers and buyers alike.
For executives, these challenges are not merely operational concerns. They define the boundary conditions for growth, influence competitive positioning, and determine which product strategies will hold up under reimbursement and procurement review.
Key Drivers Reshaping the Market
Technology Innovation and Product Evolution
Product innovation continues to be one of the strongest catalysts for differentiation. Flexible, cuffed and cuffless designs with disposable or reusable inner cannulas have broadened clinical options, allowing caregivers to match device characteristics to patient anatomy, secretion management needs, and care setting. Advanced cuff geometries and taper-guard designs are being integrated to improve sealing performance while reducing pressure-related complications. In parallel, percutaneous approaches have gained traction where clinically appropriate, enabling faster bedside access and shorter procedural pathways compared with open surgical techniques. These innovations are not purely technical achievements; they reframe purchasing decisions around outcomes, ease of use, and downstream care burden. For manufacturers, the most compelling value propositions now combine material reliability, procedural compatibility, and practical usability improvements that reduce total cost of care rather than only unit price.
Policy, Standards, and Regulatory Environment
Regulatory and standards frameworks play an outsized role in shaping product design and market access. Specifications for tracheostomy tubes made from plastics and rubber, including dimensional and performance requirements for specific size categories, provide a baseline that manufacturers must meet or exceed. Beyond baseline compliance, attention to materials has intensified, with updates to medical-grade PVC formulations using citrate and DEHT-based plasticizers reflecting a broader push toward safer, more stable material profiles. Recent device clearances for multiple tube variants and introducer sets highlight the importance of building regulatory readiness into product roadmaps. In the United States, 510(k) clearance activity is not a one-time event but a recurring capability that affects time-to-market, portfolio breadth, and global competitiveness. At the same time, adverse-event reporting continues to serve as an operational reality check, reminding manufacturers that post-market surveillance, complaint handling, and design vigilance are integral to long-term brand trust and market continuity.
For business leaders, the policy environment is both a constraint and a strategic lever. Companies that invest early in documentation, biocompatibility evidence, and post-market processes can reduce clearance friction and strengthen procurement credibility, especially when hospitals and group purchasing organizations are increasingly risk-averse.
Demand-Side Shifts in Clinical Practice and Patient Care
Demand is evolving as care pathways move across settings. Longer survival with chronic respiratory conditions, increased prevalence of prolonged ventilation needs, and more complex airway management cases are expanding the relevance of tracheostomy in both acute and extended care contexts. Clinicians are balancing procedural invasiveness, recovery time, and long-term airway security, which creates differentiated demand for percutaneous versus surgical approaches depending on patient profile, institutional capabilities, and staffing models. At the same time, home and long-term care settings are gaining importance as rehabilitation and chronic management become more structured, driving interest in tubes and accessories that support patient comfort, caregiver ease, and infection prevention. Clean and care kits, ventilation accessories, and related consumables are benefiting from this broader ecosystem effect, where the tube is only one part of a recurring care bundle.
PW Consulting
This demand evolution changes how products should be positioned. In acute hospitals, performance, procedural compatibility, and staff training support may matter most. In home and long-term care, durability, ease of cleaning, patient comfort, and caregiver usability become stronger differentiators. Businesses that can segment value propositions by care setting are better positioned to align with purchasing committees and clinical stakeholders.
Supply Chain, Materials, and Cost Structure Dynamics
The cost structure of tracheostomy products is influenced by material selection, sterilization methods, and manufacturing control. Medical-grade PVC, silicone, and polyurethane remain common substrate choices, with individual wrapping and ethylene oxide or gamma sterilization forming part of the standard production and distribution flow. Material updates designed to improve compliance and biocompatibility can affect both cost and performance trade-offs, while cleanroom injection molding and controlled assembly processes raise operational barriers in ways that favor disciplined manufacturers. These dynamics influence margins, lead times, and the ability to scale consistently across regions. For buyers, supply continuity, lot traceability, and sterilization validity are increasingly part of procurement review, particularly when respiratory care is treated as a critical-path service.
For manufacturers, the strategic question is whether to compete primarily on cost, on reliability and compliance, or on differentiated clinical performance. Each path demands a different operating model, supplier base, and quality investment. In a market where margins are influenced by reimbursement variability and purchasing consolidation, the ability to articulate total value—rather than unit cost alone—can determine shelf presence and contract wins.
Competitive Landscape and Leadership Strategies
The competitive field combines large diversified respiratory and surgical device players with focused airway specialists and regional manufacturers. This mix creates both opportunities and tensions. Larger participants benefit from broader portfolios, cross-selling potential, and established regulatory and commercial infrastructure. Focused manufacturers often compete through product specialization, regional relationships, and nimble portfolio updates. The result is a landscape where differentiation can come from either breadth or depth, depending on the segment and geography.
Several strategic patterns are visible among leading participants:
- Portfolio breadth anchored in recognizable tube platforms. Companies that maintain a family of flexible cuffed and cuffless tubes, including variants with disposable and reusable inner cannulas and extended-length options, can address a wide range of patient anatomies and care scenarios while keeping product lines manageable.
- Targeted regulatory wins to expand procedural applicability. Recent clearances for percutaneous introducer sets and multiple tube variants illustrate a strategy of adding procedural access tools and configuration options that broaden clinical adoption and procurement fit.
- Material and design emphasis as a trust signal. Using medical-grade materials, updating plasticizer formulations, and maintaining standardized specifications helps position products for both clinical acceptance and procurement due diligence.
- Regional manufacturing and cost-competitive offerings. Some participants build value through localized production and competitive medical-grade PVC-based tubes, which can support price-sensitive segments and distribution partnerships across diverse markets.
The market is likely to continue evolving through a mix of consolidation and segmentation rather than a single dominant shift. Larger players may pursue bolt-on capabilities in airway accessories or care kits to deepen relationships beyond the tube itself. Smaller and regional manufacturers may continue to compete where cost, speed, or local relationships matter most. Meanwhile, new entrants that can demonstrate clear differentiation in usability, safety profile, or care-setting fit will find openings, especially where incumbents are constrained by portfolio complexity or margin pressure. A notable competitive dynamic is that many buyers now evaluate devices not in isolation but as part of a workflow that includes cleaning, maintenance, patient outcomes, and staff burden. That shift favors companies that can support the full care process rather than individual product functions.
For strategists, this landscape suggests that winning is less about being the only player in a category and more about being the most credible option for a specific care context, procurement model, or geographic market. Brand trust, regulatory readiness, and post-market reliability increasingly act as gatekeepers alongside clinical performance.
Forward-Looking Trends and Commercial Opportunities
Trend 1: Care-Setting Diversification Will Reward Segmented Product Strategies
Over the next three to five years, demand is expected to continue spreading across intensive care, step-down units, rehabilitation settings, and home-based care. This diversification will place greater emphasis on product portfolios that can serve multiple environments without sacrificing usability or safety. Commercially, this opens opportunities for bundles that pair tubes with compatible accessories, cleaning and care kits, and clinician education resources. Manufacturers that design for cross-setting flexibility can capture more touchpoints in the patient journey and strengthen contract relevance with integrated purchasing groups.
The opportunity here is not simply to sell more SKUs, but to reduce switching costs for institutions that want consistent standards across departments and care transitions. Risk factors include inconsistent reimbursement support for more advanced configurations and the possibility that care-setting adoption may vary significantly by region.
Trend 2: Regulatory and Safety Expectations Will Become a Competitive Differentiator
As post-market reporting, material compliance, and adverse-event transparency remain in focus, companies that treat regulatory readiness as a core capability rather than a compliance task will gain an advantage. Clear documentation, robust sterility and traceability processes, and proactive design monitoring can shorten procurement cycles and reduce institutional hesitation. Over time, this could create a two-tier market in which credible safety and compliance narratives support premium positioning or preferred-supplier status, while undifferentiated products face greater scrutiny and substitution risk.
Tracheostomy Tube Market
The upside is meaningful for manufacturers that can link safety and usability to total cost of care. The downside is that any lapse in consistency can have outsized reputational and commercial impact, especially in critical care environments. Businesses should therefore treat quality systems and complaint surveillance as strategic assets, not back-office functions.
Trend 3: Reimbursement and Procurement Logic Will Continue to Shape Product Mix
Reimbursement variability for different tube types and procedures will keep influencing selection at the hospital and health-system level. Even when clinical factors favor a particular configuration, payment design can shift the effective economics of adoption. This creates a commercial opportunity for providers and manufacturers to align on value communication that ties device choice to staff efficiency, complication reduction, and downstream cost avoidance. Procurement decisions are likely to become more structured, with greater weight on evidence, standardization, and supply reliability.
One commercial implication is that pricing strategies alone will not win long-term positioning in many accounts. Contracts may increasingly reward solutions that reduce variability, simplify inventory, or support training and care consistency. The risk is that overly complex product portfolios can confuse procurement evaluations, while insufficient differentiation can lead to commoditization in price-sensitive segments.
Strategic Recommendations for Decision Makers
For Manufacturers and Product Leaders
- Design portfolios with care-setting segmentation in mind. Differentiate offerings for acute procedural use versus long-term and home-based management, and ensure that accessories, kits, and educational support match the intended setting.
- Treat regulatory and post-market capability as part of the product strategy. Build clearance, material compliance, and surveillance readiness into the roadmap so that portfolio expansion does not create documentation bottlenecks or quality risk.
- Invest in value storytelling that connects device features to total care outcomes. Highlight usability, complication-mitigation potential, and inventory or training simplification in ways that procurement committees and clinical leaders can act on.
For Investors and Strategic Partners
- Assess companies on their ability to combine portfolio relevance, regulatory execution, and supply reliability rather than on revenue scale alone. In a moderate-growth market, execution quality often matters more than category size.
- Look for businesses that can expand within care ecosystems—through accessories, consumables, or care-kits—because recurring touchpoints can stabilize demand and improve commercial resilience.
- Monitor material, sterilization, and post-market capability as indicators of durability. Companies with strong process control and transparent reporting are better positioned to withstand procurement scrutiny and reputation-sensitive buying environments.
For Procurement and Clinical Operations Leaders
- Align device selection with care pathways and staff workflows, not just unit economics. Standardization across settings can reduce training variability and simplify inventory while maintaining clinical fit.
- Use supplier evaluation to include traceability, sterilization consistency, material compliance, and adverse-event responsiveness. These factors increasingly affect operational risk in respiratory care.
- Evaluate total cost implications across consumables, cleaning, and maintenance, especially when recurring care bundles are involved. A lower unit price can be offset by higher downstream burden if device and accessory choices are not coordinated.
The tracheostomy market is moving from incremental growth to a more structurally differentiated phase. Clinical preference shifts, regulatory expectations, reimbursement design, and care-setting diversification are jointly reshaping where value is created and captured. Companies and buyers that anticipate these forces—and build strategies around them—will be better positioned to navigate volatility and identify durable opportunities. For decision makers seeking a deeper breakdown of segment trajectories, regional dynamics, and competitive benchmarks, the full PW Consulting market research report provides detailed segmentation data and customized strategic recommendations to support more precise planning.
For detailed analysis of this topic, please visit the official page: Tracheostomy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


