



Laser Capture Microdissection Market: Why 8.55% CAGR Changes Everything

Navigating the Laser Capture Microdissection Market: Strategic Trends and Commercial Opportunities
The Laser Capture Microdissection (LCM) market has moved past its early-adopter phase and is now entering a period of structured expansion. From 2020 through 2025, market revenue grew from approximately $178 million to $230 million, reflecting steady adoption across life sciences and clinical research settings. The trajectory through 2032 points to sustained momentum, with revenue projected to reach $383 million and a compound annual growth rate of roughly 8.55 percent. This scale is not merely a reflection of instrument sales; it signals a broader shift in how heterogeneous biological samples are interrogated. As molecular profiling becomes more precise, the ability to isolate pure cell populations from complex tissues has transitioned from a niche capability to a foundational workflow step. For executives and investors, the growth curve suggests a maturing market where differentiation, workflow integration, and reimbursement clarity will determine which players capture disproportionate share.
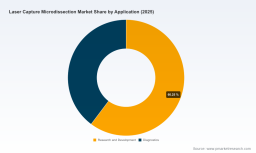
The market structure reveals meaningful concentration. A small group of established vendors holds a combined share exceeding half of total revenue, with the top three firms controlling roughly 52.5 percent and the top five reaching 64.2 percent. This concentration reflects the capital-intensive nature of LCM platforms, the importance of application-specific validation, and the long sales cycles tied to core facilities and reference laboratories. At the same time, the breakdown between instruments and consumables, along with the split between research and diagnostics applications, underscores a dual-engine market. Instruments anchor initial adoption, while recurring consumable purchases and diagnostic revenue streams create the long-term economics that sustain vendors. For decision-makers, this structure implies that competitive advantage will increasingly come from total cost of ownership, workflow compatibility, and service ecosystems rather than from hardware specifications alone.
Worldwide Tissue Microarray Market
Market Snapshot and Core Challenges
The LCM market sits at an inflection point where technical capability, operational constraints, and commercial policy intersect. Growth has been durable, but several structural challenges are shaping how quickly new customers adopt platforms and how efficiently existing users scale their workflows.
The first challenge is the persistent tension between capability and accessibility. LCM instruments remain capital-intensive, with acquisition costs that can create meaningful barriers for laboratories in emerging regions or smaller academic settings. This dynamic reinforces a concentrated adoption pattern, where well-funded core facilities and larger institutions lead deployment while smaller groups rely on shared resources or outsource isolation steps. The practical effect is a market where installed base expansion is gated not only by scientific interest but also by budget cycles, space constraints, and the availability of trained operators. As a result, vendors that can reduce operational friction—through automation, simplified sample handling, or flexible deployment models—are better positioned to extend reach beyond flagship institutions.
The second challenge is workforce and operational readiness. Even as demand for cell-specific molecular analysis rises, staffing shortages and training bottlenecks continue to temper the pace of adoption. LCM workflows require microscopy expertise, careful sample preparation, and disciplined downstream handling. In core facilities and high-throughput environments, the need for skilled personnel can become a limiting factor, especially when instrument utilization is high and turnaround expectations are tight. This operational reality is reshaping purchasing criteria. Laboratories increasingly weigh not just image quality or laser precision, but also reproducibility, ease of training, and the ability to standardize isolation protocols across users and shifts. Vendors that invest in workflow simplification, guided operation, and robust application support are effectively addressing a barrier that hardware specs alone cannot solve.
The third challenge lies in the gap between scientific utility and commercial realization. LCM has long been valued in research, but translating that value into diagnostics and reimbursed workflows has required regulatory clarity, standardization, and payer recognition. Progress is underway, but adoption in clinical settings still depends on demonstrating consistent analytical performance, integrating LCM into established pathology and molecular pipelines, and aligning with reimbursement frameworks that recognize the incremental value of targeted cell isolation. Until these elements are firmly in place, the market will continue to see a divide between research-driven demand and diagnostics-driven scale. For commercial teams, bridging that divide is less about selling instruments and more about enabling validated, repeatable workflows that meet clinical-grade expectations.
PW Consulting
Key Demand Drivers
The LCM market is being shaped by a set of reinforcing drivers that extend beyond incremental improvements in laser technology. Each driver alters the value proposition in a way that expands use cases, influences purchasing behavior, and changes the competitive basis across regions and application segments.
Technological innovation remains the most visible driver. Advances in laser control, optical integration, and automation are steadily improving precision, throughput, and contamination control. Modern systems are increasingly designed to isolate single cells, small clusters, or subcellular components with greater consistency, which directly supports downstream genomic, transcriptomic, and proteomic analyses. Equally important is the trend toward workflow integration. LCM is no longer evaluated as a standalone instrument; it is assessed as part of a larger sample-to-answer chain that includes staining, capture, nucleic acid extraction, and molecular profiling. Vendors that offer tighter compatibility with common laboratory workflows, flexible collection methods, and software tools that reduce manual steps are gaining an edge in environments where reproducibility and throughput matter. The practical implication is that innovation is shifting from pure hardware performance to integrated solutions that reduce variability and make LCM more accessible to a broader range of operators.
Regulatory and reimbursement developments are becoming a meaningful demand catalyst, particularly in the diagnostics direction. Recognition of specific billing codes for oncology-related semiquantitative analysis that includes laser capture microdissection has improved the commercial logic for clinical adoption. When payers formally acknowledge the role of LCM in enabling more precise diagnostic evaluation, laboratories gain a clearer path to justify investment and operational cost. This does not automatically unlock mass adoption, but it strengthens the business case for sites that are already considering LCM for molecular pathology, biomarker stratification, and tumor microenvironment studies. For manufacturers and service providers, this shift makes application-specific validation and documentation more valuable. The market reward increasingly goes to those who can support standardized protocols, demonstrate consistency across sample types, and help laboratories navigate the interface between research-grade flexibility and clinical-grade reliability.
Demand-side behavior is also evolving. Researchers and clinical laboratories are under growing pressure to extract more information from limited or heterogeneous samples. In oncology, neuroscience, and developmental biology, the ability to isolate defined cell populations enables analyses that would otherwise be diluted by surrounding tissue. This need is amplified by the broader move toward single-cell and spatially informed molecular methods, where sample purity and representation directly affect interpretation. At the same time, core facilities and service laboratories are facing higher expectations for turnaround, data quality, and protocol standardization. As a result, purchasing decisions are driven less by novelty and more by practical fit: the system must match the laboratory's sample volume, operator capacity, and downstream application. Laboratories that once treated LCM as a specialized tool are now evaluating it as part of a longer-term molecular strategy, which favors vendors that can support scalable, repeatable operations.
Supply-side and cost-structure dynamics add another layer of influence. The capital cost of LCM instruments remains a significant consideration, and this cost structure interacts with regional purchasing power, service availability, and consumable economics. In higher-budget markets, adoption is often driven by the availability of dedicated funding, shared infrastructure, or clinical programs that can absorb upfront investment. In lower-budget environments, the decision is more sensitive to total cost of ownership, maintenance requirements, and the availability of consumables over time. This divergence is encouraging a more pragmatic competition. Vendors are increasingly differentiating through service models, consumable pricing, training support, and regional availability of application specialists. The operational lesson is that durable market success depends on aligning pricing and support with the realities of laboratory budgets, staffing, and local infrastructure.
Competitive Landscape and Leading Strategies
The LCM market is defined by a relatively concentrated group of established players, each pursuing a distinct positioning strategy. While the leaders share core capabilities in laser-based isolation, their differentiation lies in how they connect hardware, software, consumables, and application support to specific customer needs.
Thermo Fisher Scientific has a long-standing presence in the space through its Arcturus LCM systems, kits, reagents, and slides designed for isolating specific cells from heterogeneous tissue via infrared and ultraviolet laser approaches. The commercialization of the Arcturus business by Laxco illustrates an important dynamic in this market: brand, distribution, and application support can be as influential as the original instrument design. For end users, the value often comes from the availability of compatible consumables, proven protocols, and a reliable supply chain. Thermo Fisher's broader commercialization strength gives it a structural advantage in reaching large laboratory networks, integrating LCM into wider procurement relationships, and supporting standardized workflows across multiple sites.
Worldwide Laser Capture Microdissection (LCM) Market
Molecular Machines & Instruments has positioned itself around precision and contamination-free isolation, with CellCut systems and automated CellRobot options that support single cells, cell clusters, or subcellular components across varied tissue types. This emphasis on automation and contamination control targets laboratories where reproducibility, clean handling, and throughput are central concerns. The strategic message is clear: LCM is not only about capturing the right cells, but also about doing so in a way that minimizes variability and protects downstream analysis. In highly controlled research and clinical environments, that positioning can be a strong differentiator.
Carl Zeiss and Leica Microsystems both leverage deep optical heritage, but they apply it in slightly different ways. Zeiss's PALM systems are integrated with microscopes for cutting and recovering viable cells from tissue cultures and fixed material, emphasizing integration with established imaging workflows in life sciences and research. Leica's LMD6 and LMD7 systems focus on high-precision lasers for cutting and collecting defined microscopic areas into collection vessels for downstream molecular analysis. Leica's continuing investment in demonstrations and user engagement, including recent on-site demonstrations at academic imaging cores, reflects a strategy centered on hands-on validation, trusted relationships with core facilities, and visible support for active research environments. This approach reinforces the idea that LCM adoption is influenced not only by specifications, but also by local proof points, operator familiarity, and the credibility of application support.
Laxco has carved out a position around accessible infrared laser capture with the Accuva Cellect system, emphasizing isolation of cells of interest while preserving adjacent cell integrity. This focus on selective capture and sample preservation speaks to laboratories that need clean separation without compromising the broader specimen context. For some users, that balance is a practical requirement, especially when comparative morphology or adjacent tissue architecture remains relevant to interpretation. Laxco's trajectory also highlights how specialized commercial entities can compete by narrowing the value proposition to specific workflow benefits rather than trying to match broader portfolio scale.
The competitive landscape is evolving along several axes. One is integration versus specialization. Larger players with broad laboratory portfolios can bundle LCM into wider purchasing relationships and offer broader service coverage, while specialized firms can move faster on niche workflow needs and application-specific optimization. Another axis is automation and reproducibility. As laboratories scale LCM use, automation, standardized collection, and software-assisted operation become more valuable, which favors vendors that can reduce operator dependence and support consistent output across users. A third axis is commercial execution in diagnostics. Companies that can help laboratories align LCM workflows with clinical expectations, documentation, and reimbursement considerations are likely to gain advantage as the diagnostic segment matures.
Market consolidation and partnership activity are plausible as the segment matures. The presence of commercialized product lines, the importance of consumables, and the need for strong application support all create incentives for strategic alignment. At the same time, new entrants may find opportunities in adjacent capabilities such as software-driven workflow management, automated sample handling, or integrated extraction and analysis pipelines. The real differentiation in the next phase will likely come from end-to-end reliability: how well a vendor can support the scientific question, the operational environment, and the commercial constraints that laboratories face at the same time.
Future Trends and Commercial Implications
Over the next three to five years, the LCM market is likely to be shaped by three interconnected trends. Each carries clear commercial implications and introduces uncertainties that decision-makers should monitor.
The first trend is the shift from instrument-centric adoption to workflow-centric adoption. As LCM becomes embedded in more standardized molecular pipelines, customers will evaluate systems less as isolated hardware and more as part of a complete process that spans sample prep, targeting, capture, extraction, and downstream analysis. This shift favors vendors that can deliver compatible consumables, repeatable protocols, and software that reduces variability. It also raises the importance of service, training, and application documentation. For manufacturers, the commercial opportunity lies in building defensible recurring relationships through consumables, support contracts, and workflow packages. For laboratories, the opportunity is faster turnaround, more consistent results, and better utilization of skilled staff. The risk is that vendors who compete only on hardware features may face increasing pressure from integrated solutions that lower operational friction.
The second trend is the gradual expansion of LCM into more clinically oriented workflows. Reimbursement recognition and the demand for precise cell-level analysis in oncology and other complex diseases create a path toward broader diagnostic relevance. However, clinical adoption will depend on standardized validation, robust documentation, and alignment with laboratory operations and payer expectations. The commercial upside is meaningful, because diagnostics can create more predictable demand and strengthen the economic case for LCM in high-value settings. The uncertainty is equally important: clinical pathways are regulated, payer policies vary, and laboratory adoption can be slow unless the workflow fits existing pathology and molecular routines. Companies that invest early in application validation, clinical-grade consistency, and practical integration are better positioned to capture this opportunity than those that assume research demand alone will carry the transition.
The third trend is the broadening of access through automation, shared infrastructure, and more flexible deployment. Staffing constraints and capital costs will continue to shape where LCM is deployed, but automation and simplified operation can reduce the dependency on highly specialized operators. Core facilities, reference laboratories, and service providers are likely to remain important adoption hubs, especially in regions where individual laboratories cannot justify standalone systems. This creates an opportunity for vendors to design for multi-user environments, shared scheduling, and scalable utilization. It also opens space for new business models centered on service, outsourcing, and regional support. The potential risk is that automation and simplification may raise expectations for throughput and consistency, making performance shortfalls more visible. In that environment, vendor credibility will depend on dependable operation as much as on feature lists.
Strategic Recommendations for Decision-Makers
For manufacturers and vendors, the most effective strategy is to strengthen the full workflow value proposition rather than competing solely on laser performance or optical specifications. That means prioritizing consumables ecosystems, application-specific protocols, training pathways, and service reliability. Companies should also invest in automation and software features that reduce operator dependence and improve reproducibility across users and sites. In diagnostics-adjacent segments, validated workflows, documentation, and reimbursement-aligned messaging will become increasingly important. The commercial goal should be to make LCM easier to adopt, easier to operate, and easier to sustain over time, because those attributes drive both initial sales and long-term recurring revenue.
For investors, the market offers a profile of steady growth with concentration risk and meaningful operational dependencies. The durable CAGR and expanding use cases support a constructive long-term view, but returns will likely depend on which companies can capture recurring consumable demand, expand into clinically relevant applications, and manage service and support efficiently. Pay close attention to reimbursement developments, staffing dynamics, and the pace at which automation reduces adoption barriers. Companies that demonstrate strong application support, reliable supply chains, and credible clinical or core-facility relationships are better positioned than those relying primarily on hardware differentiation. As always, the key is not just market growth, but which players convert growth into defensible economics.
For procurement leaders and laboratory managers, the priority should be to evaluate LCM systems against operational reality rather than headline specifications. Total cost of ownership, consumable availability, training burden, multi-user support, and compatibility with downstream molecular workflows should carry substantial weight. Where internal staffing is limited, shared-facility access, service contracts, and automation features may outweigh marginal performance gains. Where diagnostic or high-stakes research applications are involved, protocol validation, repeatability, and vendor support should be treated as core purchasing criteria. The best outcome comes from selecting a platform that fits the laboratory's actual throughput, personnel profile, and downstream needs, rather than one that simply offers the most impressive technical feature set.
The LCM market is moving from specialized capability to a more mainstream enabler of precise molecular analysis. That transition creates opportunities for vendors who can integrate hardware, consumables, and support into reliable workflows, for investors who understand where recurring value is being built, and for laboratories that can align adoption with operational and clinical realities. Given the pace of reimbursement change, automation progress, and competitive repositioning, a detailed look at region-specific dynamics, application splits, pricing structures, and vendor-specific benchmarks can make the difference between a good strategic decision and a great one. For a more complete view of the segment data, competitive benchmarks, and forward scenarios, exploring the full PW Consulting research report can provide the level of detail needed to shape procurement plans, investment theses, and product strategy with greater confidence.
For detailed analysis of this topic, please visit the official page: Laser Capture Microdissection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


