



Organic PVC Stabilizers Market Transforms as Construction & Asia Pacific Drive Sustained Growth

Navigating the Organic PVC Stabilizers Market: Strategic Trends and Commercial Opportunities (2025–2032)
The global organic PVC stabilizers market is entering a phase of structural transition, where growth is no longer defined solely by volume expansion but by a complex interplay of regulatory pressure, raw material volatility, and strategic buyer behavior. Over the historical period from 2020 to 2025, the market moved through uneven cycles, reflecting broader macroeconomic shocks, supply chain recalibration, and shifting demand patterns across key downstream sectors. Looking ahead to the forecast window of 2026 through 2032, the trajectory points toward a compound annual growth rate of 2.2%, with the overall market expected to expand from a base value in 2025 to a significantly larger scale by the end of the projection period. While the absolute figures suggest steady expansion, the real story lies in how value is being redistributed across chemistry types, application verticals, and geographic corridors.
For executives and investors tracking this space, the headline growth rate masks a market where competitive positioning increasingly depends on formulation innovation, compliance readiness, and the ability to manage input cost swings. The organic stabilizers segment is being reshaped by forces that extend well beyond conventional polymer additive economics, and companies that treat this as a commodity-driven category risk missing the strategic inflection points now taking shape.
Market Structure and the Core Challenges Ahead
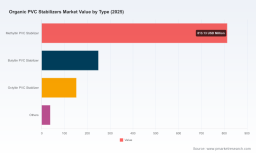
The organic PVC stabilizers market is characterized by a moderately concentrated competitive field, with the top three players accounting for roughly half of overall revenue and the top five capturing approximately sixty percent. This level of concentration suggests that scale advantages, formulation IP, and established customer relationships still matter, but it also leaves meaningful room for specialized entrants and regional specialists to compete on performance, service, and sustainability credentials. The revenue base is anchored by methyltin chemistry, which commands the largest share, followed by butyltin and octyltin systems, with other formulations making up the remainder. On the application side, construction materials and packaging materials together form the backbone of demand, while medical instruments and other end-use segments contribute smaller but strategically important volumes. Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with no single region dominating to the point of eliminating regional differentiation.
Worldwide Plastic Stabilizer Market
Against this backdrop, several structural challenges are redefining how participants operate and plan.
- Lead substitution is no longer a compliance checkbox but a market reality. Regulatory frameworks such as EU REACH and China’s GB standards are accelerating the displacement of traditional lead-based systems in favor of organic and bio-based alternatives. This shift is irreversible in most high-value applications, forcing both incumbents and new entrants to invest in lead-free architectures rather than treating them as optional upgrades.
- Raw material cost pressure is compressing margins and forcing formulation strategy adjustments. Since the first quarter of 2023, calcium-based compounds used in organic stabilizer systems have experienced price increases in the range of forty-two percent, while zinc derivatives have seen cost increases around thirty-seven percent amid global supply chain disruptions. These movements are not temporary blips; they are reshaping cost structures and pushing buyers to weigh total cost of ownership against unit price.
- The willingness to pay for performance and longevity is being tested by buyers with tighter procurement budgets. Organic PVC stabilizer systems typically command a price premium of twenty-five to forty percent over traditional lead-based alternatives, a gap that can be justified by extended service life and regulatory safety, but only when value communication is clear and consistent across the value chain.
These challenges converge into a single strategic message: the market is moving from a price-and-specification dynamic toward one where compliance, lifecycle value, and supply resilience determine competitive outcomes. Companies that continue to compete purely on unit cost are likely to face shrinking headroom as regulatory expectations and input volatility become more entrenched.
Key Drivers Reshaping the Market
The forward direction of the organic PVC stabilizers market is being shaped by four interconnected forces: chemistry innovation, regulatory momentum, demand-side behavior changes, and supply chain restructuring. Each driver carries implications that extend beyond incremental growth and into the question of which business models will be durable over the next several years.
Technology and formulation innovation remain the most powerful lever for differentiation. The move away from petroleum-based thiols toward bio-based ligands derived from vegetable oils, castor oil, and agricultural residues is gaining traction as part of a broader push to reduce dependency on fossil feedstocks while maintaining stabilization performance. This is not a purely academic exercise; it responds directly to downstream buyers who are under pressure to lower the carbon footprint of their own products and who increasingly view additive origins as part of their sustainability reporting. At the same time, high-efficiency heat stabilizer architectures continue to improve for PVC pipes, fittings, rigid film, and exterior-grade applications, enabling formulators to achieve better processing stability and longer service life without reverting to older chemistries. The practical impact is that innovation is becoming a credibility signal as much as a performance advantage.
Policy and regulatory pressure is acting as a hard boundary for legacy solutions. The substitution toward bio-based and organic stabilizers is being reinforced not by a single regulation but by a converging set of standards and buyer expectations. In markets where lead-based systems were once economically attractive, the compliance cost of continuing with them is rising faster than the cost of switching, particularly for applications that intersect with consumer-facing, food-contact, or construction safety regimes. This is changing the conversation from “what is cheapest today” to “what can remain viable through the next audit cycle and customer specification review.”
PW Consulting
Demand-side behavior is evolving as both consumers and enterprises become more attentive to material safety and lifecycle durability. Construction specifiers, packaging converters, and medical device manufacturers are not simply looking for pass/fail compliance; they are increasingly interested in systems that reduce long-term degradation, simplify material declarations, and align with broader ESG narratives. This creates a market where organic stabilizer suppliers can win on value storytelling and technical support, especially when they can demonstrate extended service life and consistent performance under demanding conditions.
Supply chain and cost structure changes are forcing both procurement and R&D to adapt simultaneously. The sharp increases in calcium and zinc-based inputs have exposed the vulnerability of formulations that depend heavily on specific commodity derivatives. In response, some players are pursuing broader supplier diversification, dual-sourcing strategies, and formulation flexibility that allows partial substitution without sacrificing critical performance attributes. The strategic implication is that resilience is becoming a design parameter, not just a sourcing concern. Formulators that can adjust to input volatility while preserving specification integrity are gaining an advantage that goes beyond short-term margin protection.
Taken together, these drivers indicate a market where winners will be those who integrate compliance, formulation science, and cost-aware supply strategy rather than treating them as separate functions.
Competitive Landscape and Leading Strategies
The competitive field in organic PVC stabilizers includes both global and regional players with distinct strategic orientations. PMC Group Inc., based in the United States, has positioned itself around organotin stabilizers spanning methyltin, butyltin, and octyltin variants, with a focus on high-efficiency heat stabilizers for PVC pipe, fittings, rigid film, and exterior applications. Its profile suggests a strategy built on application-specific performance and reliability for demanding extrusion and film use cases. In China, Henan Shunbang Chemical Industry Co., Ltd. manufactures organic PVC stabilizers, including lead salt and compound organic types, serving PVC pipes, sheets, and food packaging. This points to a broad product footprint that balances cost-competitive offerings with application coverage across pipe and packaging channels. Guangdong Sky Bright Group Co., Ltd., also in China, emphasizes organic PVC stabilizers such as high heat resistance tin stabilizers for hard PVC and food-grade applications, suggesting a more targeted emphasis on performance grades aligned with stricter end-use requirements.
Akcros Chemicals Limited, operating in the United Kingdom as part of Valtris Specialty Chemicals, supplies sustainable and bio-based organic PVC stabilizers as part of lead-free systems. Its positioning reflects a sustainability-led value proposition that resonates with buyers seeking to reduce reliance on traditional feedstocks while meeting evolving regulatory expectations. REAGENS S.p.A. in Italy provides organic and calcium-zinc PVC stabilizers for construction and industrial applications, an indication of strength in systems that balance performance with familiar, widely accepted chemistries. Pau Tai Industrial Corporation in Taiwan manufactures organic PVC stabilizers for PVC pipe and profile extrusion, aligning with the structural demand coming from construction-related shaping and extrusion processes.
Several strategic patterns emerge from this landscape. First, differentiation is increasingly formulated around application fit and regulatory readiness rather than chemistry alone. High-efficiency organotin systems for pipes, fittings, and exterior use compete on processing performance and durability, while bio-based and calcium-zinc systems compete on sustainability alignment and broader acceptance in lead-free environments. Second, regional specialization remains important because downstream demand patterns, regulatory baselines, and cost structures differ meaningfully across markets. Third, suppliers that can offer reliable food-grade or construction-grade certifications, combined with application support, are better positioned to capture premium value than those relying solely on volume pricing.
The market is also likely to see continued integration and selective fragmentation. Concentration at the top suggests scope for consolidation among players seeking scale in formulation capacity, distribution, and technical service, especially in regions where compliance complexity is rising. At the same time, fragmentation is possible around specialized bio-based, high-performance, or region-specific formulations where smaller players can build defensible niches. New entrants that bring innovation in ligand design, feedstock sourcing, or cost-efficient production could further re-sort the landscape, particularly if they address the dual requirements of performance and regulatory acceptability.
Future Trends and Commercial Implications
Looking across the forecast period, three trends are likely to shape how the organic PVC stabilizers market evolves and where commercial opportunities will concentrate.
Worldwide Methyl Tin Stabilizer Market
The first trend is the deepening of lead-free and bio-based substitution as a default expectation rather than a premium option. As regulatory standards tighten and customer specifications mature, organic stabilizer systems built on renewable or bio-derived inputs will become increasingly relevant in packaging, construction, and medical-adjacent applications. The commercial opportunity lies in building formulations that can match or exceed the performance expectations of legacy systems while offering a cleaner compliance profile. The associated risk is that feedstock availability, formulation scalability, and price stability may lag behind the pace of specification change, creating temporary supply gaps or margin pressure for early adopters.
The second trend is a shift toward value-based procurement that rewards extended service life and total cost of ownership. Because organic stabilizer systems typically carry a meaningful price premium, buyers will become more rigorous in evaluating whether that premium is offset by reduced failure rates, longer replacement cycles, or easier compliance management. Here, the opportunity belongs to suppliers that can quantify lifecycle benefits, provide application-specific performance data, and support downstream users in specification decisions. The risk is that in cost-constrained purchasing environments, value arguments may be discounted unless they are supported by strong technical credibility and consistent field results.
The third trend is greater formulation flexibility and supply resilience as a competitive requirement. With calcium-based and zinc-based input costs having risen sharply, companies that can manage volatility through diversified sourcing, modular formulation design, and responsive production planning will be better positioned to protect margins and maintain supply continuity. The commercial upside is the ability to offer customers more stable pricing behavior and fewer disruption-driven specification changes. The uncertainty is that prolonged input volatility could compress profitability across the board and reward only those participants with enough scale or innovation to offset cost pressure without eroding quality.
These trends suggest that the next few years will reward players who can align chemistry, compliance, and commercial execution rather than those who excel in only one dimension. The market is unlikely to reward purely transactional strategies, but it will offer meaningful openings for companies that can translate technical and regulatory change into practical value for downstream buyers.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to treat formulation strategy as a business strategy, not just a technical function. Investments in bio-based ligand development, lead-free systems, and application-specific high-efficiency stabilizers should be paired with supply diversification and cost-aware design so that performance gains are not eroded by input volatility. Companies should also strengthen technical support and documentation capabilities, because in a market where compliance and lifecycle value matter, the ability to prove and explain performance can be as important as the performance itself.
For investors, the opportunity lies in identifying participants that combine regulatory readiness with durable differentiation. The most resilient businesses are likely to be those with clear positioning in high-value applications, credible sustainability or performance narratives, and the operational flexibility to navigate raw material swings. Due diligence should examine not only current product breadth but also formulation roadmap, feedstock strategy, and exposure to regions where compliance change is advancing fastest.
For procurement and buying organizations, the practical move is to evaluate stabilizer suppliers on a broader scorecard that includes compliance trajectory, supply resilience, and total cost of ownership, rather than anchoring decisions on unit price alone. Where organic stabilizer systems can extend service life or reduce compliance risk, the premium should be assessed against downstream consequences of specification failures, audit exposure, and replacement costs. Engaging early with suppliers on formulation direction can also help align future specifications with evolving regulatory and sustainability expectations.
For decision-makers who need a deeper, more granular view of how these dynamics will play out across chemistry types, application segments, and regional demand patterns, the full research report provides detailed breakdowns, scenario context, and customized guidance that can be mapped directly to internal planning and investment decisions. The market is moving quickly enough that relying on aggregate trends alone may leave strategic questions unanswered, especially where regulatory timelines, raw material exposure, and application-specific value claims intersect. A more detailed analysis can help translate these interconnected forces into actionable next steps for your specific operating context.
For detailed analysis of this topic, please visit the official page: Organic PVC Stabilizers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


