



Zinc Borate Market: The Real Drivers Behind 6.98% CAGR and $345M Growth

Strategic Trends and Commercial Opportunities in the Zinc Borate Market: 2025–2032 Outlook
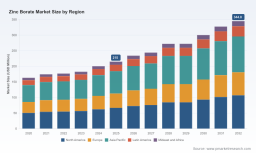
The zinc borate market has entered a phase of steady, structurally supported expansion. Valued at approximately $215 million in 2025, the market is projected to grow at a compound annual growth rate of 6.98 percent through 2032, reaching just under $345 million. This trajectory reflects a broader shift in how industrial formulators balance performance, compliance, and supply chain resilience. Zinc borate has long been recognized as a reliable flame retardant and smoke suppressant, but the market no longer rewards commodity positioning alone. The next growth cycle will be shaped by technological refinement, regulatory recalibration, and geographic realignment. For executives and investors, the question is no longer whether demand will rise, but where value will concentrate and which capabilities will separate winners from marginal players.
Market Status and Core Challenges
The market's expansion over the past five years has been consistent rather than explosive. Annual revenue climbed from $163.15 million in 2020 to $215 million in 2025, with the forward forecast pointing to a clear upward slope through the early 2030s. Growth is broad-based across regions and end-use sectors, but the distribution of value is uneven. North America, Europe, and Asia Pacific account for the largest revenue shares, while Latin America and the Middle East and Africa represent smaller but increasingly strategic volumes. In terms of application, construction remains the dominant demand anchor, driven by building codes, fire safety mandates, and the substitution of higher-cost or more constrained flame retardant chemistries. Textiles and other specialty applications contribute smaller but high-margin segments where product consistency and regulatory documentation matter as much as price.
Three structural challenges define the current inflection point. First, raw material volatility continues to pressure cost predictability. Boric acid, the primary feedstock for zinc borate production, has experienced price swings tied to supply chain disruptions and the geographic concentration of boron resources. When feedstock costs fluctuate, manufacturers face difficult choices between absorbing margin compression, passing costs downstream, or adjusting formulation specifications. Second, regulatory scrutiny is tightening across multiple jurisdictions. Boric acid and its salts have been added to restricted substance lists in cosmetic applications in Canada, and related risk management scopes under environmental legislation now classify certain boron compounds as substances with potential immediate or long-term harmful effects. While zinc borate itself is not uniformly categorized in the same way, the broader regulatory environment around boron chemistry is shifting, and formulators are increasingly cautious about downstream compliance exposure. Third, trade friction is altering landed costs and import flows. Reciprocal tariff actions introduced in 2025 affected zinc borate imports into the United States, raising costs for certain importers and prompting a wider re-evaluation of sourcing strategies. Together, these forces are pushing the market away from price-only competition and toward a model where supply reliability, compliance readiness, and application support carry more weight.
Zinc Sulfate Market
Key Demand Drivers
The market's trajectory is being pulled by a combination of technical, regulatory, demand-side, and supply-side forces that reinforce one another.
Technology and product refinement. Innovation in zinc borate applications centers less on entirely new chemistries than on grade optimization, particle engineering, and formulation compatibility. Higher-purity grades are gaining traction in applications where consistency, low moisture sensitivity, and controlled smoke suppression are critical. Standard grades continue to serve cost-sensitive polymer and rubber formulations, but the margin opportunity increasingly lies in tailored products that integrate more cleanly into complex polymer matrices and meet tighter performance thresholds. This is especially visible in wire and cable, automotive components, and electronics-adjacent applications, where formulators need additives that do not compromise processing or mechanical properties. The practical effect is a market that rewards technical differentiation and application engineering more than bulk volume alone.
PW Consulting
Policy and regulatory environment. Regulation is acting as both a constraint and a catalyst. Stricter fire safety expectations in construction and transportation continue to support demand for halogen-free or low-halogen flame retardant systems, where zinc borate remains a practical option. At the same time, boron-related regulatory updates are making downstream buyers more attentive to documentation, substance tracking, and formulation risk. This does not eliminate zinc borate demand, but it raises the bar for suppliers that can provide clear compliance support, stable quality, and transparent sourcing. In practice, regulatory pressure is helping consolidate demand toward suppliers with stronger technical service capabilities and established regulatory files, while squeezing out less differentiated commodity positioning.
Demand-side behavior. End-user preferences are shifting toward safer, more durable, and more compliant materials. In construction, fire performance requirements and insulation-driven material choices are expanding the use of flame retardant additives in polymer-based building components. In industrial manufacturing, compounders are seeking additives that reduce smoke generation and improve material performance without disrupting processing economics. This demand-side evolution favors products that can demonstrate consistent performance across batches and offer formulation guidance. Buyers are less willing to treat zinc borate as an interchangeable input; they want reassurance that the grade they select will behave predictably in their specific polymer system and regulatory context.
Supply chain and cost structure. The supply side is being reshaped by capacity expansion, geographic sourcing decisions, and feedstock dynamics. New production capacity has come online in regions with access to boron resources and lower-cost manufacturing bases, while established producers in other markets have invested in higher-purity lines to capture premium demand. At the same time, boric acid price volatility and trade policy adjustments have made landed cost a more variable factor. These conditions are encouraging buyers to diversify sourcing, reconsider near-term inventory strategies, and evaluate total cost of ownership rather than unit price alone. For producers, the implication is that scale advantages matter, but they must be paired with reliability, technical support, and regulatory readiness to defend margin.
Competitive Landscape and Leading Strategies
The competitive field is moderately concentrated, with the top three firms accounting for roughly 24.6 percent of market revenue and the top five reaching about 26.2 percent. This level of concentration suggests a market where established players hold meaningful share but fragmentation remains sufficient for regional specialists and application-focused entrants to compete on performance, service, or cost positioning. The strategic differences among leading companies are instructive.
Large established producers have built their positions around brand recognition, broad application coverage, and consistent quality. U.S. Borax, for example, has emphasized specific flame retardant and smoke suppressant grades for polymers, wire and cable, and construction uses. Its strategic advantage lies in a recognized product portfolio and the ability to support regulated applications with established technical credibility. In a market where buyers increasingly value reliability and compliance documentation, this kind of positioning provides a defensive moat, especially in North American and global supply chains that prioritize proven performance over incremental cost savings.
Regional producers with access to boron resources are pursuing a different logic: capacity expansion and targeted high-purity offerings. Akdeniz Chemson began producing hydrated zinc borate flame retardants with a first-phase plant capacity of 3,000 tonnes per year, and its recent capacity expansion reflects a deliberate move to capture rising demand. Eti Maden has taken a similar path, expanding production capacity with a facility dedicated to high-purity zinc borate to address global demand growth and improve supply chain efficiency. Turkey's broader role in boron resource availability gives these producers structural cost and supply advantages, but their commercial success depends on converting resource access into consistent quality, export reach, and application support.
European and Asian specialists are generally leaning into purity, sector-specific requirements, and regulatory alignment. Societa Chimica Larderello focuses on high-purity grades for automotive, electrical, and coatings sectors with REACH compliance. Sakai Chemical Industry positions premium high-purity zinc borate for electronics, automotive, and demanding Asian markets. These strategies target segments where buyers are less price-sensitive and more focused on performance consistency, documentation, and long-term supply assurance. In contrast, several Chinese producers serve domestic polymer processors and export to price-sensitive markets with standard-grade products. This is a commercially rational approach in volume-driven segments, but it also exposes those players to tighter margin dynamics and greater sensitivity to feedstock volatility and trade policy shifts.
Technical service and formulation support are emerging as differentiators across the landscape. Royce Global and Wallace FR illustrate a service-oriented model built around technical advisory, regulatory compliance documentation, and support for polymer compounders operating under regulated conditions. This matters because zinc borate performance is highly application-dependent. Buyers in wire and cable, construction polymers, and specialty coatings often need help optimizing loading levels, understanding interaction with other additives, and navigating documentation requirements. Suppliers that can reduce formulation risk and accelerate time to compliance are increasingly able to command preference even when unit pricing is not the lowest.
The competitive landscape is likely to evolve along three axes. Consolidation will continue where scale, resource access, and regulatory files provide durable advantages. Differentiation will intensify around purity, application support, and compliance readiness, especially in higher-value segments. New and expanding entrants will pursue specific niches, such as high-purity grades, regional cost advantages, or specialized technical service. The broader trend is not toward a single dominant model, but toward a layered market in which value capture depends on aligning product grade, service capability, and geographic reach with the right end-use segments.
Zinc Oxide Market
Future Trends and Commercial Opportunities
Over the next three to five years, three interconnected trends are likely to shape how value is created and captured in this market.
Trend one: premiumization within a growing volume base. As demand expands, a larger share of growth is expected to come from higher-purity and application-tailored grades rather than undifferentiated standard products. Construction and industrial polymer applications will continue to drive volume, but the most durable margin opportunities will belong to suppliers that can provide consistent quality, controlled particle characteristics, and formulation support. The commercial opportunity here is to move up the value chain within zinc borate itself: invest in grade development, quality assurance, and technical service so that the product becomes a defining element of the buyer's formulation rather than a replaceable commodity.
Trend two: compliance and documentation as competitive infrastructure. Regulatory attention around boron-related substances is unlikely to fade. Even where zinc borate remains acceptable for core flame retardant uses, downstream buyers will continue to demand clearer documentation, traceability, and proactive compliance support. This creates an opportunity for suppliers to treat regulatory readiness as part of the product offering rather than an administrative add-on. Companies that can supply robust compliance files, transparent sourcing information, and application-specific guidance will be better positioned to retain customers in regulated polymer, construction, and electrical applications. The risk is that suppliers with weaker documentation or less consistent quality will face growing exclusion from sensitive supply chains.
Trend three: geographic realignment and sourcing diversification. Trade policy, tariff effects, and feedstock concentration are encouraging buyers to diversify supply sources and reconsider inventory and sourcing strategies. At the same time, capacity expansion in resource-adjacent regions is changing the balance of available volume. The opportunity lies in matching supply positioning to buyer risk tolerance. Some customers will prioritize regional supply security and technical support, while others will pursue cost-optimized sourcing where documentation and quality consistency are still acceptable. Producers that can operate across these demand profiles, or that deliberately choose a clear positioning, will be better equipped to manage volume and margin than those stuck in the middle.
These trends point to a market where growth is real but not uniformly distributed. The most attractive opportunities will be in segments where flame retardant performance, smoke suppression, and compliance intersect with demanding applications. The most significant risks involve feedstock price volatility, regulatory uncertainty around boron chemistry, and trade-driven cost fluctuations that can quickly erode margin for poorly positioned players. Executives should therefore treat the market as one where strategic choices about grade mix, service capability, and sourcing geography matter as much as overall demand growth.
Actionable Recommendations for Decision Makers
For manufacturers and formulators, the priority is to align product and sourcing strategies with the way value is shifting in the market. Evaluate zinc borate grades not only by price, but by how reliably they perform in the intended polymer system, how well they support regulatory documentation, and whether the supplier can provide formulation guidance. Where applications are performance-sensitive or regulation-intensive, the total cost of ownership argument often favors more consistent, better-supported grades over the lowest headline price. At the same time, review sourcing exposure to feedstock volatility and trade-related cost changes, and consider whether a diversified supplier base or a more deliberate regional sourcing strategy reduces risk without sacrificing performance.
For investors and corporate development teams, the appeal lies in companies that combine resource access or scale with premium grade development and compliance readiness. Capacity expansion alone is not a sufficient thesis; the more durable opportunities are in producers that can capture higher-value segments, serve regulated applications with credible documentation, and offer technical support that reduces customer risk. Watch for signposts such as continued investment in high-purity lines, expansion in regions with resource advantages, and growing emphasis on application engineering rather than bulk commodity sales. Conversely, exposure to undifferentiated price competition in highly tariff-sensitive or feedstock-volatile channels should be assessed carefully, as margin durability may be limited.
For procurement and supply chain leaders, the strategic task is to balance cost, reliability, and compliance in a market where each can shift independently. Multi-source sourcing may be prudent for high-volume applications, but the goal should be to qualify suppliers that meet consistent quality and documentation expectations rather than simply alternating between the lowest-cost options. Build compliance and traceability requirements into supplier qualification early, especially for applications entering regulated construction, electrical, or automotive supply chains. In practice, the buyers who will gain the most leverage are those who define performance and documentation requirements clearly, then evaluate suppliers against those criteria instead of treating zinc borate as a fungible input.
The timing of these decisions matters. The market is moving toward greater differentiation in grades, stronger expectations around compliance support, and more deliberate sourcing strategies. Companies that wait for the landscape to settle risk paying higher costs later, both in supply disruption and in lost positioning. More detailed segmentation, regional dynamics, and company-level benchmarking can help translate these directional insights into specific operating choices. The full research report provides deeper granularity on market splits, demand patterns, and competitive benchmarks for organizations that need to move from strategic direction to implementation.
For detailed analysis of this topic, please visit the official page: Zinc Borate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


