



Pneumococcal Vaccination Market 2026: Why 5.3% CAGR & Shifting Demand Signal Sustained Growth

Strategic Insights into the Pneumococcal Vaccination Market: Growth Trajectories and Commercial Opportunities
Market Landscape and Core Challenges
A Maturing Industry with Steady Expansion
The global pneumococcal vaccination market has demonstrated consistent growth over the past half-decade, expanding from approximately $7.35 billion in 2020 to nearly $9.38 billion in 2025. This historical trajectory reflects sustained immunization efforts, expanding national schedule integration, and incremental product introductions. Looking ahead, the market is projected to progress from $10.20 billion in 2026 toward $13.26 billion by 2032, representing a compound annual growth rate of 5.3%. While the growth rate is moderate compared to pandemic-era vaccine segments, it underscores a structural shift from emergency response to routine, high-coverage immunization programs with broader age-group inclusion.
Revenue concentration remains high, with the top three manufacturers accounting for roughly 85% of market value and the top five capturing about 92%. This concentration signals strong barriers to entry, primarily driven by complex conjugate chemistry, stringent regulatory pathways, and established procurement relationships with government agencies and multilateral organizations. At the same time, it suggests that differentiation increasingly depends on valency breadth, age-specific indications, and supply reliability rather than on basic vaccine availability.
Key Challenges at the Current Inflection Point
Three structural challenges define the current market environment. First, pricing and reimbursement dynamics remain highly bifurcated. In high-income markets, private-sector procurement prices for conjugate vaccines can range from $100 to $150 per dose, while subsidized doses in lower- and middle-income countries can reach as low as $3.50 through multilateral mechanisms. This gap creates tension between volume expansion and margin sustainability, especially as global health institutions push for broader access without proportionally increasing procurement budgets.
Second, cold chain logistics continue to constrain last-mile delivery and inventory flexibility. All pneumococcal conjugate vaccines require storage between 2 and 8 degrees Celsius, with stability limited to approximately four days at temperatures up to 40 degrees Celsius. This requirement elevates operational costs for remote outreach, increases wastage risk, and places pressure on manufacturers and distributors to improve packaging, monitoring, and contingency planning.
Third, reimbursement and coverage policy shape demand signals across regions. In the United States, Medicare Part B covers pneumococcal vaccines at 95% of average wholesale price, with geographically adjusted rates updated in 2025. While this supports predictable uptake among older adults, it also ties commercial performance to periodic policy updates and formulary decisions. Any lag in coverage alignment, particularly for newer higher-valent products targeting adult populations, can slow adoption even when clinical differentiation is clear.
Key Drivers Shaping Market Direction
Technology Innovation and Valency Evolution
The most visible driver is the ongoing expansion in valency coverage and target-population specificity. The launch of broader conjugate formulations reflects a deliberate effort to address serotype coverage gaps, particularly in adult populations where disease burden is rising and serotypes not covered by earlier formulations remain clinically relevant. A concrete example is the positive CHMP opinion received in March 2025 for Capvaxive, a 21-valent pneumococcal conjugate vaccine designed for adults. This milestone signals regulatory momentum for higher-valency products and indicates that differentiation is increasingly linked to serotype selection, immunogenicity, and age-specific clinical data rather than to conjugate technology alone.
Beyond new formulations, technology leadership also depends on manufacturing capability. Operations that can scale conjugate production efficiently, maintain lot consistency, and manage fill-finish throughput gain a meaningful advantage in a market where supply interruptions can immediately affect national procurement schedules. The establishment of a dedicated North Carolina site and custom fill-finish line for pneumococcal vaccines in 2026 illustrates how capacity building is becoming a strategic priority, not merely an operational detail.
Policy and Regulatory Dynamics
Regulatory pathways and procurement policy are becoming more granular. Multi-valency approvals for adults, pediatric indications, and regional licensing decisions all influence the speed at which new products reach the market. The growing emphasis on adult immunization reflects a broader policy recognition that pneumococcal disease burden spans age groups, and that coverage targets cannot be achieved through pediatric programs alone. In parallel, procurement forums such as the PAHO Revolving Fund continue to structure access in ways that blend affordability with local production goals. The January 2025 agreement for local PCV20 production in Argentina demonstrates how policy and manufacturing strategy can converge to support both supply security and regional capacity building.
At the same time, regulatory expectations on quality, stability, and post-market surveillance remain high. These requirements do not only affect launch timing; they shape long-term commercial viability by raising the minimum bar for manufacturing excellence and lifecycle management. Companies that treat regulatory compliance as a strategic capability, rather than a procedural hurdle, are better positioned to maintain access across diverse buyer environments.
Demand-Side Behavior and Immunization Priorities
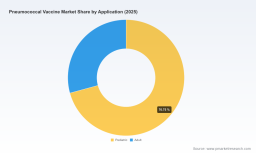
Demand is being reshaped by broader public-health awareness, adult vaccination initiatives, and growing emphasis on equitable access. Pediatric demand remains substantial and is supported by routine immunization schedules, but the adult segment is gaining attention as health systems seek to reduce hospitalizations and complications linked to pneumococcal disease in older populations. This shift matters commercially because adult programs often involve different procurement channels, reimbursement structures, and provider education requirements compared with pediatric campaigns.
Another demand-side dynamic is the increasing preference for supply resilience. Procurement entities are more attentive to manufacturing location, backup capacity, and risk-sharing terms, especially after recent global disruptions across healthcare supply chains. Buyers are not simply evaluating price and valency; they are also assessing whether a supplier can deliver predictably across multiple seasons and geographies. For manufacturers, this means that commercial strategy increasingly includes operational credibility as a differentiator.
Cost Structure and Supply Chain Considerations
Cost structures remain highly sensitive to manufacturing complexity, serotype mix, and procurement segmentation. The large spread between high-income private pricing and subsidized multilateral pricing means that companies must manage product portfolios with different margin profiles and volume expectations. In that environment, efficiency in upstream production and downstream distribution has direct commercial implications. Even modest improvements in yield, fill-finish throughput, or packaging design can significantly affect net performance across high-volume, lower-margin segments without disrupting high-value markets.
Cold chain constraints also interact with cost structure. Temperature-stable packaging innovations, extended monitoring tools, and distribution planning can reduce wastage and broaden reach in harder-to-serve settings. These improvements are not only logistical; they influence the economic feasibility of expanding coverage in regions where the value case depends on reliable delivery rather than on vaccine availability alone.
Competitive Landscape and Leading Strategies
Strategic Positioning of Major Players
The competitive field is anchored by large multinational manufacturers and an emerging group of regional and cost-competitive suppliers. Leading multinationals typically compete through comprehensive pneumococcal portfolios spanning multiple valencies and age groups. For example, one major manufacturer markets a 20-valent conjugate vaccine and a 15-valent conjugate vaccine across infant and adult indications, while another maintains a portfolio that includes a well-established 13-valent conjugate vaccine, a 23-valent polysaccharide vaccine, and a newer 21-valent adult-focused conjugate vaccine. This breadth allows them to address different clinical needs and procurement categories while leveraging established brand recognition, regulatory experience, and global distribution capabilities.
Regional and affordability-oriented suppliers are positioned differently. Some focus on pneumococcal conjugate products intended for pediatric use, often in formulations that align with specific national immunization needs or cost constraints. One notable example is a 10-valent conjugate vaccine distributed for pediatric use and prequalified for broader access, while another manufacturer in India has brought a 14-valent conjugate vaccine into the market with WHO prequalification. These products illustrate how competitive advantage can be built through access-friendly pricing, regulatory prequalification, and fit-for-purpose formulations, especially in markets where procurement decisions weigh cost and supply continuity heavily.
China-based manufacturers also play an important role in domestic and regional supply, particularly with 13-valent conjugate vaccines for pediatric use. Their strategic relevance lies in serving high-volume local demand and potentially expanding into adjacent markets where regulatory alignment and pricing structures support competitor diversification.
Differentiation in a Concentrated Market
In a market where the top three and top five firms hold the large majority of value, differentiation tends to emerge in four areas:
- Valency and indication breadth: Products that address adult and pediatric populations with improved serotype coverage can command stronger positioning if supported by clinical evidence and reimbursement alignment.
- Manufacturing and supply reliability: Capacity investments, fill-finish specialization, and regional production partnerships create credibility with procurement entities that prioritize continuity and risk mitigation.
- Access strategy: Price-tier strategies, multilateral engagement, and local production arrangements can open volume opportunities in price-sensitive markets while preserving higher-margin segments elsewhere.
- Lifecycle and pipeline momentum: Companies advancing next-generation candidates, such as a 25-valent pediatric program, signal long-term intent and can influence formulary and procurement decisions well before launch.
These dimensions matter because the market is no longer defined solely by who has a conjugate vaccine. It is increasingly defined by who can deliver the right valency to the right population, at the right cost structure, with dependable operations and policy-aware market access.
Evolving Market Structure: Integration, Diversification, and New Entry
The market structure is evolving along several lines. Large players continue to reinforce positions through portfolio breadth, global procurement relationships, and pipeline advancement. At the same time, the industry is seeing targeted partnerships and regional manufacturing initiatives that could gradually diversify supply sources. The Argentina-based local production arrangement for PCV20, supported by a multinational partner and a regional procurement fund, shows how access and supply resilience can be pursued through coordinated partnerships rather than through wholly independent vertical integration.
New entry remains difficult, but not impossible. Entrants that can secure regulatory prequalification, demonstrate manufacturing quality, and align with multilateral or government procurement channels may find viable niches, especially where serotype coverage needs or cost thresholds create room for alternative suppliers. Conversely, entrants without clear cost advantages, differentiated valency coverage, or credible supply commitments will face steep headwinds in a market that already rewards scale, experience, and operational reliability.
Future Trends and Commercial Implications
Trend One: Adult-Focused Higher-Valency Adoption Will Accelerate
Over the next three to five years, adult immunization is likely to become a stronger growth driver as higher-valency conjugate options and supportive policy signals gain traction. This trend is commercially significant because adult programs can expand total addressable demand, encourage updated formulary placement, and create new procurement patterns distinct from pediatric routines. Vaccines with adult-specific indications and broader serotype coverage may benefit most, especially if reimbursement frameworks continue to support predictable access.
The business implication is that manufacturers and buyers alike should prepare for more segmented adult demand, with greater emphasis on provider education, scheduling logistics, and coverage alignment. Companies that can demonstrate real-world effectiveness, efficient adult dosing pathways, and reliable supply will be better positioned to capture share in this expanding segment.
Trend Two: Supply Resilience and Regional Production Will Become Strategic Assets
Another likely trend is the continued emphasis on supply security through regional production, dedicated fill-finish capacity, and procurement partnerships. As buyers place more weight on continuity, the ability to demonstrate manufacturing presence, contingency planning, and localized production potential may become a competitive advantage. This is not only about responding to shortages; it is about aligning with procurement preferences that increasingly treat supply reliability as a core requirement.
Commercial opportunities here include partnerships that combine technology, capacity, and procurement access; investment in flexible fill-finish infrastructure; and manufacturing strategies designed to serve multiple price-tier markets without undermining quality or delivery performance. For buyers, this shift creates opportunities to reduce concentration risk and improve long-term affordability through diversified supply arrangements.
Pertussis Vaccine Market
Trend Three: Pricing Pressure and Access Optimization Will Coexist
The third trend is the persistence of pricing divergence across markets. High-income private pricing and subsidized procurement will continue to coexist, which means that portfolio management and market access strategies will remain central to commercial success. Companies will need to navigate the tension between volume growth in lower-price segments and margin preservation in higher-price segments. This is likely to reinforce interest in efficiency improvements, targeted access programs, and differentiated formulations that can justify pricing based on clinical value and service reliability.
A related opportunity lies in optimizing the pathway between product value and reimbursement. In settings where coverage policy shapes adoption speed, alignment with payer expectations, formulary status, and provider workflows can be as important as clinical differentiation. Firms that integrate market access considerations earlier in product planning will be better equipped to convert innovation into commercial traction.
Risk Considerations
Several uncertainties could alter the pace or pattern of growth. Regulatory timing for new higher-valency products may vary by region, affecting how quickly adult and pediatric segments adopt next-generation formulations. Cold chain constraints and last-mile delivery costs may continue to limit coverage expansion in certain environments, especially where infrastructure is limited or seasonal demand spikes strain supply systems. Pricing and reimbursement updates can also change demand dynamics, particularly if policy adjustments reduce reimbursement levels or shift procurement toward more competitive contracting. Finally, the high concentration of market value means that competitive responses by leading players, such as pricing maneuvers, portfolio expansions, or supply agreements, can materially influence the landscape for smaller participants and new entrants.
Worldwide Multivalent Pneumococcal Conjugate Vaccine Market
Actionable Recommendations for Decision Makers
For Manufacturers and Developers
Focus on differentiating through valency relevance, age-specific evidence, and operational credibility. For adult-focused products, ensure that clinical positioning supports reimbursement alignment and provider adoption. For pediatric and mixed-population offerings, emphasize supply reliability and manufacturing maturity as part of the commercial proposition. Consider regional production or partnership models that improve access credentials and supply resilience without sacrificing quality. Build lifecycle plans that anticipate not only new formulations but also procurement expectations, cold chain realities, and price-tier management across markets.
For Investors and Strategic Partners
Evaluate opportunities based on three questions: whether a candidate or asset addresses a clear serotype or population gap, whether the operating model supports dependable supply at scale, and whether the market access pathway is realistic in the target geography. Higher-valency adult programs, dedicated fill-finish capacity, and access-oriented partnerships are areas where strategic value may be particularly sensitive to execution quality. At the same time, assess concentration risk in the supply base and the potential for procurement policy shifts to change volume or pricing assumptions. In this market, value creation often depends less on speculative demand than on execution of differentiation, reliability, and access.
For Procurement Leaders and Health System Decision Makers
Prioritize contracts and procurement strategies that balance cost, coverage, and continuity. Where possible, diversify supply sources for critical pneumococcal programs and require evidence of cold chain capability, contingency planning, and delivery reliability. For adult immunization programs, align procurement decisions with reimbursement and provider workflows to reduce adoption friction. For pediatric programs, emphasize predictable supply and formulation fit with national schedules. As higher-valency options become available, evaluate them not only on price but also on serotype relevance, target-population coverage, and total program reliability.
PW Consulting Health Care Research Center
Timely, detailed intelligence is especially valuable in a market where commercial outcomes depend on the interaction of regulation, procurement policy, manufacturing capacity, and product differentiation. Decision makers who monitor pipeline milestones, regional production developments, reimbursement updates, and procurement trends are better positioned to anticipate shifts rather than react to them. For those seeking deeper segmentation detail, scenario analysis, and tailored recommendations, the full research report offers a more granular view of regional dynamics, product-level positioning, and market-access considerations across buyer environments.
For detailed analysis of this topic, please visit the official page: Pneumococcal Vaccination Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


