



Automotive Ambient Lighting Market: Why 10.5% CAGR Signals a $5.9B Design Shift

Illuminating the Path: Strategic Shifts and Commercial Opportunities in the Automotive Ambient Lighting Market
Market Architecture and Defining Headwinds
The automotive ambient lighting market has transitioned from a discretionary cabin furnishing element to a structured, technology-intensive segment that now demands dedicated strategic attention. Over the historical period, the market has expanded steadily, building on a multi-year trajectory that reflects both volume growth and rising content per vehicle. Looking ahead through the forecast horizon, the sector is projected to sustain a robust compound annual growth rate, indicating that ambient lighting is becoming a baseline consideration rather than a niche upgrade. This growth is underpinned by broader vehicle production increases, higher trim penetration, and the gradual migration of ambient systems from premium showcases to mass-market platforms.
The current landscape, however, is defined less by simple expansion and more by structural inflection points. Suppliers and OEMs are navigating a period in which volume growth no longer guarantees margin expansion. Several forces are compressing traditional economics and forcing a recalibration of how ambient lighting is sourced, specified, and monetized.
The first challenge is the erosion of unit economics through persistent component price deflation. As LED module pricing continues to decline at a steady annual pace, suppliers must absorb cost reductions while delivering increasingly sophisticated features such as multi-zone control, color accuracy, and seamless OEM integration. The margin structure that once rewarded scale alone is being replaced by a performance-driven model in which differentiation and system-level value capture determine profitability.
Automotive LED Lighting Market
The second challenge is the shifting center of gravity in the passive environment. Interior lighting, once treated as a low-risk styling decision, is now subject to evolving safety and visibility expectations. Regulatory expectations for interior illumination standards are reshaping specification requirements and forcing manufacturers to treat cabin lighting as a compliance-adjacent function rather than an optional aesthetic feature. This creates additional validation cycles, testing burdens, and design constraints that affect both cost and time-to-market.
The third challenge lies in supply chain geography and cost volatility. LED components, substrates, driver electronics, and interconnect materials remain heavily concentrated in a small set of manufacturing regions. That concentration offers scale and maturity, but it also exposes program schedules and bill-of-materials costs to geopolitical friction and tariff escalation. For vehicle assembly operations in North America and Europe, these dynamics can materially alter sourcing strategies and require deliberate redundancy planning rather than single-source reliance.
Four Forces Reshaping the Value Chain
The most consequential force shaping the market is the pace of component and system-level innovation. Ambient lighting is no longer about a single color strip hidden behind a trim panel; it is becoming a coordinated cabin interface that balances aesthetics, perception, and electrical architecture. Intelligent LED driver solutions with integrated color calibration, optimized pulse-width modulation control, and automotive-grade qualification are reducing the complexity of multi-zone implementations. At the same time, these advances allow OEMs to design zonal lighting experiences that are more dynamic, consistent, and easier to calibrate across trims and cabin configurations. This shift is significant because it moves differentiation upstream, away from mechanical placement and toward electronic control, software-defined behavior, and integrated validation.
Policy and regulation are emerging as a parallel driver of change. As interior lighting standards become more explicit for new vehicle types in major markets, ambient lighting is increasingly evaluated through the lens of occupant visibility, glare control, and predictable operational behavior. Compliance expectations do not necessarily eliminate customization; instead, they impose structure on it. Manufacturers that design cabin lighting with regulatory foresight can convert standards into a competitive advantage by building systems that satisfy both aesthetic goals and safety-related performance criteria without re-engineering at the end of the program cycle.
Consumer and commercial demand are also evolving in ways that matter for product strategy. In passenger vehicles, ambient lighting is increasingly tied to perceived quality, brand expression, and cabin personalization. The expectation is not simply that a vehicle has lighting, but that it can deliver a coherent sensory environment across different drive modes, times of day, and user profiles. For light and heavy commercial vehicles, the value case is slightly different: better cabin visibility, improved ergonomic perception, and stronger fleet branding can support operator comfort and brand differentiation. As these expectations mature, ambient lighting is becoming more of a functional and experiential layer than a pure styling add-on.
Cost structure and supply chain dynamics complete the set of core drivers. The combination of declining LED pricing and concentrated component sourcing creates a dual challenge: suppliers must keep innovating to defend margins while also managing exposure to trade policy and logistics risk. That means sourcing architectures are becoming more strategic, with greater attention to regional balance, qualification redundancy, and design flexibility. In practical terms, the market is rewarding participants who can decouple value creation from pure component cost competition and instead offer integrated electrical architecture, validated multi-zone control, and predictable program execution.
PW Consulting Automotive & Machinery Research Center
Competitive Positioning and Landscape Evolution
The competitive environment reflects a mix of established Tier-1 suppliers, lighting specialists, and electronics-focused manufacturers, each pursuing a different angle on cabin illumination. Some players compete by offering fully integrated ambient lighting systems with strong OEM integration and multi-zone capability. Others focus on advanced LED technology and smart control electronics that enable personalization, multi-color effects, and tighter electrical integration. A further group emphasizes precision LED modules and emitter-level innovation, delivering components that meet demanding color calibration, reliability, and automotive qualification requirements. There are also suppliers that embed ambient lighting within broader interior systems, electrical architecture, or full-vehicle module offerings, allowing them to capture value through system-level bundling rather than component-only sales.
The differentiation that matters most is shifting from lamp count or color variety toward integration confidence and system performance. Players with strong competency in driver ICs, calibrated color behavior, and EMC-optimized control are gaining leverage because they simplify OEM design work and reduce validation risk. Suppliers that can deliver ambient solutions as part of a broader interior or electrical integration package also enjoy an advantage in programs where packaging, harness strategy, and controller architecture must be solved together. On the other end of the spectrum, manufacturers that compete primarily on volume hardware without a clear integration or electronics advantage face increasing pressure as pricing continues to compress.
The landscape is evolving along several identifiable directions. One is consolidation of capability, where OEMs and Tier-1 suppliers favor partners that can reduce the number of distinct integration points across the cabin. Another is increasing specialization at the component and electronics level, especially around intelligent drivers and calibrated emitters that make multi-zone implementations more practical. At the same time, new entrants and expanding incumbents are exploring adjacent opportunities in optical design, software-controlled lighting behavior, and cabin experience personalization. The result is a market that is not simply becoming more crowded, but more functionally layered, with competition intensifying around integration depth, validation reliability, and the ability to support both premium customization and high-volume repeatability.
Forward Outlook: Three Trends That Will Shape the Next Cycle
The next several years are likely to be defined by a move toward more software-influenced cabin lighting strategies. As intelligent control components and multi-zone architectures mature, ambient lighting will increasingly support adaptive color, mode-based scenes, and more refined calibration across vehicle variants. This trend opens commercial opportunities for suppliers that can offer configurable lighting behavior without adding undue complexity to the electrical architecture. It also creates value for OEMs seeking distinct cabin identities without engineering a separate hardware stack for each trim. The strategic implication is that ambient lighting will become more of a configurable experience platform than a static part number, rewarding players who can balance flexibility with production discipline.
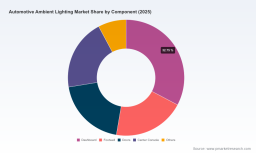
A second trend is the continued integration of ambient lighting into broader interior and electrical system strategies. Cabin illumination is increasingly considered alongside dashboard lighting, console illumination, footwell effects, door ambient features, and center console aesthetics as part of a unified interior experience. That integration encourages suppliers to think in terms of system reliability, connector strategy, thermal behavior, and validation coverage rather than isolated decorative strips. For procurement and program teams, it means ambient lighting decisions should be made with visibility into overall interior architecture, because late-stage changes in one zone can cascade into control logic, packaging, and cost across adjacent areas.
A third trend is the growing importance of supply chain resilience and regional sourcing balance. As tariff exposure and component concentration remain salient concerns, manufacturers will place greater value on partners who can provide supply continuity, transparent cost structures, and flexible qualification footprints. This trend favors suppliers with credible alternatives, disciplined program management, and the ability to maintain performance while adapting to changing trade and logistics conditions. The commercial opportunity lies in making ambient lighting programs less sensitive to single-point disruptions and more capable of meeting predictable cost and timing targets across multiple vehicle programs.
These trends carry inherent risks. Over-customization can increase validation burden and complicate cost control. Regulatory evolution may require recalibration of lighting performance assumptions, particularly where interior standards continue to tighten. And if pricing pressure persists without offsetting value capture through integration, electronics, or service-level differentiation, the market can reward scale while penalizing undifferentiated hardware suppliers. Navigating these risks will require discipline in architecture choices, sourcing strategy, and the pace at which customization is introduced into high-volume programs.
Strategic Actions for Different Decision-Makers
For manufacturers and Tier-1 suppliers, the priority should be to shift competitive positioning from component price to system and integration value. That means investing in control electronics, calibration reliability, multi-zone feasibility, and validated integration paths that reduce OEM development friction. Suppliers that can demonstrate predictable performance across zones, lower validation rework, and clearer electrical architecture integration will be better placed to defend margins even as individual component costs continue to decline. It is equally important to build sourcing resilience, not as a reactive hedge but as a planned element of program design, so that trade and logistics volatility does not become a recurring margin leak.
For investors, the more useful lens is value capture rather than headline volume. The strongest commercial prospects are likely to be found where suppliers combine intelligent control, qualification maturity, and integration relevance with credible cost discipline. Investments in companies that can support software-influenced cabin lighting, reduce fragmentation in OEM programs, and manage supply chain exposure may be better aligned with the next phase of market growth than exposure to undifferentiated LED hardware alone. Evaluating portfolio exposure should also account for how regulation, trade policy, and component concentration could affect regional program economics over the forecast period.
Automotive Lighting Market
For procurement and OEM program teams, the strategic task is to manage ambient lighting as a system decision rather than a late-stage styling add-on. Early alignment on zones, control architecture, color calibration expectations, and interior integration can prevent costly rework and improve the odds of consistent cabin experience across variants. Procurement strategies should also explicitly address sourcing diversity and tariff sensitivity, because the cost and continuity of ambient lighting programs are increasingly tied to the broader electrical and optical supply base. Treating cabin lighting decisions in isolation tends to create downstream risk; treating them as part of the interior and electrical plan tends to create more predictable outcomes.
For decision-makers seeking sharper segmentation detail, competitive benchmarking, pricing sensitivity analysis, and region-specific program implications, more comprehensive market research can provide the additional granularity needed to translate these trends into operational plans. Deep-dive coverage that breaks down component, vehicle-type, and regional dynamics in greater detail supports more precise scenario planning and more confident sourcing or investment decisions. In a market where margin creation depends on integration, qualification, and supply chain resilience, timely access to structured intelligence can make the difference between reacting to change and shaping it.
For detailed analysis of this topic, please visit the official page: Automotive Ambient Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


