



Dextran Market 2026: Why 5.5% CAGR and Asia Pacific Growth Redefine Strategy

Strategic Trends and Commercial Opportunities in the Dextran Market: A 2032 Outlook
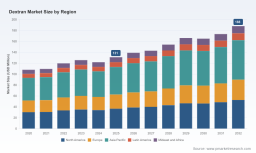
The global dextran market is navigating a period of structural transition, balancing steady growth with evolving clinical preferences and supply chain recalibrations. Valued at approximately $131.0 million in 2025 and projected to reach $188.0 million by 2032, the market is expanding at a compound annual growth rate of around 5.5 percent. This trajectory reflects a sector that is neither explosive nor stagnant; rather, it is maturing under the influence of clinical guideline shifts, manufacturing modernization, and regional demand migration. For executives and investors, the opportunity lies not in chasing headline growth figures but in understanding where value is being created, which formulations are gaining or losing clinical traction, and how leading players are positioning themselves to capture margin and share.
The historical record from 2020 through 2025 reveals a market that has recovered from pandemic-era disruptions, rebounded with renewed procurement cycles, and now faces a more disciplined demand environment. Growth is no longer driven solely by volume expansion in traditional plasma expander applications. Instead, the market is being reshaped by formulation upgrades, derivative diversification, and regional capacity investments that aim to shorten delivery cycles and reduce logistics friction. This evolution creates a clearer divide between commodity-oriented production and clinically differentiated, compliance-backed offerings. The companies that thrive will be those that can align manufacturing reliability with therapeutic relevance, particularly as procurement teams increasingly weigh total cost of ownership against clinical outcomes and supply resilience.
One of the most pressing challenges is the clinical repositioning of certain high-molecular-weight formulations. Dextran 70, while still approved for volume expansion in hypovolemia, is used less frequently in modern practice due to recognized risks such as anaphylaxis, renal impairment, and coagulopathy. This does not eliminate the category, but it does shift demand toward formulations with improved safety profiles and toward derivative products that extend dextran’s utility beyond volume expansion. A second challenge lies in raw material exposure. Sucrose remains the dominant biological feedstock for microbial fermentation production, and its price volatility directly affects cost structures and pricing flexibility. Manufacturers with integrated sourcing, long-term contracts, or alternative feedstock strategies are better positioned to protect margins during input cost swings. A third challenge is regulatory and quality assurance intensity. Pharmaceutical-grade dextran operates under strict pharmacopoeial monographs, and both the FDA and EMA maintain a continuous focus on quality, safety, and traceability for excipient and active pharmaceutical ingredient applications. Compliance is not merely a barrier to entry; it is increasingly a competitive differentiator that influences hospital formulary decisions and procurement trust.
Key Drivers Reshaping Market Direction
The market’s next phase of growth will be shaped by a combination of technological progress, regulatory clarity, demand-side behavior change, and supply chain redesign. Each driver reinforces the others, creating a landscape in which incremental improvements can translate into meaningful share shifts.
Technological Innovation and Formulation Breakthroughs
Innovation in dextran has moved beyond basic polymer production toward targeted formulation and derivative engineering. The introduction of DEAE-Dextran as part of an expanded biopolymers portfolio illustrates how manufacturers are broadening the functional footprint of dextran beyond conventional volume expansion. In parallel, newer Dextran 20 formulations are being designed with enhanced biocompatibility for advanced surgical applications, addressing long-standing concerns around compatibility and patient response. These product-level improvements matter because they create clinically defensible reasons for hospitals and surgical centers to prefer specific offerings over generic alternatives. For commercial teams, the implication is clear: differentiation is increasingly tied to formulation quality, biocompatibility data, and the ability to support specific procedural use cases rather than price alone.
Policy, Regulation, and Reimbursement Dynamics
Regulatory expectations continue to elevate the importance of quality documentation and pharmacopoeial compliance. The sustained focus on monographs for pharmaceutical dextran means that suppliers must demonstrate consistent manufacturing standards, batch-to-batch reliability, and robust safety profiles. At the same time, reimbursement environments are influencing procurement decisions. Public and private payers are scrutinizing average prices and utilization patterns, which places pressure on suppliers to justify value through clinical performance and supply reliability. In this context, products that can demonstrate clear therapeutic benefit, predictable availability, and strong quality credentials are more likely to secure favorable formulary positioning. Reimbursement scrutiny is not a deterrent to growth; it is a filter that rewards disciplined manufacturers and penalizes undifferentiated commodity positioning.
Demand-Side Shifts in Healthcare and Biotechnology
Demand is being reshaped by changing clinical protocols and expanding application breadth. In hospital settings, the balance between traditional plasma expanders and alternative resuscitation strategies continues to evolve, influenced by safety considerations and institutional preferences. This shift encourages manufacturers to invest in formulations that align with modern surgical and emergency care pathways. Beyond direct infusion applications, derivative portfolios are gaining relevance across pharmaceutical and biotech workflows, where dextran-based materials support a wider array of process and formulation needs. The practical consequence is that demand is becoming more application-specific, and suppliers that can map their portfolio to distinct clinical and industrial use cases are better positioned to sustain predictable order flow.
Supply Chain, Logistics, and Cost Structure Realignment
Cold-chain logistics remain a critical enabler for sensitive dextran formulations used in plasma expanders and excipients. As product portfolios become more specialized, the cost and reliability of temperature-controlled distribution increasingly influence both margin and market access. Regional manufacturing expansion is one response, designed to reduce delivery times, lower logistics complexity, and improve service levels for local markets. At the same time, sucrose-driven feedstock costs require continuous attention to procurement strategy, fermentation efficiency, and yield optimization. Companies that combine localized capacity with disciplined input cost management can offer a more stable value proposition, particularly in markets where supply interruptions or prolonged lead times would otherwise disrupt clinical operations.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a moderate concentration level, with a core group of established manufacturers holding meaningful but not prohibitive share. This structure leaves room for differentiation through quality, regional service, and formulation expertise rather than through scale alone.
Profiles of Core Players and Strategic Positioning
Pharmacosmos stands out as an active large-scale manufacturer and global leader in pharmaceutical-grade dextran production. Its portfolio spans Dextran 40, Dextran 70, and derivatives, with supply of APIs, excipients, and clinical-grade dextran supported by FDA and EDQM approvals. This positions the company as a compliance-centric supplier for pharma and healthcare uses, where regulatory credibility and product consistency are central purchasing criteria. Its recent introduction of DEAE-Dextran under GMP certification from the Danish Medicines Agency signals a deliberate expansion into specialized biopolymer applications, reinforcing a strategy that combines regulatory strength with portfolio breadth.
Nagase Viita, formerly Hayashibara, is an active manufacturer of microbial polysaccharides including dextran and derivatives for pharmaceutical and biotech applications. Its long-standing presence in high-quality dextran polymer production reflects deep process knowledge and a focus on consistent polymer characteristics. For customers that prioritize manufacturing reliability and polymer quality across pharmaceutical and biotechnology workflows, this heritage provides a credible basis for long-term sourcing relationships.
What Differentiates the Leaders
The leading players are not competing solely on price; they are competing on trust, compliance, and application fit. Key differentiators include:
Dextrins Market
- Regulatory and quality credentials that simplify procurement validation and support formulary inclusion
- Portfolio breadth that covers both established infusion-grade products and derivatives for broader pharmaceutical use
- Manufacturing reliability and batch consistency that reduce supply risk for hospitals and biotech users
- Regional service capabilities that shorten lead times and improve responsiveness in key demand centers
These advantages matter because buyers in this market are increasingly risk-averse. A supplier that can demonstrate documented quality, predictable availability, and clinically relevant formulation options is more likely to retain share during periods of procurement consolidation or guideline changes.
PW Consulting
Evolution of the Market Structure
The landscape is evolving through a mix of expansion, product specialization, and selective capacity moves. Manufacturing expansion in Southeast Asia aimed at increasing Dextran 20 production capacity reflects a regionalization strategy designed to improve service levels and reduce delivery times. Product launches with enhanced biocompatibility for advanced surgical applications indicate a shift toward higher-value use cases in European hospitals. Regulatory approvals for Dextran 20–based plasma expanders in emergency trauma protocols underscore the continued relevance of dextran in acute care, while also highlighting the importance of timely regulatory clearance and clinical alignment. Taken together, these moves suggest a market that is neither consolidating into a single dominant model nor fragmenting into undifferentiated commodity competition. Instead, it is bifurcating: one pathway emphasizes compliance, clinical differentiation, and regional service, while another remains more price-sensitive and volume-oriented. The most resilient players will be those that can operate effectively across both pathways without diluting their quality positioning.
Future Trends and Commercial Implications
Looking ahead to the 2026–2032 period, three trends are likely to shape commercial outcomes.
Cyclodextrin Market
Trend One: Application Refinement Over Broad Volume Expansion
Growth will increasingly be driven by formulation upgrades and application-specific demand rather than undifferentiated volume gains. Dextran 40 and Dextran 70 will remain important, but their commercial relevance will depend on clinical acceptance, safety perception, and the availability of improved variants. Dextran 20 is likely to see continued interest where enhanced biocompatibility and surgical utility are valued, especially as regional capacity supports faster availability. For commercial teams, this means that portfolio strategy should prioritize applications with clear clinical justification and documented performance benefits, rather than relying on category-wide tailwinds.
Trend Two: Regional Capacity Build-Out and Logistics Optimization
Regional manufacturing and distribution improvements will become a more visible competitive lever. Investments that shorten delivery times, reduce cold-chain complexity, and improve local service can create meaningful advantages in markets where procurement teams value supply certainty. At the same time, feedstock cost management and fermentation efficiency will remain important for protecting margins. Companies that align capacity investments with demand geography and logistics realities are more likely to convert growth into sustainable profitability.
Trend Three: Regulatory and Reimbursement Discipline as a Market Filter
Regulatory expectations and reimbursement scrutiny will continue to reward disciplined manufacturers. Strict pharmacopoeial monographs and ongoing quality and safety focus will raise the bar for market participation, while reimbursement dynamics will encourage buyers to prioritize value and reliability. This environment favors suppliers with strong documentation, consistent quality, and the ability to articulate clinical and operational value. It also introduces risk for those that depend on commoditized positioning without a clear quality or service advantage.
These trends create tangible commercial opportunities. Manufacturers can pursue differentiated formulations and derivative expansions that align with evolving clinical needs. Investors can look for suppliers with credible regulatory standing, regional service strategies, and cost discipline. Procurement and hospital systems can benefit from suppliers that combine compliance, reliability, and application-specific support. The principal uncertainty lies in the pace of clinical guideline evolution and the degree to which safety considerations continue to shift demand away from certain formulations. Any misstep in quality, availability, or regulatory compliance can quickly erode trust in a market where reputation and consistency are central to purchasing decisions.
Actionable Guidance for Decision Makers
Different stakeholders should focus on distinct priorities, but all share a common need: timely, granular insight into where demand is moving, which formulations are gaining traction, and how competitors are adjusting their capacity and portfolio strategies.
For Manufacturers
- Strengthen formulation differentiation by investing in biocompatibility, derivative development, and application-specific support rather than competing primarily on price
- Align capacity and logistics with regional demand centers to reduce lead times and improve service reliability, especially for sensitive formulations that depend on cold-chain distribution
- Protect margin resilience through disciplined sucrose sourcing, fermentation efficiency, and long-term input cost planning, while maintaining rigorous quality documentation to support regulatory trust
For Investors
- Evaluate companies on regulatory credibility, quality systems, and the ability to sustain compliance across pharmaceutical-grade and excipient applications, since these attributes increasingly determine formulary access and procurement stability
- Assess regional expansion and service capabilities as indicators of competitive positioning, particularly where delivery speed and local availability can influence share in surgical and emergency care settings
- Monitor formulation mix and derivative growth as signals of portfolio health, because reliance on a narrow set of legacy products may expose a business to guideline-driven demand shifts
For Procurement and Hospital Systems
- Prioritize suppliers with strong pharmacopoeial compliance, documented quality consistency, and clear clinical support for the specific applications you use most frequently
- Evaluate total cost of ownership rather than unit price alone, including logistics reliability, cold-chain integrity, and the risk of supply interruption for sensitive formulations
- Track formulation updates and regulatory approvals that affect safety and compatibility, since product-level improvements can materially influence clinical outcomes and procurement decisions
Given the pace of formulation innovation, regulatory refinement, and regional capacity change, decision makers benefit from access to detailed segmentation data, competitor tracking, and scenario-based forecasts that go beyond aggregate market size. The broader market trajectory points toward moderate, disciplined growth, but the real value lies in understanding how share, margins, and application mix are shifting at the segment level. For teams that need deeper segmentation data and customized strategic recommendations, PW Consulting’s full Dextran Market research report provides the detailed breakouts and forward-looking analysis required to translate these trends into concrete business decisions.
For detailed analysis of this topic, please visit the official page: Dextran Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


