



Ferulic Acid Market: Why the 7% CAGR & Beauty Boom Redefine Growth

The Ferulic Acid Market: Strategic Trends and Commercial Opportunities in a Growing Antioxidant Economy
Market Landscape and Core Challenges
The ferulic acid market has entered a phase of sustained expansion, driven by the compound's dual role as a potent antioxidant and a functional ingredient across multiple end-use sectors. Over the historical period from 2020 to 2025, the market demonstrated consistent upward momentum, with revenue climbing from approximately 100 million USD at the start of the decade to around 130 million USD by 2025. This trajectory reflects a compound annual growth rate of roughly 7 percent over the base period, a pace that signals healthy demand absorption rather than speculative hype. Forecasts extending through 2032 project the market to surpass the 205 million USD threshold, indicating that the growth runway remains intact even as the base widens.
Such figures, however, only tell part of the story. Behind the headline growth lies a market that is structurally evolving, with shifting cost dynamics, regulatory clarifications, and changing buyer expectations reshaping how value is created and captured. The expansion is not uniform across all value chains; it is concentrated in specific purity grades, sourcing paradigms, and application verticals that command premium pricing or faster volume growth. At the same time, the market exhibits moderate concentration, with the top three players accounting for approximately 45 percent of revenue and the top five reaching around 50 percent. This level of concentration suggests that incumbents possess meaningful scale and distribution advantages, yet it also leaves room for specialized challengers to carve out niches through differentiation in purity, sourcing origin, or regulatory positioning.
Natural Ferulic Acid (CAS 1135-24-6) Market
Several core challenges and inflection points are testing the industry's resilience. First, raw material volatility is exerting persistent pressure on production economics. Rice bran and wheat bran serve as the primary upstream feedstocks for ferulic acid extraction and refining, and the prices of these agricultural inputs fluctuate in response to harvest cycles, weather patterns, and competing demand from food and feed industries. When feedstock costs spike, manufacturers face difficult margin calculations, especially for price-sensitive segments that cannot easily pass through cost increases. Over time, this dynamic favors players with integrated sourcing arrangements, long-term supply contracts, or access to byproduct streams that lower effective input costs.
Second, regulatory clarity is both a catalyst and a constraint. Food-grade ferulic acid must meet quality standards approved by bodies such as the FDA, which increases compliance costs for manufacturers but also raises barriers to entry for less rigorous competitors. At the same time, the FDA's approval of ferulic acid usage in pharmaceutical formulations up to certain levels provides manufacturers with legal protection and stimulates product development in higher-margin therapeutic and nutraceutical contexts. The net effect is a bifurcated market where compliance capability becomes a competitive asset rather than a mere overhead expense. Companies that invest early in documentation, testing protocols, and quality management systems are better positioned to access premium channels, while those treating compliance as an afterthought risk exclusion from regulated supply chains.
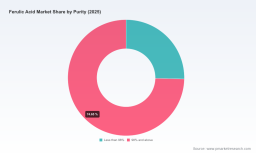
Third, the market is experiencing a sourcing and purity divergence that is reshaping procurement behavior. Natural ferulic acid derived from agricultural byproducts is gaining traction in cosmetics and nutraceuticals, where clean-label positioning and traceable sourcing resonate with end consumers. Synthetic variants continue to serve applications where consistency, cost efficiency, and scalable supply are paramount. On the purity axis, high-purity material at 98 percent and above commands a disproportionate share of revenue compared with lower-purity grades, reflecting the premium that formulators place on performance reliability, color stability, and regulatory acceptability. This split creates strategic tension: producers must decide whether to compete on volume and cost in lower-purity tiers or to invest in purification capability, certification, and technical service to capture value in higher-purity segments.
Key Drivers Shaping the Market
Technological Innovation and Process Breakthroughs
Process innovation is a critical lever for expanding margins and unlocking new application potential. Extraction and purification technologies that improve yield from rice bran and wheat bran feedstocks directly reduce unit costs and improve the economic viability of natural ferulic acid. Advanced purification methods, including refined crystallization and chromatography-based approaches, enable manufacturers to consistently achieve high-purity specifications, which in turn opens doors to pharmaceutical and sensitive cosmetic formulations. These technical advances are not merely incremental; they alter the cost curve of the entire value chain, allowing producers to offer premium grades at prices that remain attractive to buyers who previously faced trade-offs between quality and affordability.
PW Consulting
In parallel, formulation science is expanding the functional scope of ferulic acid. Its antioxidant synergy with other ingredients, such as vitamins and UV filters, enhances product efficacy in personal care and cosmetics, reinforcing its appeal to brand owners seeking substantiated performance claims. As research continues to clarify stability profiles and delivery mechanisms, the compound's value proposition in topical applications strengthens, creating a virtuous cycle where better formulation outcomes drive greater demand, which in turn justifies further investment in supply quality.
Policy and Regulatory Environment
The regulatory landscape is moving from ambiguity toward structured acceptance, with meaningful implications for market participants. The FDA's stance on ferulic acid in pharmaceutical formulations, including approval for use up to specified levels, provides a clearer pathway for developers and reduces the regulatory risk associated with incorporating the ingredient into drug products. This legal certainty encourages research and development teams to explore ferulic acid in new therapeutic contexts, knowing that compliant use is definable and defensible. For manufacturers, this translates into a more predictable demand environment in the pharmaceutical segment, where formulation cycles are long but contract value and margin profiles can be substantial once approved products reach commercialization.
Simultaneously, food-grade regulations are raising the floor for quality. Meeting FDA-recognized quality standards for food applications increases compliance costs, but it also filters out under-resourced entrants and consolidates supply relationships around manufacturers with robust quality systems. The result is a market where regulation functions as a competitive filter: it adds cost, yes, but it also rewards those who treat quality infrastructure as strategic capability. Over the next several years, as regulatory expectations continue to crystallize across regions, the ability to provide traceable, well-documented material will become a prerequisite for access to premium buyers rather than a differentiator reserved for a few.
Demand-Side Shifts in Consumer and Business Behavior
On the demand side, the most visible shift is the accelerating emphasis on clean-label and plant-derived ingredients in personal care and cosmetics. Consumers and brand owners alike are increasingly scrutinizing ingredient origin, sustainability credentials, and transparency. Ferulic acid sourced from rice bran and similar agricultural byproducts aligns well with these preferences, offering a narrative of upcycling and natural efficacy that resonates in marketing and product positioning. This demand-side pressure is not cosmetic; it influences procurement decisions, as formulators seek ingredients that support brand claims without compromising performance.
A parallel shift is occurring in pharmaceuticals and nutraceuticals, where the focus on antioxidant support, skin health, and metabolic wellness continues to expand the functional ingredient pipeline. In this context, ferulic acid's established antioxidant properties and growing body of application research make it a candidate for inclusion in formulations that target specific health and wellness outcomes. The demand here is less about consumer-facing branding and more about evidence-based functionality, which places a premium on purity, consistency, and regulatory compliance. Together, these demand-side trends are pulling the market in two complementary directions: one emphasizing natural origin and storytelling in cosmetics, the other emphasizing specification reliability and compliance in pharmaceutical and nutraceutical channels.
Supply Chain and Cost Structure Evolution
Supply chain dynamics are reshaping where value accrues. Because rice bran and wheat bran are the primary upstream feedstocks, the economics of ferulic acid production are tied to agricultural commodity markets and the logistics of bran collection, storage, and processing. Volatility in these inputs affects production costs, but it also creates opportunities for players who can secure stable, cost-effective feedstock through regional partnerships, integrated processing facilities, or access to milling byproducts that would otherwise be underutilized. In effect, feedstock advantage is becoming a strategic moat, not just a procurement detail.
Cost structures are also evolving as manufacturers invest in higher-purity output and compliance infrastructure. The revenue skew toward 98 percent and above purity grades indicates that buyers are willing to pay for assurance, and that premium pricing can offset some of the cost burden associated with advanced purification and quality systems. For suppliers, the strategic question is whether to absorb these costs to gain access to higher-margin channels or to remain in lower-spec tiers where competition is more price-driven. The answer increasingly favors those who can couple technical capability with customer-facing service, such as formulation support, documentation packages, and reliable batch-to-batch consistency, because these elements turn a commodity ingredient into a value-added partnership.
Competitive Landscape and Leading Strategies
The competitive field in ferulic acid reflects a mix of regional specialization, sourcing heritage, and regulatory positioning. Tsuno Rice Fine Chemicals Co., Ltd., based in Wakayama, Japan, anchors its offering in rice bran-derived natural ferulic acid and related rice bran products used as source material for extraction into antioxidant ingredients for cosmetics and nutraceuticals. This positioning leverages a clear sourcing narrative and a heritage in rice bran processing, which can be compelling for buyers seeking traceable natural origin and a well-defined upstream story. The strategic implication is that Tsuno competes on provenance and specialty sourcing rather than on pure commodity scale, making its value proposition strongest in applications where ingredient origin carries commercial weight.
Vigon International, located in East Stroudsburg, Pennsylvania, USA, focuses on natural ferulic acid supplied for cosmetic formulations at greater than 98 percent purity. This combination of natural sourcing and high-purity specification targets a premium segment where formulators demand both clean-label alignment and performance reliability. The strategic logic is clear: by pairing natural origin with high purity, Vigon addresses a buyer need that sits at the intersection of marketing and functionality, allowing it to command attention in cosmetic supply chains that are increasingly discerning about both claims and specifications.
Spectrum Chemical Manufacturing Corp., based in Gardena, California, USA, offers ferulic acid powder meeting cGMP standards for pharmaceutical and research use. This positioning emphasizes quality systems and regulatory alignment, which are critical in pharmaceutical and research contexts where documentation, consistency, and compliant manufacturing practices are non-negotiable. Spectrum's strategy illustrates how compliance capability can serve as a market access key, enabling participation in higher-value channels where trust in quality is a prerequisite rather than a nice-to-have.
Indofine Chemical Company, situated in Belle Mead, New Jersey, USA, supplies ferulic acid for pharmaceutical, agricultural, and life science industries. This multi-sector orientation suggests a diversification strategy that spreads demand exposure across related verticals, reducing dependence on any single end-market while leveraging common quality and supply capabilities. Such diversification can stabilize revenue streams during cyclical shifts in any one sector, though it also requires the operational flexibility to serve differing specification and documentation requirements across industries.
On the natural ingredient side, Shaanxi LonierHerb Bio-Technology Co., Ltd., based in Xi'an, Shaanxi, China, provides natural ferulic acid as a herbal extract for food additives, cosmetics, and functional ingredients. This offering aligns with the broader trend of plant-derived ingredient demand and positions the company to serve buyers looking for herbal extract framing across multiple application categories. Similarly, Sichuan Benepure Pharmaceutical Co., Ltd., in Chengdu, Sichuan, China, offers ferulic acid as a botanical extract and active pharmaceutical ingredient for pharmaceutical, cosmetic, and nutraceutical applications. Benepure's dual framing as both botanical extract and API reflects an intent to span the gap between nutraceutical and pharmaceutical demand, which can be a powerful positioning if supported by appropriate quality and regulatory infrastructure.
Taken together, these players illustrate several patterns in the competitive landscape. First, sourcing origin and purity specification are central axes of differentiation. Companies that combine natural sourcing with high purity, or that pair compliance certifications with reliable supply, create defensible positions that are not easily replicated by generic producers. Second, there is a geographic spread that includes both established players in Japan and the United States and growing capabilities in China. This dispersion suggests that supply is not monolithically concentrated in one region, and that buyers have options based on their requirements for origin, certification, scale, and technical service. Third, the market is showing signs of both integration and specialization: larger or more diversified players can span multiple sectors and purity grades, while specialists can thrive by owning a narrow but valuable niche, such as cosmetic-grade natural ferulic acid at high purity or cGMP-compliant material for pharmaceutical use.
The evolution of the landscape is likely to continue along these lines. Incumbents with scale, certification, and long-standing customer relationships will seek to protect share by reinforcing quality credentials and expanding application support. New entrants and regional challengers will look for gaps where specific sourcing narratives, purity capabilities, or regulatory alignments can create entry points. Consolidation may occur where scale and compliance become increasingly decisive, particularly in pharmaceutical and food-grade channels, while fragmentation may persist in cosmetics and nutraceuticals where branding, origin, and specialized grades create room for multiple viable suppliers. The strategic winners are likely to be those who can articulate a clear value proposition along one or more of these axes and back it with consistent execution.
Future Trends and Commercial Opportunities
Looking ahead three to five years, several trends are poised to shape the ferulic acid market and create actionable commercial opportunities. The first trend is the deepening of high-purity demand as formulators across cosmetics and pharmaceuticals increasingly prioritize specification reliability. As products become more complex and claims more scrutinized, the tolerance for batch variability diminishes. Suppliers that can reliably deliver 98 percent and above purity, supported by robust documentation and consistent quality, will find expanded opportunities to serve as preferred partners rather than interchangeable sources. For businesses, this means that investments in purification capability, quality systems, and customer-facing technical support can translate into longer-term contracts and improved margin profiles.
Fumaric Acid Market
The second trend is the continued rise of natural and plant-derived positioning in cosmetics and nutraceuticals, amplified by clean-label consumer preferences and brand differentiation strategies. Ferulic acid sourced from rice bran and wheat bran is well placed to benefit from this trajectory, particularly where suppliers can provide traceable origin stories and substantiate sustainability or upcycling narratives. The commercial opportunity here lies not only in selling the molecule but in enabling brand owners to communicate value to end consumers. Suppliers that can package origin, purity, and technical performance into a coherent offering will be better positioned to capture premium demand than those competing solely on price.
The third trend is the gradual formalization of regulatory acceptance across applications, which is likely to reduce uncertainty and encourage product development in pharmaceutical and food contexts. The FDA's approval of ferulic acid usage in pharmaceutical formulations up to certain levels, alongside ongoing quality standard expectations for food-grade material, points toward a more structured environment where compliance capability becomes a market access determinant. For forward-looking businesses, this trend suggests that early investment in regulatory documentation, quality management, and application-specific testing can create a timing advantage as new formulations move from research to commercialization. The opportunity is to be an established, trusted supplier when demand materializes, rather than scrambling to qualify during a product launch window.
These trends are not without risks and uncertainties. Raw material volatility in agricultural feedstocks remains a persistent threat to cost stability, and any prolonged spike in bran prices could compress margins or trigger price resistance in sensitive segments. Regulatory environments can also shift, and while current signals are favorable, changes in quality expectations or jurisdictional requirements could raise compliance burdens unexpectedly. In addition, the growing interest in ferulic acid could attract new entrants, intensifying competition in specific grades or regions and pressuring pricing where differentiation is weak. Companies that rely on a single feedstock source, a single application channel, or a single geographic market may find themselves more exposed to these dynamics than those with diversified supply and demand bases.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to clarify which value axis to own and to invest accordingly. If the strategy is to compete in premium cosmetic or pharmaceutical channels, then high-purity capability, compliance infrastructure, and technical service should be treated as core assets rather than optional enhancements. If the strategy is to serve volume-driven segments, then securing stable, cost-effective feedstock through integrated or long-term supply relationships becomes the critical lever. In either case, it is advisable to avoid undifferentiated commodity positioning, because the market's revenue skew toward higher-purity grades and its increasing regulatory selectivity reward specificity. Manufacturers should also stress-test their cost models against raw material volatility and consider hedging strategies, regional diversification of feedstock sources, or byproduct integration to reduce exposure.
For investors evaluating opportunities in this space, the key is to distinguish between structural growth and cyclical pricing noise. The market's projected expansion through 2032, supported by demand in cosmetics, pharmaceuticals, and food and beverages, indicates a foundational growth trend rather than a transient surge. However, value creation will be uneven, and returns are likely to concentrate among players with clear differentiation in sourcing origin, purity, or compliance capability. Due diligence should therefore focus on the durability of a company's positioning: whether its sourcing advantages are defensible, whether its quality and regulatory infrastructure can support premium channels, and whether its customer relationships are based on specification and service rather than price alone. Monitoring regulatory developments, particularly around food-grade standards and pharmaceutical usage approvals, will also be important, as these factors can accelerate or constrain demand in specific segments.
For procurement and R&D leaders in cosmetics, pharmaceutical, and food and beverage companies, the strategic imperative is to treat ferulic acid sourcing as a partnership decision rather than a transactional purchase. Given the divergence between natural and synthetic offerings, and between lower- and higher-purity grades, procurement teams should align ingredient selection with product positioning, regulatory requirements, and performance needs. This means specifying not only the molecule but also the origin, purity, documentation package, and supply reliability that matter for the end application. Building relationships with suppliers that can provide consistent quality, clear traceability, and formulation support reduces the risk of downstream issues and strengthens the ability to make credible claims in marketing and regulatory contexts. It also pays to qualify multiple suppliers across different sourcing and purity profiles, so that supply strategies can adapt if feedstock costs shift or if application requirements evolve.
Across all these roles, timely access to detailed market intelligence remains a decisive advantage. The ferulic acid market is moving on multiple fronts at once, from feedstock economics and purification technology to regulatory acceptance and clean-label demand. Decisions made without a clear view of how these forces interact risk being reactive rather than proactive. More granular data on segment dynamics, purity-grade revenue splits, sourcing cost structures, and company-level positioning can sharpen strategy and reveal where to commit resources for the highest return. For those seeking a deeper, more customized view of the market, an expanded research report can provide the segmentation detail, competitive benchmarking, and scenario analysis needed to translate these high-level trends into concrete action plans.
For detailed analysis of this topic, please visit the official page: Ferulic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


