



Medical Cyclotron Market: How 6.9% CAGR and Diagnostic Imaging Demand Reshape Growth by 2032

Medical Cyclotron Market: Strategic Trends and Commercial Opportunities
The medical cyclotron sector is entering a period of structural expansion. Historical data shows a steady rise from approximately $189 million in 2020 to $252 million in 2025, with a projected compound annual growth rate of 6.9 percent through 2032, pushing the market toward $398 million. This trajectory is not merely a reflection of steady capital equipment demand; it signals a shift in how radiopharmaceuticals are produced, distributed, and integrated into clinical pathways. For executives and investors, the market is moving from a niche imaging-support segment to a foundational component of precision diagnostics and targeted therapy ecosystems. Understanding why growth is accelerating, where competition is concentrating, and how demand-side behavior is reshaping procurement decisions will determine which organizations capture durable value.
Market Snapshot and Structural Shifts
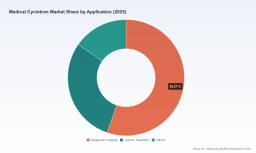
The revenue trend over the 2020-2025 period demonstrates resilience through clinical adoption cycles and supply chain volatility. Demand has broadened beyond traditional PET tracer production, with oncology therapies and specialized diagnostic protocols expanding the addressable base for on-site isotope generation. The forecast period through 2032 suggests continued expansion, but not uniformly across use cases. Growth is being steered by applications that tie imaging to therapeutic decision-making, as well as by production models that favor localized isotope generation over centralized distribution. This structural shift is altering demand patterns, vendor selection criteria, and capital planning timelines.
Three challenges define the current inflection point. First, the industry is navigating a policy environment that is becoming more explicit about production traceability, quality documentation, and reimbursement coding for cyclotron-dependent isotopes. Regulatory attention to process validation and isotope sourcing is raising the bar for operators and suppliers alike. Second, the market remains concentrated, with a small group of manufacturers commanding the majority of share. Concentration creates short-term stability but also intensifies competition around product differentiation, service models, and installation flexibility. Third, demand is being reshaped by clinical adoption of theranostic protocols, which require reliable isotope supply and production capacity aligned to treatment schedules rather than episodic imaging volumes. These pressures are forcing vendors and buyers to rethink operating models rather than simply adding units.
Worldwide Positron Emission Tomography Devices Market
Key Drivers Shaping the Market
Technology innovation remains the clearest catalyst for change. Manufacturers are increasingly focusing on compact designs, higher output efficiency, and dedicated configurations for specific isotope families. Recent product launches illustrate this direction, including instruments engineered for routine production of alpha-emitter isotopes with automated irradiation control and reduced operator exposure. At the same time, high-output platforms continue to evolve for PET and SPECT applications, expanding the range of clinical sites that can support localized production. The strategic implication is straightforward: performance differentiation is moving from raw beam capability to workflow integration, footprint constraints, and compliance-ready operation.
Regulatory and reimbursement dynamics are reinforcing that shift. Authorities have been clarifying pathways for cyclotron-based isotope production in both diagnostic and therapeutic settings, with notable approvals and coding decisions that tie production methods to billing and clinical use. Examples include cleared production processes for Ga-68-based diagnostics, PDUFA action dates for cyclotron-prepared diagnostic kits, and therapy approvals that depend on reliable isotope production for radioligand treatments. These developments are not abstract regulatory milestones; they affect commercialization timelines, reimbursement certainty, and the economics of on-site production versus generator or centralized supply.
Demand-side behavior is changing as well. Hospitals, research centers, and specialized radiopharmacies are seeking more control over supply continuity and production timing, especially where therapeutic workflows depend on synchronized imaging and treatment. On-site cyclotron capability is increasingly viewed as a strategic asset for centers building out precision medicine programs. At the same time, expansion projects are being planned around manufacturing capacity and service responsiveness. New dedicated production facilities, installation milestones at academic and clinical sites, and multi-unit setups at manufacturing locations all point to a market where deployment speed, local support, and operational reliability are becoming as important as instrument performance.
Cost structure and supply chain considerations are also influencing purchasing strategy. Capital expenditure decisions are being evaluated against total cost of ownership, including servicing, consumables, staffing requirements, and regulatory compliance burdens. Suppliers that reduce installation complexity, streamline operational training, and provide clearer service coverage gain an advantage in procurement discussions. For buyers, the question is no longer only whether a cyclotron can produce a required isotope, but whether the broader operating model supports predictable uptime, qualified personnel, and integration with existing radiopharmacy workflows.
Competitive Landscape and Strategic Positioning
The market is led by a set of globally positioned manufacturers with distinct strategic angles. One established leader continues to emphasize breadth across medical cyclotron families and targeted alpha therapy production, including configurations designed for routine isotope output with minimized operator exposure. Another large diversified player anchors its offering around PETtrace platforms, linking on-site isotope production to diagnostic and therapy-related applications through hospital and research installations. A specialist manufacturer focused on high-output systems has been expanding its footprint, including investments in production capacity to support global nuclear medicine demand. A compact superconducting cyclotron developer is positioning around smaller footprints and integrated radiopharmaceutical manufacturing solutions. A Japanese industrial producer continues to compete with compact HM-series systems, emphasizing reliable support and delivery for PET tracer production. These profiles reveal a landscape where scale, specialization, and application focus coexist.
PW Consulting
The strategic differentiation among leaders is becoming clearer along three lines. First, product architecture matters: dedicated high-energy configurations for specific isotope families compete alongside flexible general-purpose platforms, and buyers increasingly evaluate which architecture best fits their isotope roadmap. Second, service and deployment models are a growing battleground, with vendors competing on installation speed, site readiness, commissioning support, and ongoing operational reliability. Third, application breadth is being used as a positioning lever, with some suppliers emphasizing alpha therapy production, others emphasizing PET and SPECT output, and still others connecting cyclotron capability to broader radiopharmaceutical manufacturing services. In practice, this means competitive advantage is less about a single specification and more about how well a vendor aligns instrument design with clinical workflow, compliance, and supply chain expectations.
Market structure is evolving through both consolidation pressure and fragmentation risk. Concentration in the hands of a few incumbents creates a high barrier to entry for general-purpose platforms, but it also opens space for specialized entrants in compact systems, superconducting architectures, or application-specific production lines. At the same time, recent installation activity by both manufacturers and end users reflects a pattern where multi-vendor environments and site-specific procurement choices are becoming more common. Some leading radiopharmaceutical operations are installing instruments from different suppliers to diversify production capability and support parallel diagnostic and therapeutic pipelines. This suggests the competitive battleground is shifting toward ecosystem value: how effectively equipment, isotope workflows, service coverage, and regulatory alignment fit together in a real operating environment.
Worldwide Negative Ion Cyclotron Market
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by three interrelated trends. The first is continued specialization around isotope families that connect diagnostics with therapy, particularly where production reliability directly affects treatment scheduling and clinical throughput. This trend favors vendors and operators that can demonstrate consistent output, documented quality processes, and flexible configurations for specific therapeutic and imaging isotopes. The commercial opportunity lies in aligning equipment selection with isotope roadmaps, not just current production needs.
The second trend is greater emphasis on site-integrated deployment. As more centers invest in precision medicine infrastructure, the value proposition of a cyclotron is increasingly tied to facility planning, staffing, and workflow integration rather than standalone instrument performance. Suppliers that offer simpler siting requirements, clearer commissioning pathways, and stronger local service coverage will have an advantage in competitive procurement processes. For operators, the opportunity is to plan capital investments as part of a broader production and service model, reducing downtime risk and improving utilization.
The third trend is regulatory and reimbursement clarity continuing to influence adoption velocity. As more production processes, diagnostic kits, and therapy pathways become explicitly linked to cyclotron-based isotope supply and billing codes, procurement decisions will be more directly connected to commercialization risk and operational compliance. This creates both opportunity and uncertainty. Where coding and approval pathways stabilize, demand can accelerate around established isotope families. Where regulatory timelines or reimbursement changes remain fluid, adoption may pause while buyers await clearer economics. Organizations that monitor policy milestones and reimbursement updates will be better positioned to time investments and avoid overcommitting to supply models that depend on uncertain coding outcomes.
Actionable Guidance for Decision-Makers
The market is expanding, but value capture will depend on how well organizations align strategy with isotope production realities, regulatory direction, and procurement dynamics. For manufacturers, the priority is to strengthen differentiation beyond instrument specifications by tightening the link between platform design, service coverage, and compliance-ready workflows. Product roadmaps should reflect the growing importance of specific isotope families, installation flexibility, and operational support, especially as centers plan multi-unit or multi-isotope environments. Competitive advantage will increasingly belong to suppliers that can demonstrate not only output capability but also reduced operational friction and reliable site readiness.
For investors, the practical question is where durable demand is forming and which segments are most exposed to rapid adoption or policy-driven uncertainty. Growth is strongest where production reliability supports both diagnostic imaging and therapeutic protocols, and where sites are willing to invest in localized isotope generation. At the same time, reimbursement coding and regulatory approvals can accelerate or delay commercialization timelines for specific isotopes and kits. Due diligence should focus on product fit to likely isotope roadmaps, the strength of service and deployment models, and the sensitivity of demand to policy milestones. Portfolio exposure should account for both the upside from theranostic adoption and the timing risk from evolving approval and billing pathways.
For procurement teams and radiopharmacy operators, the decision calculus is shifting from instrument capability alone to total operating suitability. Evaluating vendors now requires attention to siting constraints, staffing demands, commissioning support, service responsiveness, and alignment with planned isotope mixes. Multi-vendor environments and parallel production lines are becoming more relevant where organizations need flexibility across diagnostics and therapeutics. Procurement planning should also incorporate the impact of regulatory and reimbursement changes on isotope economics, since production method and coding status can materially affect the business case for on-site cyclotron investment.
Strategic decisions in this market carry long lead times and depend on details that are not always visible in high-level market sizing. Segment-level demand patterns, vendor-specific deployment metrics, policy timelines, and reimbursement developments will shape which opportunities convert into durable advantage. For teams that need a sharper view of these factors, the full research report provides deeper segmentation data, regional and application-level context, and customized guidance tied to specific operating model and investment objectives.
For detailed analysis of this topic, please visit the official page: Medical Cyclotron Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


