



Train Seat Market 2026: Why 5.2% CAGR and High-Speed Demand Reshape Growth

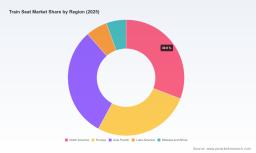
The Train Seat Market: Strategic Shifts and Commercial Opportunities (2025–2032)
The global train seat market has entered a phase of steady expansion, underpinned by renewed investment in rail infrastructure and a structural shift toward higher passenger comfort. Valued at approximately 146.8 million USD in 2025, the market is projected to grow at a compound annual rate of 5.2 percent through 2032, reaching an estimated 207.6 million USD. Historical progression from 2020 through 2025 reflects a consistent upward trajectory, with growth accelerating as operators prioritize fleet modernization and passenger experience. This expansion is not merely a function of rising ridership; it reflects deeper changes in how rail operators configure interiors, how manufacturers respond to regulatory and material constraints, and how seating has evolved from a commodity component to a strategic differentiator.
Despite the favorable growth outlook, the industry faces several structural challenges that will shape competitive outcomes over the next decade. First, stringent safety and fire-resistance regulations for railway interiors continue to lengthen production cycles and increase compliance costs, compressing margins for manufacturers that lack scalable certification processes. Second, material cost volatility remains a persistent pressure point. Prices for aluminum, high-density foam, and composite materials fluctuate in response to broader industrial demand and supply chain disruptions, directly affecting the economics of advanced seating systems. Third, pricing dynamics on the operator side are reshaping procurement behavior. In regions where rail market liberalization has driven ticket prices downward, operators face tighter capital allocation for cabin upgrades, forcing manufacturers to justify seating investments through lifecycle cost reductions, durability, and modularity rather than upfront premium pricing. These intersecting pressures create a market where value engineering, regulatory agility, and total-cost positioning matter as much as raw product performance.
Key Demand and Supply Drivers
The market’s growth is not uniform; it is being pulled forward by a combination of technological, regulatory, and behavioral forces. Understanding these drivers is essential for operators, manufacturers, and investors evaluating where to allocate resources.
Technology and Material Innovation
Seating design is increasingly converging with automotive-era engineering practices. Lightweight construction, ergonomic optimization, and modular architectures are becoming standard expectations rather than niche differentiators. Manufacturers are adapting automotive-derived seating technologies to rail applications, reducing weight while maintaining structural integrity and passenger comfort. Monomaterial frames and recyclable fabric systems are gaining traction, particularly in segments where operators seek to streamline maintenance and align with sustainability targets. These innovations reduce assembly complexity and improve component interchangeability, which in turn lowers long-term service costs. The shift toward flexible, high-tech fabric and recyclable structures also supports faster retrimming cycles and simplifies compliance with evolving fire-safety requirements, though the upfront engineering investment remains substantial.
Regulatory and Policy Environment
Policy frameworks continue to act as both a catalyst and a constraint. On the demand side, expansion of railway infrastructure and urban transit systems globally is generating a steady pipeline of new and replacement seating orders. Public investment in intercity corridors, high-speed networks, and modernized commuter fleets creates volume that supports manufacturing capacity utilization. On the constraint side, interior safety regulations mandate rigorous fire-resistance, durability, and vandalism-resistant performance standards. These requirements increase testing, documentation, and production overhead, particularly for manufacturers serving multiple jurisdictions with divergent approval processes. The regulatory environment also indirectly shapes procurement pacing. Where competition in the rail market has intensified, operators have reduced ticket prices and recalibrated capital spending, which can slow large-scale seat replacement programs unless the value proposition is clearly tied to operational efficiency or passenger retention.
Demand-Side Behavior and Operator Priorities
Passenger expectations are shifting the internal economics of rail seating. Modern travelers increasingly equate cabin comfort, cleanliness, and ergonomic support with overall service quality, especially on intercity and high-speed routes where competition from air and road transport remains intense. Operators are responding by prioritizing seating that supports higher occupancy flexibility, improved accessibility, and easier maintenance. The introduction of double-deck and next-generation high-speed trains illustrates this shift: interior layouts are being redesigned to maximize capacity without sacrificing comfort, and seating packages are selected with step-free boarding, weight distribution, and cabin modularity in mind. For manufacturers, this means that the sale is no longer just about the seat itself; it is about how the seating system integrates into broader fleet performance objectives, including turnaround time, cleaning cycles, and passenger satisfaction metrics.
PW Consulting Health Care Research Center
Cost Structure and Supply Chain Realities
The economics of train seat production are increasingly tied to material sourcing and manufacturing footprint decisions. Volatility in the cost of aluminum, foam, and composites directly impacts margins, particularly for suppliers that rely on fixed-price contracts or operate with thin manufacturing buffers. In response, several manufacturers have expanded or relocated production capacity to improve cost competitiveness and reduce lead times. New facility investments in regions with favorable labor and input economics are enabling suppliers to scale modular platforms more efficiently while maintaining regional compliance capabilities. At the same time, high manufacturing and material costs associated with advanced seating systems continue to act as a restraint on rapid adoption, especially for operators with constrained capital budgets. This tension is pushing the market toward platform-based seating solutions that balance performance, weight, and lifecycle cost, rather than bespoke designs for every order.
Toilet Seat Market
Competitive Landscape and Leader Strategies
The competitive structure of the train seat market is moderately concentrated, with leading players collectively holding a significant share of regional and segment demand. This concentration reflects the technical barriers to entry, the importance of regulatory certification, and the long qualification cycles that rail operators typically impose on interior suppliers. Within this structure, companies are differentiating themselves through product architecture, regional alignment, and the ability to pair seating with broader engineering and manufacturing services.
German and European suppliers remain prominent across multiple rail segments, offering full-line passenger and driver seating for city, regional, intercity, and high-speed applications. Their advantage lies in broad portfolio coverage and established relationships with operators running mixed fleets. Several of these manufacturers have emphasized modular, ergonomic, and vandalism-resistant designs tailored to local, regional, and intercity use cases, where durability and ease of maintenance are central procurement criteria. Others have focused on comfort-optimized seating for intercity, regional, and metro applications, with high degrees of individualization and durability that appeal to operators seeking brand consistency across routes.
In North America, suppliers are concentrated on commuter rail, light rail, subway, and regional passenger vehicles, where robustness, turnaround efficiency, and compliance with regional safety standards are paramount. These providers have built strong positions by aligning product designs with the operational realities of high-frequency urban services. Meanwhile, manufacturers leveraging automotive-derived technologies are gaining relevance in segments that demand lightweight construction, ergonomic refinement, and durable materials. Their cross-industry expertise allows them to accelerate material and cushioning innovation while maintaining the structural requirements specific to rail use. Specialist firms in France and Spain have carved out a distinct role in high-speed train seating, emphasizing ergonomic and modular solutions that suit premium intercity travel and operator customization needs. In parallel, engineering-focused providers offer design, engineering, and manufacturing services for rail seating systems, including lightweight and modular options, positioning themselves as partners in cabin integration rather than solely as component suppliers.
Recent developments illustrate how these players are translating strategy into market action. One European manufacturer launched a new regional seating platform featuring flexible high-tech fabric and a recyclable monomaterial frame, signaling a push toward sustainability-aligned modular design and simplified material handling. That same company inaugurated a new production plant to expand rail seating capacity, reflecting a deliberate move to strengthen manufacturing throughput and regional responsiveness. On the operator side, major rail systems have introduced new fleets with updated seating configurations: double-deck trains with modern seating packages, next-generation high-speed trains with refreshed passenger seating, and high-speed models featuring step-free boarding and enhanced interior seating. These introductions are not isolated product updates; they represent broader fleet strategies where seating is integral to accessibility, capacity optimization, and passenger experience.
The market structure is evolving along a dual path. On one hand, consolidation pressure exists where scale, certification capability, and multi-segment coverage create advantages for larger full-line suppliers. On the other hand, segmentation remains pronounced, with specialized players competing in high-speed, commuter, and metro niches by offering tailored ergonomic, modular, and durability-focused solutions. New entry is difficult but not impossible, particularly for firms that bring differentiated material technology, lightweight engineering, or integrated cabin-design capabilities that reduce operator integration risk. The overall trend points toward a landscape where breadth of coverage and platform commonality are increasingly valuable, but segment-specific expertise still commands premium positioning in demanding applications.
Worldwide Non-recliner Train Seat Market
Future Outlook: Trends Shaping 2026–2032
Looking ahead, several trends are likely to define the market’s trajectory and determine where commercial value concentrates.
Platform-Based Seating and Modular Standardization
The industry is moving toward platform-based seating architectures that allow operators to standardize components across train families while retaining flexibility for route-specific configurations. Modular frames, interchangeable cushioning, and adaptable fabric systems reduce inventory complexity and shorten refit cycles. This trend benefits manufacturers that can offer a coherent platform with proven compliance, predictable maintenance, and lower total cost of ownership. For operators, the opportunity lies in reducing lifecycle costs and improving cabin turnaround without sacrificing passenger comfort. The risk is that over-standardization may limit differentiation in premium segments, making it harder to distinguish services on high-margin routes.
Sustainability-Linked Design and Material Circularity
Sustainability is becoming a procurement consideration rather than a secondary attribute. Recyclable monomaterial frames, durable fabric systems, and designs that facilitate disassembly are increasingly relevant as operators align fleet upgrades with broader environmental goals and regulatory expectations. Manufacturers that can demonstrate lower end-of-life disposal impact, reduced material waste, and easier retrimming will have stronger positioning in bids where total lifecycle cost and compliance are evaluated together. The uncertainty here is material availability and cost consistency; recycled and monomaterial solutions must prove they can meet fire-resistance, durability, and vandalism-resistance standards at scale before they become default choices across all segments.
Fleet Modernization as a Persistent Demand Engine
Infrastructure expansion and urban transit upgrades will continue to drive demand for both new and replacement seating, but the pace will vary by region and operator budget. High-speed and intercity modernization programs are likely to sustain premium seating demand, while commuter and metro operators will focus on durable, high-throughput designs that withstand heavy usage. The key opportunity is to align product roadmaps with fleet renewal cycles, anticipating where replacement programs intersect with accessibility upgrades and interior redesigns. The principal risk is budget compression: if operator capital remains limited, large-scale upgrades may be deferred, shifting demand toward incremental replacement rather than full cabin overhauls.
Strategic Implications for Decision Makers
For manufacturers, the priority is to balance platform scale with segment specificity. Expanding modular seating platforms can improve production efficiency and strengthen compliance repeatability, but winning in high-speed, commuter, or metro niches still requires targeted ergonomic, durability, and customization capabilities. Manufacturers should accelerate certification agility across jurisdictions, stabilize material sourcing through long-term agreements or diversified supply channels, and position seating as part of a broader cabin-integration value proposition that reduces operator downtime and maintenance complexity.
For investors, the market offers exposure to recurring demand tied to infrastructure expansion and fleet modernization, but returns will depend on identifying suppliers with durable differentiators. The most attractive profiles combine certification capability, modular platform economics, and proven relationships across multiple rail segments. Investors should monitor capacity expansion decisions, material cost management, and the ability to convert sustainability trends into commercially viable product lines rather than treating them as isolated marketing claims.
For procurement teams and rail operators, the strategic task is to evaluate seating decisions through total-cost and operational-impact lenses rather than upfront price alone. Seating that reduces cleaning time, supports faster turnaround, improves accessibility, and maintains performance under heavy usage can deliver meaningful operating savings over a fleet lifecycle. Procurement should require evidence of fire-resistance compliance, durability under vandalism-prone conditions, and modularity that enables component-level replacement instead of full-unit swaps. Where operators are balancing ticket-price pressures with service-quality expectations, seating investments should be tied to measurable passenger experience and maintenance outcomes.
Detailed segmentation data, regional nuance, and company-level trajectory analysis can materially improve planning accuracy and risk assessment. For organizations seeking deeper granularity on demand splits, competitive positioning, and scenario-based forecasts across the forecast period, the full market research report provides expanded breakdowns and customized guidance tailored to specific operating contexts and investment horizons.
For detailed analysis of this topic, please visit the official page: Train Seat Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


