



Phosphate Ester Market 2026: Beyond the 5.4% CAGR Story, Mapping the 3.3B Shift to Flame Retardants and Asia Pacific

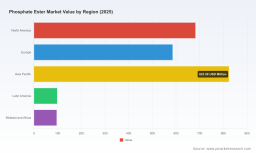
The Phosphate Ester Market: Strategic Shifts and Commercial Opportunities Beyond the Baseline
Market Context and the Pressures Reshaping the Industry
The global phosphate ester market has entered a phase of steady expansion, with total revenue reaching approximately USD 2.29 billion in 2025 and projected to climb toward USD 3.30 billion by 2032. Over the 2020-2025 historical window, the segment demonstrated a resilient upward trajectory, reflecting the incremental replacement of legacy additives and the persistent demand for high-performance fluids, flame-retardant formulations, and surfactant systems across industrial and consumer applications. The forward-looking forecast horizon points to a compound annual growth rate of around 5.4 percent, which suggests that the market will outpace many broad chemical categories but will do so under a fundamentally different operating environment than the one that characterized the early 2020s. Growth is no longer a straightforward function of volume expansion; it is increasingly tied to formulation differentiation, regulatory navigation, and the ability to secure stable, cost-competitive feedstock access.
The current industry landscape is defined less by explosive demand pull and more by structural tension between performance requirements, compliance costs, and margin compression. Three intersecting pressures are reshaping how producers, formulators, and end-users approach the market.
First, feedstock volatility continues to inject uncertainty into cost structures and pricing strategies. Phosphate esters rely on a combination of phosphoric acid derivatives and organic alcohols that are subject to regional supply disruptions, energy cost swings, and shifting trade flows. Price movements in key precursors have remained pronounced over recent years, forcing manufacturers to balance inventory positioning, contract structures, and formulation flexibility. Companies that treat feedstock exposure as a static procurement issue are finding that they lose competitiveness to firms that integrate cost risk into product design and go-to-market strategy.
Second, regulatory scrutiny is becoming more granular and more consequential. Phosphate ester applications sit at the intersection of environmental, health, and safety considerations, while specific grades are tied to dual-use export controls in advanced economies. At the same time, trade remedies and countervailing determinations have begun to affect pricing dynamics in certain alkyl phosphate ester flows. These developments are not merely administrative; they alter the economics of sourcing, the risk profile of specific customer segments, and the relative attractiveness of regional production footprints. In practice, this means that compliance capability is evolving from a cost center into a differentiator that can protect market access and shape customer trust.
Third, the demand environment is fragmenting. The most visible growth vectors are shifting toward specialized applications where performance thresholds are high and substitution is difficult, while commoditized end-uses face margin pressure and reformulation pressure from alternative chemistries. This divergence rewards producers who can supply application-specific solutions rather than generic intermediates, but it also raises the bar for technical service, validation cycles, and customer-level customization. The net effect is a market that continues to grow, but increasingly through value-added segments rather than broad-based volume expansion.
The Forces Driving the Next Phase of Growth
Despite the pressures, the market is being pushed forward by several reinforcing dynamics that are likely to define competitive outcomes over the next several years. These drivers are not independent; they interact in ways that create both margin opportunities and execution risks.
Technology and formulation differentiation
Technical innovation is moving from incremental improvement to application-specific engineering. Leading suppliers are not simply expanding capacity; they are tailoring phosphate ester architectures to meet the requirements of electric vehicle thermal management, advanced lubricants, fire-resistant industrial fluids, and lower-impact consumer formulations. The recent direction of partnership activity underscores this shift. For example, Eastman Chemical Company announced a collaboration with a leading automotive manufacturer in 2025 to develop phosphate esters designed for electric vehicle applications, signaling that the next wave of differentiation is coming from co-engineering with end-users rather than standalone product launches. Similarly, BASF SE’s introduction of a bio-based phosphate ester line reflects a broader industry push to align performance attributes with lower-carbon sourcing narratives, which is increasingly relevant for customers facing their own emissions and procurement targets.
For manufacturers, the implication is that formulation IP, application testing, and close customer integration are becoming central to value capture. For investors, the companies that can demonstrate a repeatable model for translating technical service into premium positioning are likely to earn disproportionate share in high-margin niches.
Policy, trade, and compliance as competitive levers
Regulatory and trade conditions are reshaping where and how phosphate esters are produced and sold. Recent trade-related determinations involving alkyl phosphate ester producers and exporters from China have highlighted how policy can alter cost competitiveness in specific segments and redirect sourcing strategies. At the same time, dual-use export controls on certain grades tied to nuclear applications continue to add complexity for cross-border trade and for customers who depend on globally integrated supply chains. The practical result is a more fragmented sourcing environment in which regional availability, documentation rigor, and qualification speed matter as much as unit cost.
Phosphonate Market
This environment favors firms that can provide predictable supply within defined compliance boundaries and that can support customers through qualification and documentation requirements. It also creates an opportunity for regional producers and integrated downstream formulators who can reduce exposure to cross-border friction while maintaining technical performance.
Demand-side shifts in industrial and consumer applications
Demand is being reshaped by changes in end-use priorities rather than by a single macro driver. Flame retardants continue to represent a substantial share of phosphate ester consumption, but the surrounding pressure toward sustainability and reformulation is encouraging formulators to seek grades that combine performance with improved environmental profiles. Lubricants and hydraulic fluids remain important, yet the growth emphasis is moving toward specialized fluids where fire resistance, thermal stability, and compatibility with advanced machinery and electric vehicle systems justify higher specification thresholds. Plasticizers and surfactants are evolving as well, with some applications shifting toward alternatives that meet stricter regulatory expectations while retaining functional performance.
PW Consulting
In parallel, customer procurement behavior is changing. Large industrial buyers increasingly evaluate suppliers on a broader set of criteria that includes reliability, documentation, sustainability attributes, and regional supply security. This shifts the value proposition from price per unit to total cost of ownership and risk mitigation, rewarding suppliers that can demonstrate consistent quality and proactive technical support.
Supply chain reconfiguration and regional dynamics
Supply chain strategy is becoming a strategic asset rather than a back-office function. Recent corporate activity points to a deliberate effort to strengthen regional production capabilities, particularly in Asia-Pacific, where demand is significant and competitive intensity is rising. The acquisition completed by Huntsman Corporation in mid-2025, which expanded production capabilities in the region, reflects a broader industry tendency to secure closer proximity to demand, reduce logistical exposure, and improve responsiveness to local customers.
At the same time, raw material pricing remains a salient factor. Recorded prices for tributyl phosphate in Asia reached approximately USD 2,600 per metric ton in December 2025, while precursor movements such as n-butanol have exhibited wide swings over the 2022-2025 period. These conditions reinforce the importance of integrated feedstock planning, hedging where appropriate, and flexible manufacturing footprints that can adapt to regional cost advantages. Companies that can coordinate feedstock procurement, production location, and application mix are better positioned to absorb volatility without sacrificing competitiveness.
Worldwide Phosphating Agent Market
Competitive Landscape and How Leaders Are Positioning
The phosphate ester market is moderately concentrated, with the top three firms accounting for roughly 35.8 percent of revenue and the top five reaching approximately 52.4 percent. This structure suggests that scale and portfolio breadth matter, but it also leaves substantial space for specialized players to compete on application fit, technical capability, and regional presence. The competitive dynamics are increasingly less about who produces the most volume and more about who can reliably deliver the right grade, with the right documentation, to the right customer at the right total cost.
Several patterns emerge when looking at how leading companies are differentiating themselves.
Clariant has emphasized specialty phosphoric acid esters through its Hordaphos™ offering, with production tied to its Knapsack site and focused on cleaning products, antistatic and anti-foaming functions in detergents, and multifunctional additives in inks, paints, and coatings. This positioning reflects a strategy rooted in formulation utility and downstream integration rather than commodity volume.
Stepan Company has concentrated on customized phosphate esters built on tridecyl alcohol ethoxylate and tristylylphenol ethoxylate chemistry, targeting agricultural compatibility aids, metalworking lubricants, gear oils, hydraulic fluids, and plasticizers. The emphasis on customization and application breadth allows the company to serve segments where formulation fit is a key purchase criterion.
Eastman Chemical Company has built recognition around fire-resistant phosphate ester hydraulic fluids, notably through its Skydrol™ line for aviation and industrial use. This heritage in high-performance, safety-critical fluids gives the company a strong platform in applications where qualification and reliability are paramount. The recent automotive partnership for electric vehicle applications extends this logic into new high-value demand pools.
LANXESS has developed a presence through Reofos® phosphate ester products aimed at fire-resistant hydraulic fluids and broader industrial applications. The product framing highlights performance in demanding operating environments, which aligns with customers seeking alternatives to conventional fluids in challenging conditions.
Solvay has positioned phosphate ester solutions across flame retardants, lubricants, and specialty chemical applications, suggesting a multi-segment approach that can benefit from cross-portfolio technical leverage. Dow has similarly maintained a foothold in phosphate ester additives and intermediates for lubricants, flame retardants, and industrial fluids, reflecting an integrated chemical supplier model that can connect feedstock capability with downstream application support.
AkzoNobel and Croda International represent a more sustainability- and specialty-oriented orientation. AkzoNobel’s emphasis on eco-friendly phosphate esters for industrial and consumer applications, and Croda’s focus on phosphate ester surfactants and additives for personal care, industrial, and specialty uses, both illustrate how formulation narratives and end-use fit can support premium positioning in segments where customer expectations are shifting.
ExxonMobil and Ashland contribute additional scale and application breadth, with ExxonMobil active in flame retardants, lubricants, and high-performance fluids, and Ashland focused on phosphate ester-based solutions for industrial additives and performance chemicals. Evonik Industries rounds out the landscape with specialty phosphate esters oriented toward flame retardancy, coatings, and sustainable applications, reinforcing the trend toward higher-value, application-specific positioning.
Taken together, these profiles show a market in which competitive advantage is increasingly constructed through a combination of technical service, application credibility, regional supply capability, and alignment with evolving sustainability expectations. The most differentiated players are those that can connect product chemistry to specific operating outcomes for customers, rather than positioning phosphate esters as interchangeable inputs.
The landscape is also evolving through consolidation and targeted expansion. The mid-2025 acquisition in Asia-Pacific illustrates how incumbents are seeking to strengthen regional capability where demand growth and competitive pressure are most acute. At the same time, regional differentiation and trade complexity may encourage further fragmentation in some niches, particularly where qualification requirements and local compliance expectations create natural barriers to rapid redistribution of share. New entrants are likely to find the most traction not by competing head-on in established volume segments, but by addressing unmet formulation needs, sustainability-linked specifications, or regional supply gaps.
Forward Outlook: Trends and Commercial Opportunities
Looking toward the 2026-2032 window, several trends are likely to shape both the direction of the market and the opportunities available to well-positioned players.
Trend 1: Application-led premiumization will outpace generic volume growth
The most durable growth is expected to come from applications where phosphate esters solve specific performance problems, particularly in fire-resistant fluids, high-performance lubricants, and specialized formulation functions. As end-use industries adopt more demanding operating conditions and as electric vehicle and advanced industrial ecosystems expand, the value pool will shift toward grades that are validated for specific requirements and supported by strong technical service. This creates opportunities for suppliers that can shorten qualification cycles, provide clear performance documentation, and maintain consistency across batches. It also raises the stakes for producers that depend on undifferentiated volume without a clear application link.
Trend 2: Sustainability and trade compliance will become inseparable from sourcing decisions
Customers are increasingly evaluating phosphate esters through a dual lens of environmental impact and supply reliability. Bio-based and lower-carbon formulations, such as the bio-based line introduced by BASF SE, are likely to gain relevance in segments where procurement teams must balance performance with emissions goals and customer-facing sustainability commitments. In parallel, trade measures, countervailing determinations, and dual-use export controls will continue to complicate cross-border sourcing for certain grades. The commercial opportunity here lies in building credible, documented supply pathways that reduce customer risk. Suppliers that can combine technical performance with transparent compliance and sustainability credentials will be better placed to secure long-term supply agreements and higher-margin relationships.
Trend 3: Regional supply control and feedstock integration will determine cost resilience
Because price volatility in key precursors remains a defining feature of the market, companies that can manage feedstock exposure through integration, flexible procurement, and regionally aligned production will have a structural advantage. The combination of regional demand growth, trade friction, and raw material swings makes it increasingly important to view manufacturing location, inventory policy, and customer concentration as interconnected strategic choices. Producers with the ability to shift mix, serve regional demand efficiently, and protect margins through intelligent cost management will be more resilient in fluctuating conditions and more attractive to risk-conscious buyers.
These trends carry risks as well. Formulation substitution pressure could intensify if alternative chemistries improve on cost or regulatory ease in specific applications. Trade policy could shift again, altering competitive dynamics in alkyl phosphate ester flows and other sensitive segments. Feedstock volatility may persist, making margin planning more difficult for firms that lack flexibility. Finally, if demand in certain specialized segments develops more slowly than anticipated, premium positioning may prove harder to sustain without clear differentiation.
What This Means for Decision-Makers
For manufacturers, the priority is to move beyond treating phosphate esters as a volume commodity and toward building capability in application-specific value creation. That means sharpening formulation expertise, strengthening technical service around customer use cases, and aligning product portfolios with segments where performance and compliance justify differentiated pricing. It also means treating feedstock and trade exposure as part of the product strategy, not just procurement. Companies that can show consistent performance, reliable documentation, and credible sustainability alignment will be better positioned to defend margins and deepen customer relationships.
For investors, the signal is to look for firms that demonstrate a repeatable connection between technical differentiation and commercial outcomes. Scale alone is less informative than the ability to capture premium segments, manage feedstock and trade risk, and expand in regions where demand growth and local capability reinforce each other. Attention should also be paid to partnership activity and product launches that indicate traction in emerging applications, as these often precede broader share movement in specialized niches.
For procurement and sourcing leaders, the practical imperative is to diversify risk intelligently while maintaining qualification discipline. That includes evaluating suppliers on total cost of ownership and supply security rather than headline price alone, ensuring documentation readiness for regulated or dual-use-relevant grades, and considering regional supply options where they reduce exposure to trade friction or feedstock volatility. In environments where certain alkyl phosphate ester flows are affected by trade determinations or export controls, traceability and supplier qualification become especially important.
Given the pace of change across formulation, regulation, trade, and demand, decision-makers benefit from access to detailed, segment-level intelligence that can translate broad trends into specific sourcing, investment, and product decisions. The interaction between regional dynamics, precursor pricing, application mix, and competitive moves creates a landscape where timely, granular information can materially improve the quality of strategic choices. Organizations that stay close to the shifting detail in this market will be better equipped to identify where to compete, how to structure supply, and which segments offer the most resilient opportunities.
For detailed analysis of this topic, please visit the official page: Phosphate Ester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


