



Ceramic Ink Market: How 5.79% CAGR and Asia Pacific Demand Reshape Growth

Navigating the Ceramic Ink Market: Strategic Trends and Commercial Opportunities Through 2032
The global ceramic ink market has entered a phase of steady, technology-driven expansion. Valued at approximately 2.71 billion USD in 2020, the segment climbed to 3.59 billion USD by 2025, and forward projections indicate a trajectory toward 5.32 billion USD by 2032. This growth reflects a compound annual rate of 5.79 percent across the forecast horizon. While the absolute numbers signal a mature, resilient market, the underlying composition tells a more nuanced story. Regional demand is increasingly concentrated in high-volume manufacturing corridors, functional formulations are outpacing decorative variants in both volume and margin potential, and ceramic tile applications continue to dominate downstream consumption. For decision-makers, the headline growth rate matters less than the structural shifts that will determine which players capture disproportionate value in the next cycle.
Worldwide Specialty Ink Market
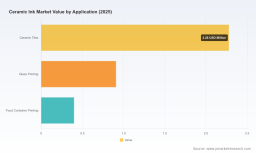
The market is not expanding uniformly. Growth is being pulled forward by regions with heavy ceramic production footprints, while mature markets are shifting from volume-driven expansion toward premiumization and regulatory compliance. Functional inks, which enable advanced surface properties beyond aesthetics, now represent the larger revenue share and are expected to retain their lead as technical specifications tighten across construction, packaging, and consumer goods verticals. Decorative inks remain critical for design differentiation, but their growth trajectory is increasingly tied to digital printing adoption rather than traditional manual or mechanical decoration methods. On the application side, ceramic tiles account for the largest consumption base, followed by glass printing and food container printing. Each vertical carries distinct performance requirements, regulatory exposures, and cost sensitivities, which means aggregated market figures can obscure pockets of volatility and opportunity.
Structural Headwinds and Inflection Points
Despite the positive top-line outlook, the industry faces a narrow set of challenges that will shape competitive positioning over the coming years. First, environmental and emissions regulations are tightening across key export and domestic markets, particularly in Europe and increasingly in Southeast Asia. Manufacturers are being asked to deliver formulations that maintain performance while reducing volatile organic compounds, odor, and hazardous substances. This is not a compliance checkbox; it is a reformulation burden that affects raw material sourcing, process control, and validation cycles. Companies that treat sustainability as an afterthought will face margin compression and delayed time-to-market, while those that design low-emission architectures early can convert regulatory pressure into a defensible product advantage.
Second, the technical bar for ink performance is rising as digital decoration systems become more capable and more widely deployed. Inorganic pigment-based ceramic inks must withstand fine milling, precise dispersion, and high-temperature firing conditions that can exceed 1250 degrees Celsius in tile production. This requires tighter supplier coordination, consistent batch quality, and formulation stability across varying line speeds and substrate types. As digital printing moves from pilot lines to high-throughput production environments, even minor inconsistencies in viscosity, particle size distribution, or adhesion can translate into elevated rejection rates and operational downtime. The inflection point here is clear: ink is no longer a commoditized consumable but a critical process enabler whose performance directly affects overall equipment effectiveness.
Third, supply chain localization is becoming a strategic necessity rather than a logistical preference. Ceramic manufacturing clusters in Southeast Asia, particularly in Vietnam and Indonesia, are expanding capacity and attracting both machinery and ink suppliers seeking closer proximity to end users. At the same time, procurement teams are increasingly sensitive to lead times, freight volatility, and currency exposure. The result is a market where regional responsiveness, localized technical support, and flexible inventory models are gaining importance alongside product performance. Organizations that remain dependent on distant, inflexible supply structures risk slower reaction times and weaker customer intimacy in fast-moving production markets.
Key Drivers Shaping the Next Growth Cycle
Technology Innovation and Formulation Breakthroughs
Technology is the most visible driver of market evolution, and its influence is accelerating across both product design and production integration. The shift toward low-emission digital inks is a case in point. Recent product announcements highlight formulations that reduce harmful emissions and volatile organic compounds by up to 50 percent compared with standard eco-inks, while also introducing almost no-smelling components to lower environmental impact in factory environments. These advances are not merely cosmetic improvements; they reflect a broader engineering push to reconcile high-temperature durability with workplace safety and regulatory expectations. For manufacturers, this means ink selection increasingly involves trade-offs between adhesion, color consistency, firing tolerance, and emissions profile, all of which must be validated on specific production lines.
Ceramic Package Market
At the same time, inorganic pigment-based ceramic inks continue to demand sophisticated milling and dispersion processes to remain compatible with extreme firing conditions. This technical complexity creates a barrier to entry that favors incumbents with deep formulation expertise and testing infrastructure. It also raises the value of application engineering, because the same ink can behave differently depending on printhead configuration, substrate preparation, and kiln parameters. The commercial implication is that differentiation is moving upstream into R&D capability, quality control rigor, and customer-facing technical support. Companies that can demonstrate repeatable performance across diverse digital decoration setups are better positioned to command premium pricing and longer contract tenure.
Policy and Regulatory Environment
Regulatory dynamics are acting as both a constraint and a catalyst. European REACH compliance and broader environmental impact reduction goals are pushing ink suppliers to redesign formulations and document material safety more comprehensively. This has already prompted notable product launches focused on low-VOC architectures, signaling that compliance is becoming a product development priority rather than a reactive adjustment. In parallel, regional manufacturing expansion in Southeast Asia is shaping a new regulatory landscape where local content expectations, environmental standards, and export requirements intersect. Ink producers and distributors that proactively align their portfolios with these evolving standards can reduce the risk of market access delays and position themselves as preferred partners for manufacturers seeking globally acceptable output.
The regulatory dimension also affects downstream demand. Tile manufacturers and homeware producers facing stricter emissions criteria in their own operations are increasingly inclined to select inks that simplify their compliance burden. This creates a pull effect where ink specifications are evaluated not only on print quality but also on the broader environmental footprint of the decorated product. As a result, regulatory alignment is becoming a commercial differentiator, especially in markets where export competitiveness depends on meeting diverse destination-country requirements.
Demand-Side Shifts in Consumer and Industrial Behavior
Demand is being reshaped by the broader adoption of digital decoration in high-volume ceramic production. In markets with massive tile output, digital ink adoption is accelerating as producers seek greater design flexibility, shorter changeover times, and more consistent repeatability across batches. This shift is not limited to luxury or custom segments; it is increasingly relevant in standard production lines where manufacturers want to respond faster to fashion cycles and regional preference variations without sacrificing throughput. The net effect is a rising appetite for ink systems that can support frequent design changes while maintaining line stability.
On the decorative side, consumer expectations continue to push for richer patterns, more realistic textures, and tighter color matching across product families. These expectations place additional pressure on ink color fidelity and gloss control. Meanwhile, functional requirements are expanding beyond aesthetics into areas such as surface durability, hygiene compatibility, and specialized coatings for containers and glass applications. The demand story is therefore bifurcating: volume-driven tile markets want reliability and speed, while design-sensitive and functional applications want performance precision. Ink manufacturers that can serve both poles with a coherent portfolio and clear application guidance are likely to capture a broader share of wallet.
Supply Chain and Cost Structure Dynamics
Cost structures are evolving as raw material inputs, energy considerations, and logistics complexity interact with formulation intensity. Inorganic pigment-based inks require fine milling and dispersion, which means that processing quality and material consistency have direct implications for yield and cost per fired unit. Any disruption in pigment supply, solvent availability, or specialized additives can ripple through the value chain and affect both pricing and delivery reliability. At the same time, the trend toward localized production in Southeast Asia is altering the cost calculus by reducing transport distances for certain markets while introducing new operational requirements around regional quality assurance and technical staffing.
This shifting cost environment rewards suppliers that can balance formulation sophistication with manufacturing efficiency. It also rewards buyers who evaluate total cost of ownership rather than unit price alone. In practice, that means factoring in waste reduction, printhead compatibility, cleaning frequency, firing stability, and rework rates. Ink that appears cheaper on a per-liter basis may underperform when measured against line efficiency and finished-product quality. As procurement teams become more sophisticated in this assessment, suppliers with transparent performance data and strong application support gain an advantage in price negotiations.
Competitive Landscape and Leading Strategies
Incumbents with Technical Depth and Regional Reach
The market features a mix of specialized ink manufacturers, global equipment-linked ink providers, and ceramic machinery groups that also supply inks and glazes. Sicer S.p.A. stands out for its focus on digital inks tailored to ceramic tile decoration, including low-emission formulations and custom series designed for specific decoration workflows. Its recent emphasis on low-emission digital inks achieving up to 50 percent VOC reduction illustrates how a focused manufacturer can turn environmental pressure into a product story. A.T. Inks, based in India, positions itself as a large-scale producer of inorganic pigment-based ceramic inkjet inks for wet-on-wet tile printing up to 1250 degrees Celsius firing. Its scale and formulation orientation make it relevant for high-volume producers seeking reliable pigment performance under extreme firing conditions.
NUtec Digital Ink operates with a broader digital ink portfolio spanning UV-cured, solvent, and water-based systems, supporting ceramic printing and homeware applications. This multi-technology footprint allows it to serve customers with varied process preferences and substrate requirements. EFI brings long-standing formulation expertise in eco-solvent and water-based ceramic inks for digital tile decoration, which positions it as a partner for producers already embedded in its equipment ecosystem or seeking proven compatibility. KEDA Industrial Group, as a ceramic machinery supplier, showcases inks and glazes alongside equipment at industry events, reinforcing an integrated value proposition that appeals to manufacturers looking to streamline supplier relationships and align ink selection with machine capability.
Strategic Positioning and Differentiation
Across these players, differentiation is emerging along three axes: formulation specialization, regulatory readiness, and application ecosystem support. Formulation specialization matters because high-temperature durability, color consistency, and printhead compatibility are not trivial to achieve at scale. Regulatory readiness matters because low-emission and low-VOC positioning is increasingly tied to market access and customer procurement criteria. Application ecosystem support matters because digital decoration success depends on more than the ink bottle; it depends on line integration, maintenance practices, and troubleshooting responsiveness. Suppliers that combine these elements can move beyond transactional selling and into solution-level relationships.
Recent industry developments reinforce this direction. The launch of new low-VOC ceramic ink lines to reduce environmental impact demonstrates a clear regulatory and sustainability response. The opening of new manufacturing facilities in Vietnam for Southeast Asia operations reflects the localization theme and the desire to serve emerging ceramic clusters with shorter supply chains. Trade show participation and product announcements continue to be important signaling mechanisms, particularly in regions where face-to-face technical engagement and live demonstrations influence procurement decisions. Taken together, these moves indicate that competitive advantage is being built through a combination of product engineering, geographic responsiveness, and visible commitment to compliance and customer support.
Evolution of the Market Structure
The market is not heading toward a simple monopoly or a fragmented free-for-all. It is more likely to evolve through selective consolidation among suppliers seeking broader portfolios and geographic coverage, alongside continued specialization by niche players who serve specific printing technologies, verticals, or regional needs. New entrants may appear, but the technical barriers around high-temperature performance, dispersion quality, and application validation will remain significant. As a result, the most disruptive threats may not come from isolated ink startups but from integrated equipment-ink-material combinations that simplify adoption for tile manufacturers and homeware producers. The competitive logic is shifting from product-only competition to process-level relevance, where ink is evaluated as part of a larger digital decoration system.
Forecasting the Next 3–5 Years
Trend 1: Low-Emission and Compliant Formulations Will Become Baseline Expectations
Over the next few years, low-emission and low-VOC architectures will transition from premium differentiators to baseline requirements in many markets. This shift will be driven by regulatory momentum, workplace safety expectations, and downstream customer preferences for cleaner production processes. Ink suppliers that treat this as a one-time reformulation exercise may find themselves repeatedly catching up, while those that build compliance and emissions reduction into their core formulation philosophy can offer a more stable value proposition. The commercial opportunity lies in packaging compliance with performance, so that customers do not have to choose between environmental goals and print quality.
PW Consulting
Trend 2: Digital Integration Will Deepen the Value Chain
Digital decoration will continue to expand beyond high-end segments into broader production volumes, especially in regions with large-scale ceramic output. As this happens, ink will become more tightly coupled with printer configuration, substrate preparation, and firing profiles. The result will be greater demand for integrated solutions, technical validation services, and application-specific tuning. This trend favors suppliers that can support line trials, provide repeatable setting parameters, and help customers reduce trial-and-error cycles. It also raises the stakes for equipment-ink compatibility, which may encourage closer cooperation between ink manufacturers and printer makers.
Trend 3: Regional Manufacturing Hubs Will Reshape Supply and Demand Patterns
Southeast Asia’s ceramic manufacturing clusters will continue to influence where ink capacity is located, how quickly new products reach end users, and how suppliers compete on responsiveness. Localized production and support can shorten feedback loops, improve service levels, and reduce exposure to long-haul logistics disruptions. At the same time, regional expansion introduces challenges around quality consistency, talent development, and coordination across multiple markets with different regulatory and customer expectations. The strategic opportunity is to build regional presence that is not merely logistical but technically credible, with local teams capable of supporting formulation queries, line optimization, and compliance documentation.
Associated Risks and Uncertainties
These trends carry meaningful uncertainties. Regulatory requirements may diverge across regions, creating compliance complexity for globally distributed portfolios. Raw material availability and energy cost fluctuations can pressure margins, especially for formulations that depend on specialized pigments and dispersion processes. Demand may also shift faster than expected if digital adoption accelerates in some markets while lagging in others, leaving suppliers with uneven capacity utilization. Finally, competition from integrated equipment-ink offerings could compress standalone ink pricing in certain segments, particularly where customers prioritize convenience and system compatibility over independent supplier choice. Companies that monitor these signals closely and maintain flexible product and supply strategies will be better positioned to adapt.
Actionable Recommendations for Decision-Makers
For Manufacturers and Production Leaders
Evaluate ink selection as a process decision rather than a consumable purchase. Prioritize trial data that reflects your actual line speeds, substrates, and firing conditions, and compare total cost of ownership across performance, waste, rework, and maintenance. If environmental compliance is becoming more important to your customers or your own operations, ask suppliers for clear documentation on emissions profiles, material safety, and validation support. Where digital decoration is expanding, invest in application engineering relationships that can help stabilize settings and reduce changeover friction. A disciplined evaluation framework will help avoid false economies from low-cost inks that underperform in production.
For Investors and Strategy Teams
Look for value creation at the intersection of formulation strength, regulatory readiness, and regional service capability. Companies that can demonstrate low-emission performance without sacrificing firing durability, and that maintain credible technical support in growth markets, are likely to earn stronger customer loyalty and more defensible margins. Pay attention to integration signals as well: partnerships or product alignments between ink suppliers and equipment providers may reveal where the market is heading in terms of bundled solutions and channel power. In parallel, track capacity expansion in Southeast Asia and the associated localization of supply chains, since these moves can influence both competitive intensity and regional demand trajectories.
For Procurement and Sourcing Professionals
Broaden evaluation criteria beyond unit price to include consistency, compatibility, and compliance readiness. Request performance evidence tied to high-temperature firing and digital print workflows, and verify that suppliers can support repeat orders with stable specifications. Consider multi-supplier or region-specific sourcing strategies if your production footprint spans multiple markets with different regulatory or logistics conditions. Where possible, negotiate for clear application support and issue resolution timelines, since responsiveness during line problems often matters more than marginal price differences. A well-structured sourcing approach can reduce operational risk while preserving flexibility as production needs evolve.
The ceramic ink market is moving through a period where growth is real but uneven, and where competitive advantage depends on how well companies align product performance with regulatory expectations, digital production realities, and regional demand patterns. The organizations that will benefit most are those that treat ink as a strategic input, build evidence-based procurement and investment decisions, and stay attentive to the intersection of formulation science, compliance, and market localization. For leaders who need a more granular view of segment dynamics, regional breakdowns, application-level demand splits, and company-level positioning beyond the trends outlined here, the full research report provides the detailed segmentation data and customized analysis required to translate these insights into concrete plans.
For detailed analysis of this topic, please visit the official page: Ceramic Ink Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


