



Wheat Seeds Market: Why the 3.75% CAGR and Asia Pacific Shift Changes Everything

Cultivating Growth: Strategic Trends and Commercial Opportunities in the Global Wheat Seeds Market
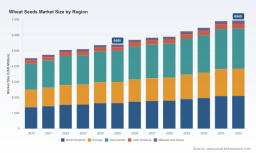
The global wheat seeds market is navigating a complex phase of structural transformation, balancing steady baseline expansion against breakthrough technological and regulatory shifts. Valued at approximately 5.4 billion USD in 2025, the sector has demonstrated consistent growth over the past half-decade, with revenue climbing from 4.52 billion USD in 2020 to the current level. Driven by a compound annual growth rate of 3.75 percent, the market is projected to approach 6.94 billion USD by 2032. This trajectory reflects more than population-driven demand; it captures an agricultural ecosystem under pressure to deliver higher yields, enhance climate resilience, and adapt to an increasingly fragmented regulatory and competitive environment. For stakeholders operating in or adjacent to wheat production, understanding where growth is structurally anchored—and where hidden inflection points lie—is essential for long-term positioning.
Beneath the aggregate growth figures, several structural realities define the competitive arena. The market is moderately consolidated but far from monopolistic, with the top three players commanding roughly 26.5 percent of revenue and the top five collectively holding 31.8 percent. This leaves considerable distributed capacity among regional specialists, niche breeders, and emerging biotechnological entrants. Meanwhile, the fundamental product architecture remains tilted toward established cultivation cycles, with winter wheat genetics accounting for the largest share of commercial activity, while spring and durum varieties serve distinct agronomic and milling requirements. The dominant use case remains commercial planting, which dwarfs smaller-scale and personal cultivation channels. The following analysis unpacks the forces reshaping this landscape, evaluates how incumbents and challengers are responding, and maps actionable pathways for executives, investors, and procurement leaders.
Market Snapshot and Core Challenges
A Steady Growth Curve Meets Structural Friction
The historical performance of the wheat seeds market from 2020 through 2025 illustrates resilience rather than volatility. Growth was neither explosive nor stagnant; instead, it reflected incremental adoption of improved genetics, steady acreage expansion in key growing zones, and gradual replacement cycles in established seed portfolios. The forecast period through 2032 projects continued expansion, though the pace suggests maturation rather than disruption in baseline demand. The real story lies not in headline numbers but in the pressure points emerging beneath them.
Hemp Seeds Market
Three interconnected challenges define the current inflection point. First, genetic yield plateaus in conventional breeding programs are forcing players to look beyond traditional trait stacking toward hybridization and gene-edited solutions, both of which carry higher development costs and longer commercialization timelines. Second, regulatory asymmetry across major growing regions is fragmenting what would otherwise be a more unified global rollout of advanced seed technologies, forcing companies to navigate divergent approval timelines, labeling requirements, and consumer acceptance thresholds. Third, supply chain volatility in parent seed production, propagation infrastructure, and input costs is compressing margins for mid-tier breeders while rewarding those with vertically integrated or regionally optimized distribution networks. These pressures do not halt growth, but they reshape who captures value and at what cost.
Where Pressure Turns Into Opportunity
The same constraints that challenge incumbents create entry points for organizations that can align innovation with regional readiness and risk mitigation. Hybridization, for instance, has historically struggled with wheat due to self-pollination biology and layout complexity, yet recent registration milestones and insurance provisions for parent seed production are lowering barriers to commercial scale. Similarly, the emergence of climate-resilient and input-efficient genetics is shifting procurement conversations from price-per-unit toward total agronomic value, allowing premium positioning where performance data and regulatory clarity align. Understanding which sub-segments are ready for technology adoption—and which remain dependent on cost-driven conventional offerings—is the first step in mapping a credible growth strategy.
Key Drivers Reshaping the Market
Technological Breakthroughs in Wheat Genetics
The most consequential shift in the wheat seeds market is the gradual translation of hybrid and biotechnological concepts into commercial reality. Wheat has long been considered a challenging crop for hybridization due to its floral structure and inbreeding tendencies, but targeted breeding platforms, doubled haploid techniques, and precision trait introgression have begun to overcome those biological constraints. Hybrid wheat varieties promise yield advantages, improved standability, and enhanced stress tolerance, yet they also require reliable parent seed supply chains and farmer confidence in replanting economics. The barrier to adoption is no longer purely biological; it is commercial infrastructure and trust in performance consistency.
Alongside hybridization, gene-editing and transgenic approaches are moving from pilot stages to limited commercial availability. The first commercial distribution of HB4 GM wheat seeds in Argentina marked a landmark shift, demonstrating that drought-tolerant and productivity-enhancing wheat traits can reach the market when regulatory pathways and regional acceptance align. This development does not instantly rewrite the global seed portfolio, but it establishes a reference point for what is technically possible and commercially viable under the right conditions. For breeders and technology platforms, the strategic implication is clear: incremental trait improvement is no longer sufficient where climate volatility and input constraints are accelerating. Differentiated performance under stress is becoming the core value proposition.
Policy and Regulatory Dynamics as Market Architects
Regulation continues to function as both a gateway and a competitive filter. Recent policy moves illustrate how regulatory clarity can unlock segments that were previously stalled by uncertainty. The introduction of hybrid wheat seed crop provisions for the 2026 crop year and beyond, including insurance coverage for parent seed production by seed companies, directly addresses a long-standing risk in hybrid wheat commercialization. By reducing the financial exposure associated with maintaining parent lines, such provisions lower the threshold for scaled deployment and encourage greater investment confidence from both seed developers and growers.
At the same time, merger activity and concentration trends in the broader seeds and agricultural chemicals sector remain under institutional scrutiny, with documentation pointing to the four largest firms holding a significant share of the global seed market. This concentration is not necessarily negative for innovation; in many cases, it provides the capital base required for long-cycle breeding programs and trait development. However, it also raises the stakes for regional players and specialty breeders, who must compete on localized adaptation, service intensity, and niche performance rather than scale alone. The regulatory environment is therefore shaping not just which technologies reach the field, but which organizational models can sustainably support them.
Demand-Side Shifts and the Total Value Conversation
On the demand side, wheat procurement is increasingly influenced by a wider set of criteria beyond yield per hectare. Farmers and agribusiness buyers are weighing stability under variable weather patterns, input efficiency, disease pressure management, and end-market quality requirements. Food processors, livestock operators, and export-oriented supply chains are pushing for consistency in protein content, milling characteristics, and agronomic predictability, which in turn shapes the seed selection logic at planting time. This broader value calculus supports premium offerings where performance can be demonstrated and documented, but it also raises the evidentiary burden for new genetics.
Consumer sentiment and export market standards add another layer of complexity. In regions where non-GM or conventionally bred wheat maintains stronger market acceptance, the route to advanced genetics may rely on gene editing or precision breeding rather than transgenic approaches, or it may focus on hybrid vigor without altering the crop's regulatory classification. In contrast, markets facing acute water stress or yield instability may show greater openness to drought-tolerant or stress-resilient seed technologies. This divergence means that demand growth is not uniform; it is conditional on regional risk profiles, end-use requirements, and the speed at which agronomic proof is translated into commercial trust.
Supply Chain and Cost Structure Pressures
The economics of seed multiplication remain a critical constraint. Parent seed production, purification, and distribution require reliable sourcing, biosecurity controls, and logistics that can preserve genetic integrity across batches. In a period of input cost variability and logistics disruption, the cost structure of seed supply can determine whether a promising variety reaches commercial scale or remains confined to limited trials. Companies with stronger regional multiplication capacity, tighter quality assurance, and better integration with agronomic service networks are better positioned to manage these pressures.
Cost pressures also influence portfolio decisions. High-development technologies must be matched with realistic commercialization pathways and pricing models that growers can absorb without sacrificing overall farm economics. This dynamic rewards strategies that combine clear performance differentiation with practical deployment support, including guidance on planting windows, crop management, and expected return under local conditions. Where seed suppliers can reduce uncertainty for the buyer, pricing becomes less of a standalone negotiation and more of a component in a broader agronomic partnership.
Competitive Landscape and Leading Strategies
Incumbents Anchored in Scale, Pipeline, and Regional Depth
The mature players in the wheat seeds market approach the sector from different angle points, but a common theme is the integration of breeding capability with broader crop portfolios and downstream support. Bayer AG continues to leverage its global reach and integrated crop science platform to offer wheat genetics alongside complementary crop protection and digital agronomy tools. Its differentiation rests on scale, multi-environment testing capacity, and the ability to bundle seed solutions with management practices that stabilize outcomes across variable conditions.
Corteva Agriscience brings a strong emphasis on trait development and corn-and-soy Adjacent technology platforms, while maintaining a focused wheat seed offering that benefits from rigorous breeding pipelines and farmer-facing service networks. Its strategic value lies in combining genetics with agronomic advisory capabilities and in leveraging data from broadacre cropping systems to improve selection accuracy and deployment timing.
Syngenta Group has moved aggressively to strengthen its hybrid wheat presence, most visibly with recent registration and launch activity around hybrid wheat varieties for European sowing seasons. By securing approvals and making specific hybrids available for upcoming planting cycles, Syngenta is attempting to convert technological readiness into commercial momentum. Its differentiation strategy emphasizes hybridization as a yield and resilience lever, backed by variety-specific availability and regional launch timing.
BASF SE has similarly positioned hybrid wheat seed sales as a contributing element within its agricultural solutions segment, with a particular focus on European markets for the 2025/2026 cycle. For BASF, the wheat seed opportunity is not isolated; it is part of a broader crop solutions ecosystem where seed, chemistry, and digital support can be aligned to improve field outcomes. This integrated posture helps justify investment in higher-complexity seed technologies by linking them to wider value capture.
Specialists, Regional Breeders, and the Distributed Edge
Beyond the largest multinationals, a substantial layer of specialized and regionally rooted companies competes on adaptation, responsiveness, and niche performance. Groupe Limagrain, KWS SAAT SE & Co. KGaA, RAGT Semences, and Florimond Desprez each bring deep European breeding traditions and strong local market knowledge, often with varieties tailored to specific soil, climate, and end-use conditions. Their strength is not necessarily to outspend global incumbents, but to offer varieties and service models that resonate with regional growers seeking locally validated performance.
In the Americas, companies such as AgReliant Genetics, Land O'Lakes Inc., ProHarvest Seeds, and AgriMAXX Wheat reflect different models of distribution, cooperative alignment, and wheat-focused breeding. AgReliant Genetics operates with a multi-channel seed business structure, while Land O'Lakes Inc. benefits from its broader agricultural cooperative network, which can support seed adoption through established customer relationships and region-specific agronomic support. ProHarvest Seeds and AgriMAXX Wheat illustrate how focused wheat portfolios can build loyalty by concentrating on core growing zones and practical farmer-facing value.
Bioceres Crop Solutions represents a distinct strategic profile, combining trait technology development with commercial execution in markets open to advanced wheat genetics. Its early commercial activity with HB4 GM wheat in Argentina underscores a strategy centered on regulatory-first market entry and targeted geographic deployment rather than global simultaneous rollout. This model highlights how technology differentiation can be paired with market selectivity to create early-mover advantage in specific jurisdictions.
How the Competitive Map Is Evolving
The current landscape is characterized by simultaneous consolidation pressure and differentiation opportunity. On one side, the largest firms continue to benefit from scale, capital intensity, and cross-portfolio synergies, which supports long-cycle breeding investment and global testing networks. On the other side, the distributed base of regional breeders and specialty players retains relevance by offering locally adapted genetics, flexible supply relationships, and stronger direct engagement with growers. The market has not tipped toward a single formula; rather, it is bifurcating into scale-driven technology platforms and regionally optimized performance specialists.
Rice Seed Market
New entry and expansion are most likely where technological readiness converges with regulatory clarity and where supply chain readiness supports multiplication at commercial scale. Hybrid wheat is a prime example: the biological and operational challenges are being reduced by improved breeding methods and supportive risk provisions, but commercial success still depends on regional launch timing, parent seed availability, and farmer adoption economics. Biotechnology-driven wheat traits face an even more selective path, with early progress tied to specific regulatory environments and end-market acceptance. In both cases, the winners are likely to be organizations that can synchronize technology, geography, and commercial infrastructure instead of treating each as an independent variable.
PW Consulting Health Care Research Center
Future Trends and Strategic Opportunities (2026-2032)
Hybridization Moves From Demonstration to Commercial Scale
Hybrid wheat is expected to transition from a promising concept to a more mainstream commercial category over the next several years, particularly in regions where registration pathways are navigable and parent seed production can be supported with manageable risk. The combination of improved breeding platforms, targeted launch strategies, and policy provisions that reduce production risk creates a more favorable environment for scaled deployment. The commercial opportunity lies not simply in selling a different seed category, but in building the accompanying agronomic support, quality assurance, and supply reliability that make hybrid adoption economically rational for growers. Companies that can prove consistent performance, manage multiplication risk, and deliver clear return expectations will be best positioned to capture share in this transitioning segment.
Regional Differentiation as the New Competitive Default
As technology portfolios become more diverse, regional differentiation will increasingly define competitive success. Uniform global rollouts will remain limited by divergent regulatory acceptance, varying climate stress profiles, and different end-use quality requirements. The strategic implication is that seed innovation will be adopted unevenly, with some regions prioritizing hybrid vigor, others focusing on drought or heat tolerance, and still others emphasizing disease resistance or milling quality. This unevenness creates space for organizations that build region-specific evidence packages, align variety selection with local risk profiles, and tailor service models to regional procurement behavior. Growth will increasingly come from matching the right technology to the right conditions, not from pushing a single offering everywhere.
Ecosystem Integration and Data-Enabled Deployment
The third trend is the deepening integration of seed offerings with broader crop management ecosystems. Advanced seed technologies are more valuable when paired with practical guidance on planting windows, nutrient management, pest pressure timing, and harvest strategy. This creates an opportunity for seed providers to strengthen their role as agronomic partners rather than product vendors alone. Data from multi-environment trials, on-farm performance monitoring, and localized management recommendations can improve adoption confidence and support premium positioning where results are repeatable. At the same time, the trend raises the bar for operational excellence: the organizations that win will be those capable of linking genetic potential with field-level execution in a consistent, credible way.
Potential Risks and Unresolved Uncertainties
Despite a constructive growth outlook, several uncertainties warrant caution. Regulatory divergence may slow or fragment the rollout of advanced wheat technologies in key export and consumption markets, limiting the addressable opportunity for certain trait types. Adoption risk remains significant for hybrid wheat if parent seed supply, seed pricing, or replanting economics fail to meet grower expectations. Concentration dynamics may also create pressure on smaller breeders, especially where scale advantages in testing, multiplication, and distribution become harder to offset. Finally, climate volatility can produce localized mismatches between variety performance assumptions and actual field conditions, underscoring the need for robust testing, transparent communication, and flexible portfolio management.
Strategic Recommendations for Decision-Makers
For Seed Manufacturers and Trait Developers
Prioritize commercialization pathways that align technology readiness with regional regulatory clarity and multiplication capacity. Where hybrid wheat or advanced trait offerings are being prepared, build the supply chain and agronomic support infrastructure in parallel rather than treating them as afterthoughts. Focus on varieties and traits that deliver measurable performance under local stress conditions, and document results in a way that reduces buyer uncertainty. Differentiation will increasingly depend on how convincingly a company can connect genetics to field-level outcomes, not just on breeding novelty alone.
For Investors and Strategic Backers
Evaluate opportunities through the lens of regional readiness and execution capability rather than technology promise alone. The most attractive risk-adjusted bets are likely to sit at the intersection of clear regulatory standing, credible parent seed or multiplication logistics, and strong local distribution or service relationships. Monitor concentration trends, but also watch for regional specialists and biotechnology-first entrants that can establish early dominance in receptive markets. In wheat, the path to value creation is often incremental and geography-specific, which means due diligence should emphasize deployment feasibility as much as scientific differentiation.
For Procurement Leaders and Grower-Serving Organizations
Shift seed purchasing conversations from unit price toward total agronomic risk reduction and performance stability. Where advanced genetics are available, test them against local conditions and evaluate the full support package, including planting guidance, multiplication reliability, and expected performance consistency across variable seasons. Diversifying portfolios by matching varieties to specific risk profiles and end-use requirements can improve resilience without relying on a single flagship offering. In practice, the strongest procurement strategies will combine selective adoption of differentiated seed technologies with disciplined evaluation of supply reliability and local agronomic fit.
Closing Perspective
The wheat seeds market is not on the verge of a single disruptive shift; it is undergoing a series of reinforcing changes that reward organizations capable of integrating technology, geography, and execution. Steady baseline growth provides a durable foundation, while hybridization, regulatory developments, demand-side value recalibration, and supply chain dynamics are reshaping where additional value is created. The competitive map remains layered, with global scale players, regional specialists, and technology-first entrants each pursuing distinct routes to advantage. For executives, investors, and procurement leaders, the strategic task is to identify which sub-segments, geographies, and technology pathways align with operational capabilities and risk tolerance. Detailed segmentation data, company-level comparisons, and customized strategic scenarios can sharpen that assessment further and support more confident decisions in a market where timing and fit increasingly determine outcomes.
For detailed analysis of this topic, please visit the official page: Wheat Seeds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


