



VCI Anti Rust Paper Market: Why 4.8% CAGR and Hidden Applications Reshape 2032 Outlook

The VCI Anti Rust Paper Market: Strategic Trends and Commercial Opportunities Through 2032
Market Snapshot and the Road Ahead
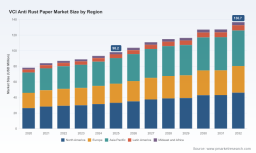
The global VCI anti rust paper market has demonstrated consistent expansion over the past half decade, moving from approximately 78.25 million USD in 2020 to an estimated 98.2 million USD in 2025. This trajectory reflects a compound annual growth rate of 4.8 percent, with projections indicating the market will cross the 136 million USD threshold by 2032. The growth is not merely a function of incremental volume increases but rather a structural shift in how manufacturers, logistics providers, and industrial distributors approach asset protection during storage and transit. Corrosion prevention has evolved from a compliance afterthought into a strategic component of supply chain resilience, quality assurance, and total cost of ownership calculations. Beneath these headline figures lies a market with concentrated positioning and distinct regional and sectoral imbalances. A handful of established players command the majority of market share, with the top three firms accounting for roughly 62.5 percent and the top five reaching 78.2 percent of total revenue. This concentration signals a mature competitive landscape where differentiation, rather than scale alone, determines winners. At the same time, regional demand patterns reveal divergent growth drivers, with developed markets focusing on regulatory compliance and technical performance while emerging economies prioritize cost-effective corrosion protection for expanding metalworking and packaging sectors. Understanding these underlying dynamics is essential for decision makers evaluating market entry, capacity expansion, or supplier relationships.
Structural Challenges Shaping the Market
Several intersecting challenges are forcing the industry to recalibrate its growth assumptions and operational strategies. Recognizing these friction points early allows executives to build more resilient business models rather than reacting defensively when pressures intensify.
One of the most pressing challenges is the tightening regulatory environment around chemical formulations. Environmental and safety directives in major markets are progressively restricting amine-based volatile corrosion inhibitors and phthalate-based plasticizers commonly used in VCI film and paper products. Compliance is no longer a static checkbox; it requires continuous reformulation, testing, and documentation. Companies operating with legacy chemistries face escalating scrutiny, while those that proactively transition to nitrite-free, renewable, and fully repulpable formulations are positioning themselves to capture procurement mandates from increasingly sustainability-conscious buyers.
A second challenge stems from cost inflation across raw material inputs and logistics channels. Amine chemistry feedstocks and transportation expenses have exerted sustained pressure on margin structures for VCI packaging materials. In an environment where end users are highly price-sensitive and alternative barrier solutions remain available, suppliers must balance cost pass-through with value demonstration. The burden falls on manufacturers to articulate how advanced VCI paper reduces total lifecycle costs through reduced damage, lower warranty claims, and extended storage life, rather than competing solely on unit price.
A third structural challenge involves the heterogeneity of end-use requirements. Metal packaging, machinery and equipment, and other industrial applications each impose distinct performance criteria, exposure conditions, and regulatory expectations. A formulation that performs adequately for ferrous metal storage may not satisfy multi-metal protection requirements or extended duration needs. This fragmentation complicates standardization and increases the cost of tailored product development. Companies that fail to align product architectures with specific application profiles risk losing share to competitors offering more precise fit-for-purpose solutions.
Core Drivers Catalyzing Market Evolution
The market's continued expansion is being propelled by a combination of technological innovation, regulatory realignment, shifting demand behaviors, and supply chain restructuring. Each driver reinforces the others, creating compounding effects that reward early movers and penalize laggards.
Technology and chemistry innovation remains the most decisive differentiator. Recent advancements in vapor-phase corrosion inhibition have enabled formulations that deliver extended protection without compromising recyclability or repulpability. The development of VCI nanotechnology on renewable kraft substrates illustrates how performance and sustainability can converge rather than compete. Products that combine expandable cushioning with active corrosion inhibition represent a step change in functional packaging, addressing both mechanical protection and long-term metal preservation within a single consumable. These innovations reduce the need for multiple packaging layers, simplify handling, and improve protection consistency across complex part geometries.
Policy and regulatory pressure is accelerating the transition toward compliant chemistries across key markets. Regulatory frameworks are increasingly mandating nitrite-free formulations and pushing for biodegradable and safer chemical profiles in VCI papers. In parallel, air quality and emission standards are raising compliance costs for amine-based chemistries, making reformulation an operational necessity rather than a discretionary initiative. Companies that treat regulatory evolution as a strategic signal rather than a compliance expense are building portfolios with longer regulatory half-lives and broader geographic applicability.
Demand-side behavior shifts are reshaping procurement priorities. Industrial buyers are placing greater weight on lifecycle performance, environmental footprint, and vendor reliability when selecting corrosion protection solutions. The emphasis has moved beyond immediate cost to include total cost of ownership, risk mitigation, and alignment with corporate sustainability commitments. This shift is particularly pronounced among operators managing high-value machinery, sensitive electronic components, and long-duration storage scenarios, where corrosion-related failures carry significant financial and reputational consequences. Procurement teams are consequently favoring suppliers that can demonstrate consistent performance, transparent chemistry, and documentation supporting waste reduction and material recovery.
Supply chain and cost structure changes are influencing sourcing strategies and manufacturing footprints. Volatility in raw material pricing and freight costs has prompted buyers to diversify suppliers, shorten supply lines where feasible, and prefer partners with localized production or regional distribution capabilities. At the same time, manufacturers are investing in process efficiencies and formulation optimization to absorb input cost pressures without eroding margins. The result is a market where responsiveness, reliability, and formulation flexibility are becoming as important as base pricing.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a core group of specialized manufacturers whose strategic approaches illuminate the pathways to sustained advantage. While market concentration remains high, the nature of competition is shifting from broad product availability toward targeted technical value, regulatory readiness, and application-specific performance.
Cortec Corporation has built its positioning around renewable, recyclable, and fully repulpable VCI chemistry applied to kraft paper substrates. Its coated VCI papers are designed for both ferrous and non-ferrous metal protection across storage and shipping contexts. The strategic emphasis on a circular-material profile aligns with procurement teams seeking to reduce waste streams and simplify end-of-life handling while maintaining active corrosion inhibition.
Daubert Cromwell has focused on nitrite-free formulations and compliance-oriented product lines, including VCI papers aligned with recognized military specifications for multi-metal corrosion protection. This compliance-centric posture appeals to sectors where documentation, standardization, and chemical safety are non-negotiable, such as defense, aerospace-adjacent supply chains, and regulated industrial manufacturing.
ZERUST Solutions offers VCI kraft papers and reinforced or poly-coated variants that provide vapor-phase protection for ferrous metals. The breadth of substrate options enables coverage across different handling conditions and exposure profiles, allowing the company to address varied industrial requirements without fragmenting its core technology.
Volatile Corrosion Inhibitors (VCI) Packaging Material Market
Intertape Polymer Group emphasizes extended-duration protection, with nitrite-free VCI saturated kraft papers that support multi-metal protection over long storage intervals. The ability to specify protection duration is a meaningful commercial lever in logistics-heavy environments where parts may remain in transit or warehousing for extended periods.
Antirusting Anti Rust Agents Market
Armor Protective Packaging has combined nanotechnology-enabled corrosion inhibition with renewable kraft substrates, including expandable cushioning formats that integrate mechanical protection and VCI function. Its recent collaborative launch of an expandable VCI paper concept underscores a broader industry move toward multi-functional packaging that reduces material complexity while improving performance.
Rust-X has concentrated on durability attributes such as tear and puncture resistance through super laminated VCI papers. For operations handling heavy, irregular, or high-abrasion metal components, mechanical robustness is a critical purchase criterion, and this focus differentiates the offering in applications where standard paper formats may be prone to failure.
PW Consulting
Across these players, several strategic themes emerge. First, differentiation is increasingly rooted in chemistry transparency, regulatory alignment, and sustainability credentials rather than price alone. Second, product architectures are becoming more application-specific, with reinforcement, coating, and saturated formats tailored to distinct handling and exposure conditions. Third, the market is experiencing incremental convergence between mechanical protection and active corrosion inhibition, reducing the need for layered packaging and improving total system performance.
The evolutionary trend in market structure points toward selective consolidation and continued specialization. Established players with strong technical portfolios and regulatory readiness are well positioned to absorb niche capabilities or expand into adjacent format segments. At the same time, new entrants may find opportunity in highly targeted niches, such as formulations for specific metal alloys, biodegradable variants, or region-specific compliance packages. Broad, undifferentiated entry is less viable in a market where performance validation and regulatory familiarity carry substantial weight.
Forward Outlook: Three Trends to Watch
Looking ahead across the next three to five years, several trends are likely to shape investment, sourcing, and product strategy in the VCI anti rust paper market.
Accelerated reformulation toward compliant, renewable chemistries will intensify as regulatory scrutiny deepens and buyer sustainability requirements become more explicit. Companies that proactively retire higher-risk chemistries and develop nitrite-free, biodegradable, or fully repulpable solutions will gain preferential access to procurement cycles in regulated and sustainability-focused segments. The commercial opportunity lies not only in compliance but in the ability to market a clear environmental and safety narrative that reduces buyer risk and aligns with corporate responsibility goals. The associated risk is execution lag; firms that delay reformulation may face sudden exclusion from bids that specify chemical restrictions or biodegradability criteria.
Multi-functional packaging will continue to gain share as operators seek to simplify material stacks and improve protection consistency. Integrating cushioning, barrier properties, and vapor-phase corrosion inhibition into a single paper-based solution reduces handling complexity and can lower total packaging cost even when per-unit pricing is higher. This trend opens opportunities for manufacturers that can combine mechanical robustness with active inhibition and for buyers who can rationalize SKU counts and supplier relationships. The risk is that over-functionalization may increase cost or compromise recyclability if substrate choices are not carefully managed, so technical validation remains essential.
Regional divergence in demand and compliance requirements will create both fragmentation and arbitrage opportunities . Mature markets will continue to emphasize regulatory conformity, documentation, and lifecycle performance, while faster-growing regions will balance performance with affordability and supply reliability. Suppliers with flexible formulation platforms, localized distribution, and the ability to tailor products to regional regulatory baselines will be better positioned to capture cross-market growth. The uncertainty lies in the pace and symmetry of regulatory adoption across jurisdictions, which can shift competitive advantage quickly if one region moves ahead of others in restricting specific chemistries.
Strategic Considerations for Decision Makers
For manufacturers and product developers, the priority is to align formulation roadmaps with regulatory trajectories and application-specific performance needs. Investing in nitrite-free, renewable, and repulpable chemistries while maintaining protection duration and mechanical robustness will expand addressable demand and reduce regulatory exposure. Equally important is building validated documentation and testing protocols that allow procurement teams to verify performance claims and meet internal sustainability thresholds. Companies that can articulate a clear link between chemistry, protection performance, and end-of-life handling will be better equipped to justify value to buyers who are increasingly scrutinizing total cost rather than unit price. For investors, the market rewards businesses with defensible technical differentiation and resilient compliance postures. Concentration in the top tier suggests that competitive advantage is often tied to formulation IP, regulatory readiness, and application breadth rather than scale alone. Due diligence should therefore emphasize chemistry portfolios, reformulation capability, certification and documentation strength, and the ability to serve multi-metal and extended-duration requirements. Capital allocation toward companies with clear pathways to compliant, multi-functional products and regional flexibility is likely to offer more durable exposure than bets on undifferentiated capacity expansion. For procurement and supply chain leaders, the focus should shift from transactional price comparison to total value evaluation. Evaluating VCI paper suppliers against criteria such as multi-metal compatibility, protection duration, mechanical durability, chemical compliance, and recyclability can reduce downstream risk and improve consistency across storage and shipping operations. Diversifying supply sources while prioritizing vendors with strong regulatory alignment and transparent chemistry reduces vulnerability to reformulation disruptions and regional compliance shifts. Negotiations are more effective when underpinned by performance specifications that reflect actual exposure conditions rather than generic packaging requirements. The pace of regulatory change, input cost volatility, and evolving buyer expectations means that static market assumptions quickly become outdated. Decision makers benefit from continuously updated intelligence on formulation shifts, competitive moves, and regional compliance baselines to avoid misaligned sourcing or investment choices. Detailed segment-level data, company-level profiling, and scenario analysis can sharpen planning and reveal where to concentrate resources for the highest return.
Completing the full analysis provides access to granular segment breakdowns, regional demand profiles, competitive benchmarking, and forward scenarios that extend beyond the directional view presented here. For teams evaluating market entry, supplier selection, formulation investment, or portfolio strategy, that additional depth supports more precise prioritization and reduces the uncertainty inherent in a rapidly evolving corrosion protection market.
For detailed analysis of this topic, please visit the official page: VCI Anti Rust Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


