



Karl Fischer Titrators Market 2026: Beyond the 5.5% CAGR Story

Navigating the Karl Fischer Titrators Market: Strategic Trends and Commercial Opportunities Through 2032
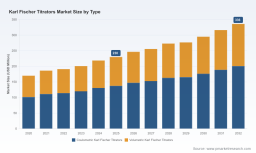
The Karl Fischer titration market has entered a phase of sustained expansion, driven by tightening quality standards, evolving regulatory expectations, and the growing need for precise moisture determination across critical industrial and life sciences applications. Valued at approximately $230 million in 2025, the market has grown consistently from its 2020 baseline, reflecting a compound annual growth rate of 5.5 percent through the forecast horizon ending in 2032. By the close of the projection period, revenue is expected to surpass $335 million, underscoring a steady but structurally shifting demand profile. This trajectory is not merely a function of incremental adoption; it reflects a broader transformation in how organizations approach analytical chemistry, compliance, and operational efficiency. The market's resilience amid macroeconomic fluctuations suggests that moisture analysis has transitioned from a optional quality control step to an embedded requirement across regulated and high-stakes production environments.
Yet expansion alone does not capture the strategic reality facing manufacturers, investors, and procurement leaders. The market is navigating several inflection points that will determine which players capture disproportionate value and which face margin compression or relevance erosion. Understanding these dynamics requires moving beyond headline growth figures and examining the underlying technological, regulatory, and competitive forces reshaping the landscape.
PW Consulting
Market Landscape and Core Challenges
A Market Shaped by Concentration and Capability Gaps
The Karl Fischer titrators market remains moderately concentrated, with the top three participants capturing roughly 70 percent of total revenue and the leading five firms accounting for approximately 85 percent. This concentration reflects the high technical barriers to entry, the importance of reagent ecosystems, and the entrenched procurement relationships within pharmaceutical, chemical, and regulated manufacturing environments. While concentration typically signals stability, it also masks underlying fragmentation in application-specific needs, regional adoption curves, and the widening gap between legacy benchtop systems and next-generation automated or connected platforms. Organizations that continue to treat Karl Fischer titration as a commoditized measurement tool risk underestimating the strategic weight of calibration integrity, data traceability, and operator workflow optimization.
Challenge 1: Balancing Precision with Operational Efficiency
One of the most persistent tensions in the market is the trade-off between measurement precision and throughput. Traditional titration workflows, while highly accurate, often require skilled operators, manual reagent handling, and frequent titer verification. In high-volume environments, these requirements translate into labor intensity, inconsistent turnaround times, and elevated risk of human error. The pressure to increase sample throughput without compromising compliance-grade accuracy is pushing laboratories and production teams to reevaluate their instrumentation strategies. Companies that fail to integrate automation, sample handling, or streamlined calibration routines will find their solutions increasingly misaligned with the operational tempo of modern quality and process labs.
Challenge 2: Regulatory Complexity and Data Integrity Expectations
The regulatory environment surrounding moisture analysis has become more demanding, particularly in pharmaceutical and biotechnology applications where data integrity, auditability, and instrument validation are non-negotiable. Compliance with frameworks such as FDA 21 CFR Part 11 andGood Manufacturing Practice expectations requires more than accurate titration results; it demands secure data handling, version-controlled methods, and traceable calibration records. At the same time, emerging cybersecurity and resilience requirements, including the EU Cyber Resilience Act, are extending compliance obligations into laboratory equipment ecosystems that were historically treated as isolated analytical tools. For manufacturers and end users alike, this creates a dual burden: maintaining analytical rigor while implementing stronger software governance, access controls, and remote diagnostic safeguards.
Challenge 3: Reagent Stability and Supply Chain Reliability
Moisture titration depends heavily on reagent quality and consistency, yet standard solvents and titration reagents introduce operational variability that can quietly erode measurement confidence. Methanol-based solvents used in volumetric Karl Fischer titration, for example, exhibit gradual titer degradation that necessitates regular verification and corrective adjustments. Approximately a 5 percent titer decrease per year is typical, meaning that laboratories must build routine titer checks into their workflows or risk systematic measurement drift. This reality complicates cost planning, increases consumable management overhead, and underscores the importance of reagent formulation innovation. In an era where supply chain volatility can disrupt laboratory operations, the ability to standardize reagent performance and reduce frequent titer corrections is becoming a meaningful differentiator rather than a logistical footnote.
Laboratory Water Purifier Market
Key Drivers Reshaping the Market
Technological Innovation and the Shift Toward Intelligent Titration
Technological advancement is the most visible force propelling market evolution. The industry is moving beyond standalone titration units toward integrated systems that combine faster detection algorithms, automated sample introduction, and smarter calibration logic. Recent product introductions illustrate this shift clearly. In mid-2024, a major analytical instrumentation provider launched a volumetric Karl Fischer titrator featuring a fast-forecasting amperometric algorithm alongside an oven autosampler designed for high-throughput water analysis. The combination of improved signal processing and automated sample handling directly addresses the throughput-versus-precision tension described earlier. A few months later, another manufacturer extended its titrator lineup by upgrading control firmware and electrode systems to improve measurement stability, highlighting how incremental engineering refinements can yield meaningful gains in repeatability and operator confidence.
By early 2025, the trend toward intelligence and remote support became even more pronounced when a leading Swiss instrumentation firm released a titration platform integrating AI-based calibration and remote diagnostics. This move signals a broader industry recognition that instrumentation value is increasingly defined by software-enabled accuracy, predictive maintenance, and reduced downtime rather than mechanical design alone. In parallel, a major scientific instrumentation company introduced a portable Karl Fischer moisture analyzer with wireless connectivity and ruggedized construction for field applications, expanding the addressable use cases beyond controlled laboratory environments into on-site production, logistics, and remote quality checks. These developments collectively point to a market where analytical performance, connectivity, and deployment flexibility are converging.
Regulatory and Compliance Pressures as Adoption Accelerators
Regulatory expectations are not merely constraints; they are powerful adoption drivers. In regulated industries, the requirement for validated methods, documented data integrity, and instrument traceability encourages organizations to upgrade from informal or aging titration setups to compliant, auditable systems. The emphasis on data security and operational resilience is also reshaping procurement criteria. As laboratory operations face updated GMP expectations and broader cybersecurity mandates, buyers are increasingly prioritizing instruments that support secure data handling, controlled user access, and firmware or software update pathways that do not compromise validated states. This regulatory momentum benefits manufacturers that design compliance into their platforms from the outset, while creating friction for those relying on retrofitted or opaque software architectures.
Evolving Demand Patterns Across Regulated and Process Industries
Demand is being shaped by a combination of quality intensification and broader application expansion. In pharmaceutical and biotechnology environments, moisture specification control remains critical for product stability, formulation integrity, and process validation, sustaining steady demand for high-precision titration solutions. In the chemical industry, moisture monitoring influences reaction control, catalyst performance, and product grading, reinforcing the need for reliable titration across both laboratory and process-adjacent settings. Food and beverage applications, while smaller in relative terms, continue to drive adoption where moisture content affects shelf life, sensory properties, and regulatory compliance. Beyond these core segments, additional application areas contribute to demand diversification, including specialized industrial testing and routine quality assurance workflows.
What matters strategically is not just the existence of these application segments, but the changing expectations within them. End users increasingly want solutions that reduce hands-on time, simplify reagent management, and integrate cleanly into existing laboratory or production data environments. The organizations winning adoption are those that align instrumentation capabilities with practical workflow outcomes rather than competing solely on specification sheets.
Supply Chain, Consumables, and Cost Structure Dynamics
Cost structures in the Karl Fischer titrators market are influenced by both hardware economics and ongoing consumable requirements. Instrument pricing remains important, but total cost of ownership is increasingly defined by reagent consumption, titer verification frequency, maintenance intervals, and the operational cost of downtime. The stability of standard methanol solvents and the recurring need for titer checks illustrate how consumable behavior can affect laboratory budgeting and staffing. At the same time, efforts to develop more stable or eco-friendly titration reagents are gaining traction. A notable partnership in mid-2025 between a major instrument manufacturer and a leading chemical producer focused on co-developing eco-friendly titration reagents for Karl Fischer applications, signaling that reagent innovation is becoming a strategic pillar rather than a back-end supply detail. For end users, better reagent stability translates into fewer corrective checks and more predictable consumable planning; for manufacturers, it opens avenues for differentiated reagent ecosystems and longer service intervals.
Competitive Landscape and Strategic Positioning
Established Leaders and Their Differentiation Plays
The competitive field is anchored by a mix of globally established analytical instrumentation firms and specialized manufacturers with strong regional or application-specific footprints. One of the leading Swiss providers has built its position around a broad portfolio spanning volumetric and coulometric platforms, including models designed for liquid, solid, and gaseous sample types. Its recent emphasis on AI-assisted calibration and remote diagnostics reflects a strategy centered on reducing operational uncertainty and extending service reach beyond the laboratory door. By embedding intelligence into calibration and support workflows, the company aims to reinforce trust in measurement results while lowering the hidden costs of troubleshooting and repeat analysis.
A major U.S.-based instrumentation player has pursued a parallel but distinct path, focusing on automatic titration systems and high-precision moisture analysis workflows. Its product lineup includes volumetric and coulometric options, complemented by oven autosampling capabilities that support higher throughput and broader sample handling. The strategic logic here is clear: by pairing precise titration chemistry with automation and robust application support, the company addresses the needs of laboratories that must handle larger sample volumes while maintaining compliance-grade data quality. This automation-led positioning is particularly relevant in environments where operator time and method consistency are under pressure.
Another prominent European analytics group has strengthened its presence through automatic titration platforms engineered for both volumetric and coulometric water determination, with connectivity-oriented design elements such as integrated interface sockets for expanded system integration. This connectivity focus aligns with the broader industry movement toward instruments that can sit within larger analytical or laboratory data ecosystems rather than functioning as isolated devices. Meanwhile, a Japanese manufacturer has carved out a recognizable position through dedicated moisture titration series and proprietary reagent formulations, emphasizing precision and application-specific reliability. Its product range spans coulometric and volumetric models designed for automated moisture analysis, reinforcing the importance of matched reagent-instrument systems in delivering consistent results.
Moisture Analyzer Market
U.S.-based specialty manufacturers have also maintained meaningful positions, particularly where application focus sharpens competitive advantage. One company has concentrated on coulometric titrators for petroleum, petrochemical products, oils, and solvents, an application segment where moisture control is tightly linked to product quality and processing efficiency. Another major water analysis and instrumentation supplier offers automatic Karl Fischer titrators suited to both laboratory and process applications, reflecting the value of versatile platforms that can bridge analytical and near-process environments. A further U.S. provider emphasizes customizable volumetric titration setups for laboratory moisture analysis, appealing to organizations that prioritize flexibility in method configuration and sample handling.
In Japan, another electronics and instrumentation manufacturer has contributed to the market with moisture titrators supported by dedicated reagent systems designed for industrial sample analysis, underscoring the continued relevance of regional engineering expertise and application-tuned reagent chemistry. At the same time, Chinese manufacturers have been expanding their presence with cost-competitive titrator platforms that combine practical specifications with upgraded firmware and electrode systems. Recent updates from one Chinese manufacturer highlighted improved measurement stability through firmware and electrode enhancements, illustrating how emerging competitors are moving beyond price competition toward capability refinement. Another Chinese firm has promoted titrator solutions with defined polarization current and repeatability characteristics, appealing to buyers who need predictable performance at accessible price points.
Market Evolution: Consolidation, Differentiation, and New Entry Points
The competitive landscape is evolving along three concurrent paths. First, established leaders are deepening differentiation through software, automation, and service connectivity rather than hardware novelty alone. The most valuable platforms are increasingly those that reduce operator burden, improve calibration confidence, and support secure, auditable data practices. Second, application specialization remains a viable and often underappreciated route to competitive strength. Companies that tailor their titration platforms, reagents, and workflow support to specific industries or sample types can build durable demand even in a concentrated market. Third, new and expanding entrants are challenging the assumption that advanced titration capabilities are the exclusive domain of large multinational firms. By improving measurement stability, offering practical specifications, and targeting cost-sensitive segments, these players are widening the competitive field and pressuring incumbents to justify premium positioning through demonstrable workflow and compliance benefits.
For buyers and investors, this evolution means that competitive advantage is less about brand familiarity and more about fit: fit between instrument capabilities and sample workflows, fit between reagent systems and verification frequency, and fit between software architecture and regulatory or cybersecurity expectations. The organizations that can articulate and deliver that fit will be best positioned to defend share and expand into adjacent application areas.
Forward Outlook: Three Strategic Trends to Watch
Trend 1: Intelligence and Remote Support as Standard Expectations
Over the next three to five years, AI-assisted calibration, predictive diagnostics, and remote support capabilities are likely to transition from differentiators to baseline expectations in the Karl Fischer titrators market. The recent introduction of platforms featuring AI-based calibration and remote diagnostics, alongside firmware and electrode upgrades aimed at measurement stability, indicates that the industry is already moving in this direction. For manufacturers, this trend creates opportunities to design instruments that reduce downtime, simplify maintenance planning, and improve result consistency across operators and sites. For end users, the commercial implication is clear: instrumentation that supports fewer interruptions, more reliable calibration states, and faster issue resolution can lower the hidden costs of moisture analysis and improve laboratory throughput. The principal risk is that intelligence features become commoditized quickly, shifting the competitive battleground toward data security, integration depth, and long-term service economics rather than feature presence alone.
Trend 2: Compliance and Cybersecurity as Procurement Filters
Regulatory and cybersecurity requirements will increasingly shape purchasing decisions, particularly in regulated industries and multi-site laboratory environments. Compliance with data integrity expectations and broader resilience mandates is pushing organizations to evaluate instruments not only on analytical performance but also on software governance, user access control, validation support, and update management. This trend favors manufacturers that have built compliance-friendly architectures and can provide clear documentation and support pathways. It also creates a practical opportunity for vendors to bundle instrumentation with services that help laboratories maintain validated states while adapting to evolving security requirements. The uncertainty lies in the pace and variability of regulatory interpretation across regions, which may lead to uneven adoption timelines and divergent compliance expectations that complicate global deployment strategies.
Trend 3: Reagent Innovation and Field-Ready Deployment Expanding Use Cases
Two related developments are likely to broaden the market's application base and change how moisture analysis is deployed. First, reagent innovation focused on improved stability and environmental profile is gaining momentum, with partnerships aimed at co-developing eco-friendly titration reagents signaling a longer-term shift in consumable strategy. If these efforts translate into reduced titer drift and more predictable handling, they can lower the operational burden of routine verification and improve cost predictability for end users. Second, the expansion of portable and ruggedized moisture analysis tools with wireless connectivity is extending Karl Fischer-based measurement into field and process-adjacent settings. This opens opportunities in industries where sample transport to a central laboratory creates delays or where on-site decisions depend on rapid moisture data. The commercial opportunity for manufacturers lies in building platforms that combine dependable analytical performance with practical field usability and consumables that hold up under varied operating conditions. The risk is that broader deployment also exposes instruments to more demanding environments, increasing the importance of robustness, training, and support infrastructure.
Strategic Implications for Decision Makers
For Manufacturers and Solution Providers
Positioning should increasingly revolve around workflow outcomes rather than isolated specifications. Investments in automation, smarter calibration logic, electrode and firmware stability, and secure software architecture are likely to yield stronger competitive returns than incremental hardware changes alone. Equally important is the reagent and consumables strategy: improving reagent stability, offering clearer titer management guidance, and aligning reagent formulations with instrument performance can reduce customer friction and create defensible ecosystem advantages. Manufacturers should also prepare for compliance-driven procurement by ensuring that documentation, data handling, and update processes support auditable, validated operations without imposing disproportionate administrative burden on end users.
For Investors and Strategic Planners
The market's growth trajectory is steady, but value creation will be uneven. The most attractive opportunities are likely to emerge where technology, compliance readiness, and application fit intersect. Investors and planners should look beyond top-line growth and assess which companies are building durable advantages through software-enabled reliability, reagent ecosystem strength, and service models that reduce total cost of ownership. Interest in field-deployable and connected moisture analysis also suggests that adjacent use cases may expand demand beyond traditional laboratory settings. At the same time, concentration in the market means that competitive disruptions are more likely to come from capability upgrades by emerging players or from application-specific specialization than from broad-based price wars. Monitoring firmware, electrode, and reagent innovations, as well as partnerships that reshape consumable offerings, will provide early signals of shifting competitive dynamics.
For Procurement and Operations Leaders
Procurement decisions should weigh total cost of ownership more heavily than initial purchase price. Key evaluation criteria should include calibration and titer management burden, automation and sample handling capabilities, data integrity and software governance features, reagent stability expectations, and the vendor's ability to support validated or regulated environments. Where moisture analysis is tied to high-volume workflows or compliance-critical applications, instruments that reduce operator intervention and improve measurement repeatability can deliver meaningful operational savings over time. Procurement teams should also consider deployment context: laboratory-bound systems, process-adjacent setups, and field applications have different robustness, connectivity, and support requirements, and matching the platform to the environment can prevent underperformance and unnecessary service costs.
The Karl Fischer titrators market is entering a period in which analytical precision, operational efficiency, and compliance readiness must advance together. Organizations that treat moisture analysis as a strategic workflow rather than a routine test will be better positioned to capture the value of upcoming technological and regulatory shifts. For those seeking a more detailed breakdown of segmentation dynamics, regional adoption patterns, application-specific demand drivers, and competitive benchmarks to support internal planning, the full research report provides a deeper evidence base and tailored scenario guidance.
For detailed analysis of this topic, please visit the official page: Karl Fischer Titrators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


